

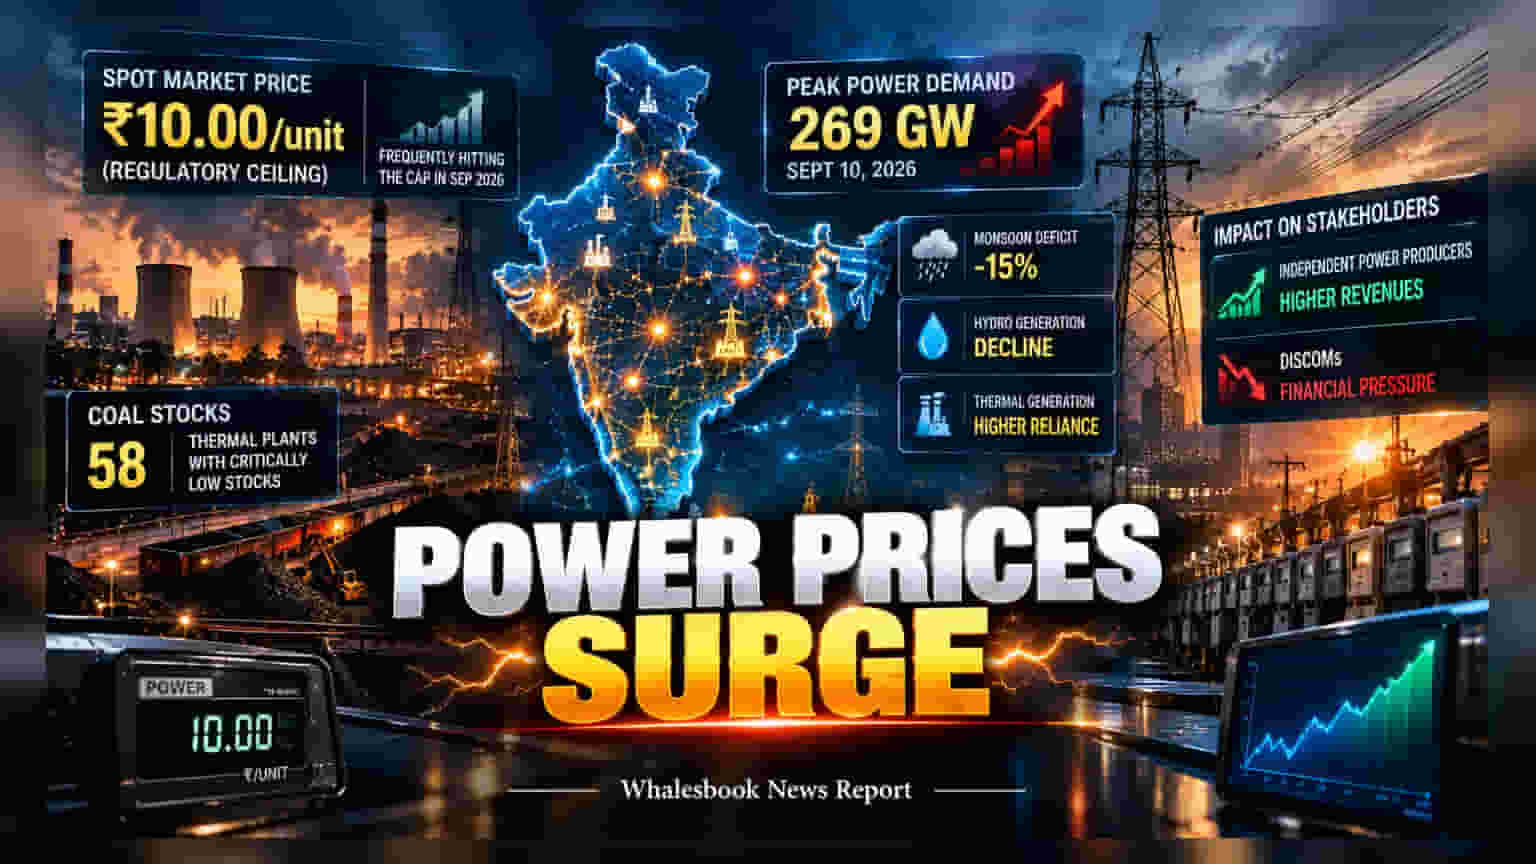
India’s spot electricity prices have reached 2026 peaks as peak power demand hit 269 GW in September. A 15% monsoon rainfall deficit has reduced hydropower generation, forcing an increased reliance on thermal plants amid tight coal stocks. Investors are tracking how this price surge impacts independent power producers versus the increased cost burden on state distribution utilities.
Electricity prices in the Indian spot market have reached their highest levels of 2026, driven by an unusual surge in power demand and a weak monsoon season. Data from the Indian Energy Exchange shows that market clearing prices have frequently touched the regulatory ceiling of Rs 10 per unit in September. This price spike reflects a severe imbalance between the country’s record-breaking consumption and the available supply.
Demand Surge and Grid Pressure
India recorded a peak power demand of 269 GW on September 10, 2026, a level rarely seen outside of the peak summer months. This sustained high demand has been fueled by a 15% rainfall deficit across the country, which has hampered agricultural and rural output while simultaneously forcing a shift in power generation. Because the monsoon has been weaker than expected, hydropower generation—a key source of clean, base-load power—has declined. This has forced the national grid to rely heavily on thermal power plants to keep up with the rising needs of industrial and residential users.
Coal Stock Constraints
The increased reliance on thermal generation is testing the country’s fuel supply chain. By early September, approximately 58 thermal power plants reported critically low coal stocks. This inventory pressure creates a risk for power producers, as any disruption in fuel delivery could impact their ability to generate electricity during these high-demand periods. For investors, this supply-side bottleneck is a critical factor to watch, as it limits how much companies can actually benefit from higher market prices.
Impact on Producers and Utilities
Independent power producers with merchant or uncontracted capacity are in a position to see higher revenues from the current pricing environment. When market prices rise, these companies can sell surplus power at better rates. However, the potential for higher margins is balanced by regulatory realities. The power sector operates under administrative price caps, which prevent spot prices from rising indefinitely, thereby limiting the maximum gain for generators even when demand is extreme.
Conversely, the situation places significant financial pressure on state-owned power distribution companies, or DISCOMs. These utilities are often required to provide continuous power to their consumers regardless of cost. When they are forced to purchase expensive electricity from the spot market to cover local shortages, it hurts their financial health. Investors often track this, as weak DISCOM financials can lead to payment delays for power generators.
What Investors Should Track Next
The sustainability of these price levels depends on a few specific factors. First, any recovery in monsoon rainfall would likely relieve the pressure on the grid by improving hydro generation. Second, the inventory levels of coal at thermal plants remain the primary monitorable for operational stability. Finally, any changes to the regulatory price caps on the power exchange could either limit or expand the revenue potential for power producers in the coming months.