

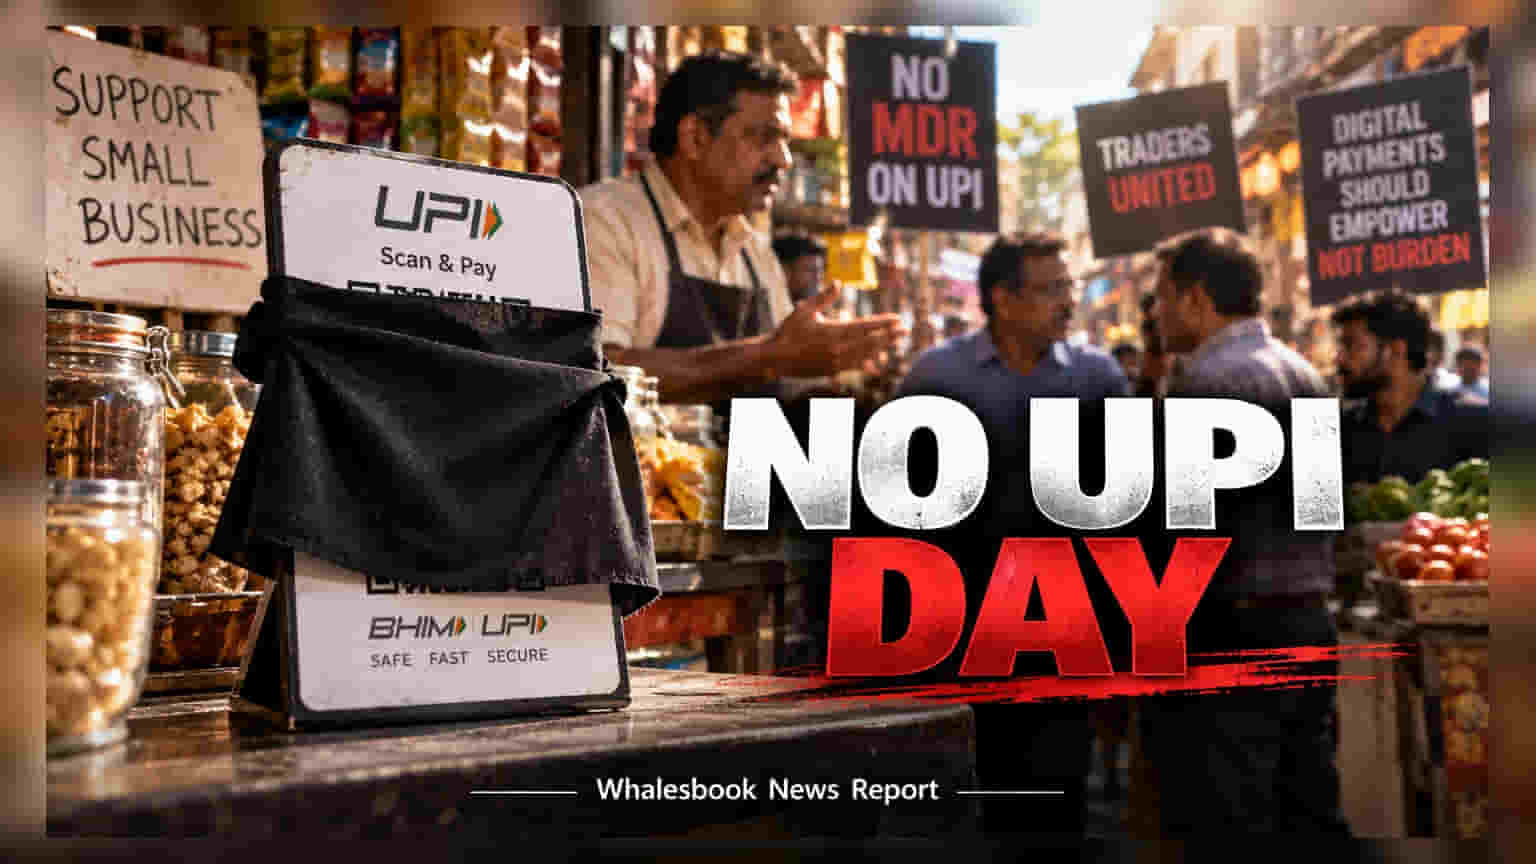
Business associations in Madhya Pradesh have launched a protest against a proposed 0.4% Merchant Discount Rate (MDR) on UPI transactions above ₹2,000. Shopkeepers are demanding the withdrawal of this levy before the planned October 15 rollout. This policy shift marks a significant friction point for the digital payments ecosystem, raising questions about future adoption and merchant cost structures.
Trade organizations across major business hubs in Madhya Pradesh, including Indore, Bhopal, Gwalior, and Jabalpur, staged a 'No UPI Day' protest on September 23, 2026. Retailers and small business owners masked their QR codes with black cloth to signal their opposition to the government's upcoming plan to introduce a 0.4% Merchant Discount Rate (MDR) on all UPI transactions exceeding ₹2,000. This protest, coordinated by groups like the Ahilya Chamber of Commerce and Industry, represents a direct clash between small business owners and the evolving regulatory framework for India's digital payment infrastructure.
The core of the dispute lies in the transition of UPI from a completely fee-free model to one where merchants may have to absorb processing costs. For years, the lack of an MDR has been a major factor driving the rapid adoption of UPI among small merchants who operate on thin margins. Business representatives argue that imposing a levy—even at 0.4%—will increase operational expenses and could disincentivize digital payments at the grassroots level. The leadership has issued an ultimatum, stating that the policy must be revoked before the October 15 implementation date, or they will consider further measures, including the symbolic disposal of digital payment hardware.
From a regulatory and economic perspective, the government has stated that the move is intended to ensure the long-term sustainability of the UPI ecosystem. As transaction volumes have scaled massively, the infrastructure requires significant investment to maintain processing speeds and reliability. Officials have clarified that the cost structure is designed to apply only to the merchant side of the transaction to cover these ballooning processing overheads, rather than charging the end-user.
For investors, this development is a critical monitorable for the fintech and digital payments sector. If the policy is implemented as planned, it could create a new revenue stream for the entities involved in the payment value chain. However, the strong resistance from the retail community underscores the risk of reduced digital transaction volumes if merchants choose to steer customers toward cash to avoid the fee. Furthermore, any company with a high concentration of UPI-based merchant services may face temporary headwinds if retailer adoption slows or if the policy is delayed or altered due to ongoing protests. Investors should track the government's response to these demands and the potential for a compromise that balances ecosystem sustainability with merchant affordability. The next few weeks, leading up to the October 15 deadline, will be crucial in determining the path forward for digital payment pricing in the country.