

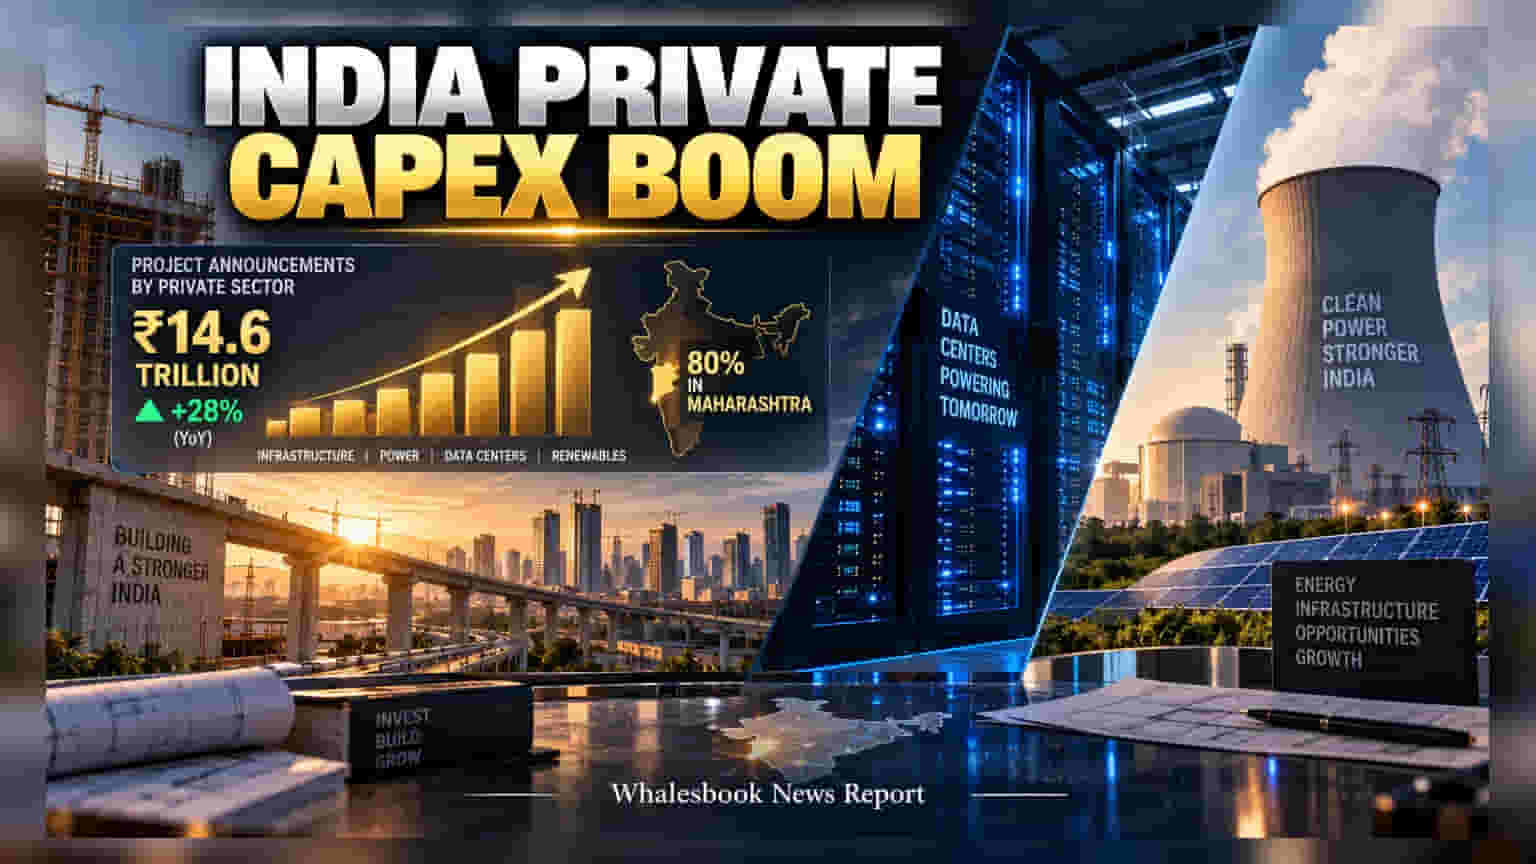
India’s private sector investment rose 28% to Rs 14.6 trillion in Q1 FY27, accounting for 90% of new projects. However, investors face a reality check as the value of shelved projects has jumped 600%, largely due to canceled railway corridors. This highlights a growing gap between project announcements and actual execution.
The landscape of Indian investment is seeing a major shift, with the private sector taking the lead in new project announcements during the first quarter of FY27. According to data, private companies accounted for 90% of all new projects, committing Rs 14.6 trillion. This marks a 28% increase compared to the same period last year. Notably, there is a strong regional concentration, with 80% of these new project announcements originating in Maharashtra.
The Gap Between Announcement and Execution
While the rise in announced investment is significant, the actual progress on the ground remains a concern for investors. The total value of projects currently under implementation has grown by only 5% year-on-year, reaching approximately Rs 204 trillion. More importantly, the completion rate of these projects has declined by 17%. A stark indicator of this execution risk is the 600% spike in the value of shelved projects, a surge largely caused by the cancellation of three major railway corridors, including the Thiruvananthapuram-Kasargod and Pune-Nashik lines. For investors, this suggests that the high volume of new announcements does not always translate into successful project delivery.
Government Spending and Sector Trends
Public spending continues to act as a stabilizer for the investment cycle. The central government has increased its capital spending, with defense and road infrastructure seeing a 41% rise as of July. Public Sector Undertakings have also improved their budget use to 40%, up from 36% in the previous year. This consistent public funding has provided a base for sectors like electrical equipment, which recorded a 28% growth in output.
Specific sectors continue to drive the investment wave, particularly power, data centers, and renewable energy. Power capacity additions have reached 22 gigawatts so far in FY27, with renewable energy contributing more than 20 gigawatts of that total. Transmission infrastructure, led by companies like Power Grid, is also expanding to support this power connectivity. However, the outlook for Engineering, Procurement, and Construction firms remains cautious. Many of these companies rely on export markets in the Middle East, where order awards are still lower than pre-conflict levels, potentially pressuring their growth.
Investors should closely track the difference between planned projects and those that reach completion. Moving forward, the financial strength and execution track record of companies will be more important than just their ability to announce large new projects. The ability of firms to maintain domestic order books will also be a key factor to monitor as global economic conditions moderate.