

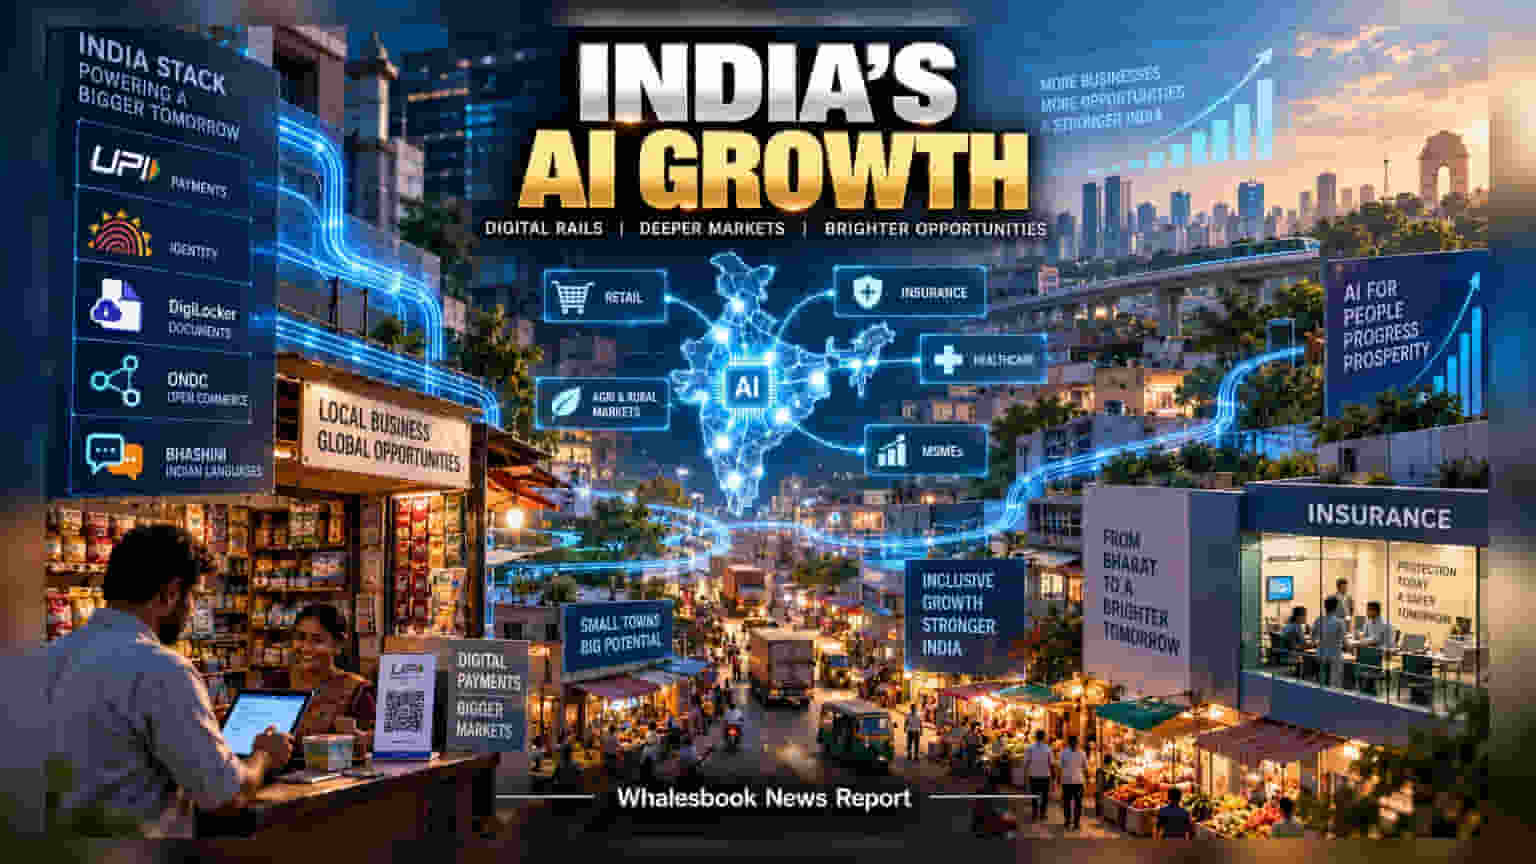
India is upgrading its public digital platforms with AI to help businesses reach new customers in smaller towns. While this shift aims to lower customer costs and boost service, investors should track how firms manage data security and operational quality rather than just tech adoption.
India’s digital public infrastructure, often referred to as the "India Stack," is entering a new phase. For years, these systems—including UPI for payments, Aadhaar for identity, and DigiLocker for document storage—focused on simply connecting users to the digital economy. Now, the focus is shifting toward integrating artificial intelligence into these shared frameworks to drive business growth.
Expanding Market Reach Through Tech
For companies, this evolution is about more than just efficiency; it is about reaching profitable scale in markets that were previously hard to serve. Through platforms like the Open Network for Digital Commerce (ONDC) and language tools like BHASHINI, businesses can now potentially serve customers in smaller cities and rural areas without needing to build their own massive physical networks.
By using these shared digital rails, companies can interact with customers in local languages and streamline logistics. For an investor, the key benefit is a potential reduction in customer acquisition costs. If a company can reduce the money spent on finding and onboarding a new customer through these automated public systems, it could lead to better profit margins over time. However, this relies on the company’s ability to successfully integrate their own services with these public systems.
The Insurance Registry and Financial Data
Financial services are also seeing a major shift. The Insurance Regulatory and Development Authority of India has been working on concepts like the Public Insurance Registry, often discussed alongside initiatives like Bima Sugam. The goal is to create a unified database of policyholders.
If implemented, this could significantly change how insurance companies operate. Instead of waiting for a claim to be filed, insurers could use this consolidated data to proactively manage risk and offer personalized coverage. This transition from reactive service to proactive risk management could improve transparency and trust, which are long-standing challenges in the insurance sector.
Why Execution Matters More Than Tech
While the integration of AI and public infrastructure offers growth potential, investors should be cautious. Simply deploying a chatbot or connecting to an open network does not guarantee profit or customer loyalty. The fundamental business risks remain the same: service quality, data accuracy, and delivery execution.
If a company uses these digital rails but fails to deliver the actual product or service, it only leads to faster customer frustration and reputational damage. The responsibility for the end experience—and the data handling—remains with the individual company, not the public infrastructure provider.
Investors should monitor how companies utilize these shared frameworks to solve real customer problems, rather than just using them for marketing automation. The next important step for companies will be to demonstrate that these tools are actually leading to lower operational costs, higher customer retention, and improved service reliability in their quarterly financial reports. Tracking how early adopters of these platforms manage their customer acquisition costs and service complaints will be a useful indicator of their success.