

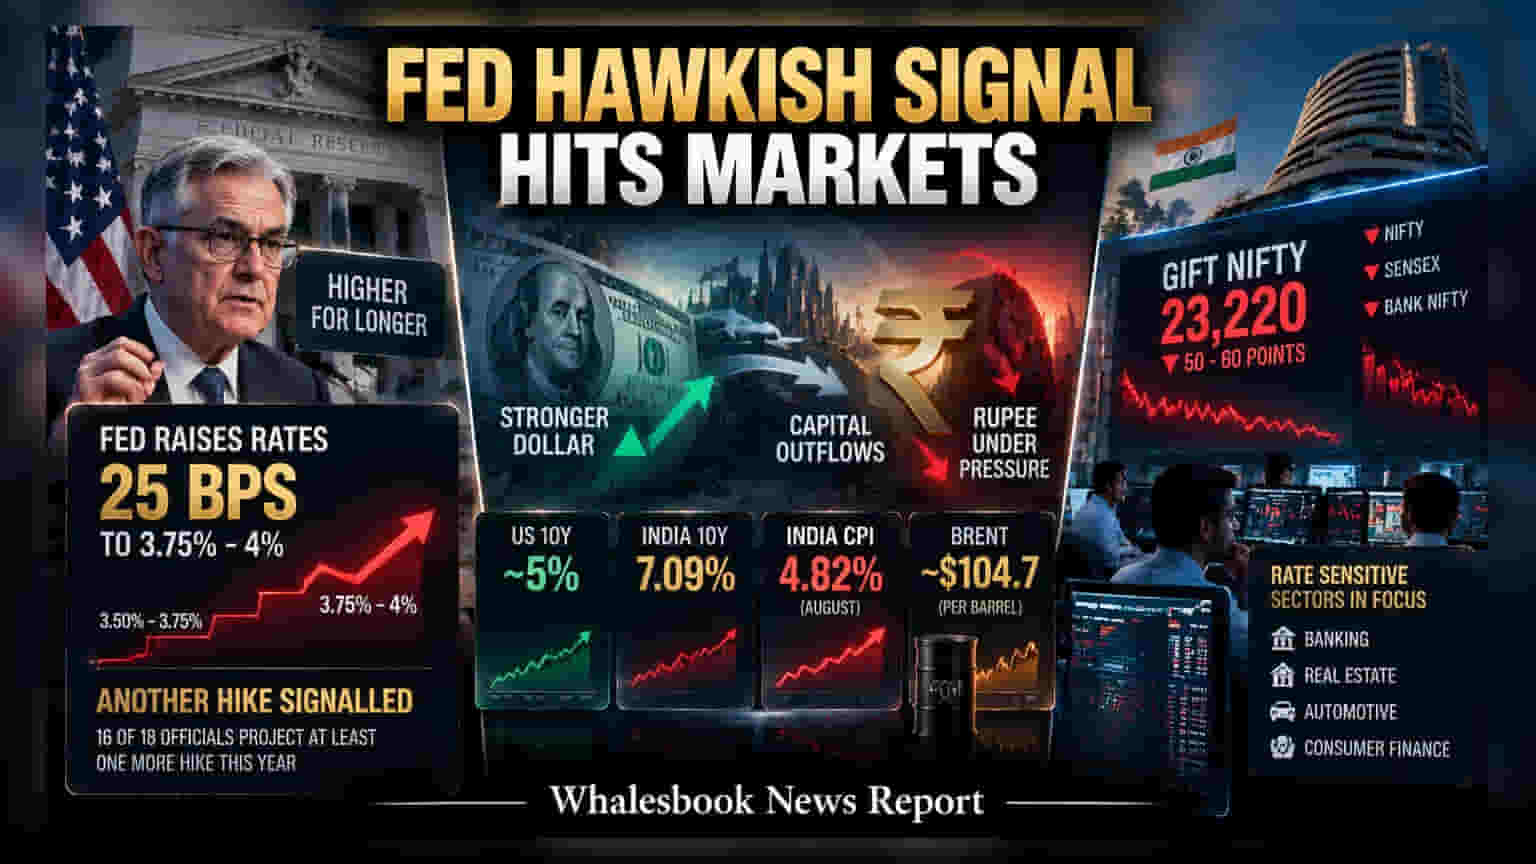
Indian stock markets are expected to open lower on September 17, 2026, following the US Federal Reserve's decision to hike interest rates by 25 basis points. Higher US yields and a stronger dollar, combined with rising domestic inflation in India, have created a cautious sentiment for investors.
Indian equity markets are signaling a cautious opening for the September 17 trading session, with early indicators like the GIFT Nifty suggesting a decline of around 50 to 60 points. This negative sentiment follows the US Federal Reserve’s decision to raise its policy interest rates by 25 basis points, moving the target range to 3.75%-4%.
The central bank's move has brought 'higher-for-longer' interest rate expectations back to the center of market discussions. With 16 out of 18 Fed officials projecting at least one more rate increase before the end of the year, investors are adjusting to a restrictive global monetary environment. This environment often strengthens the US dollar and pushes up Treasury yields, both of which can reduce the appeal of assets in emerging markets like India by making dollar-denominated investments appear more attractive to global capital.
Impact on Indian Markets
The ripple effects of the Fed's decision are being felt through multiple channels. When US bond yields climb—the 10-year Treasury yield is currently hovering above 5%—it often pressures the Indian rupee and makes it more expensive for companies to borrow money. For domestic investors, this translates into heightened scrutiny for rate-sensitive sectors. Companies in industries like banking, real estate, and automotive, which often rely on loans for expansion or consumer financing, may face increased pressure if borrowing costs remain elevated for an extended period.
Adding to this complexity is the domestic inflation picture. India's consumer price inflation rose to 4.82% in August, up from 4.45% in July. This upward trend limits the Reserve Bank of India’s flexibility to provide monetary support to the economy. With domestic borrowing costs already under pressure due to higher global yields and persistent local inflation, the ability for companies to maintain profit margins will be a key factor for market participants to watch in the coming quarters.
Competing Forces
While monetary policy is creating headwinds, there is a minor source of relief in the form of energy costs. Brent crude prices have eased toward $104.7 per barrel. As India is a significant importer of oil, a reduction in energy prices can help manage the country's trade balance and provide some support against inflationary pressures. However, oil prices remain elevated enough that they continue to act as a significant drag on both the economy and company input costs.
Moving forward, volatility is expected to remain high as the market reacts to shifting expectations. Investors will likely track the movement of the US Dollar Index, foreign portfolio investment flows into Indian equities, and the 10-year government bond yields as primary indicators of market health. Any further commentary from the Reserve Bank of India regarding its interest rate trajectory will also be a critical monitorable for investors assessing the future earnings outlook for Indian corporates.