

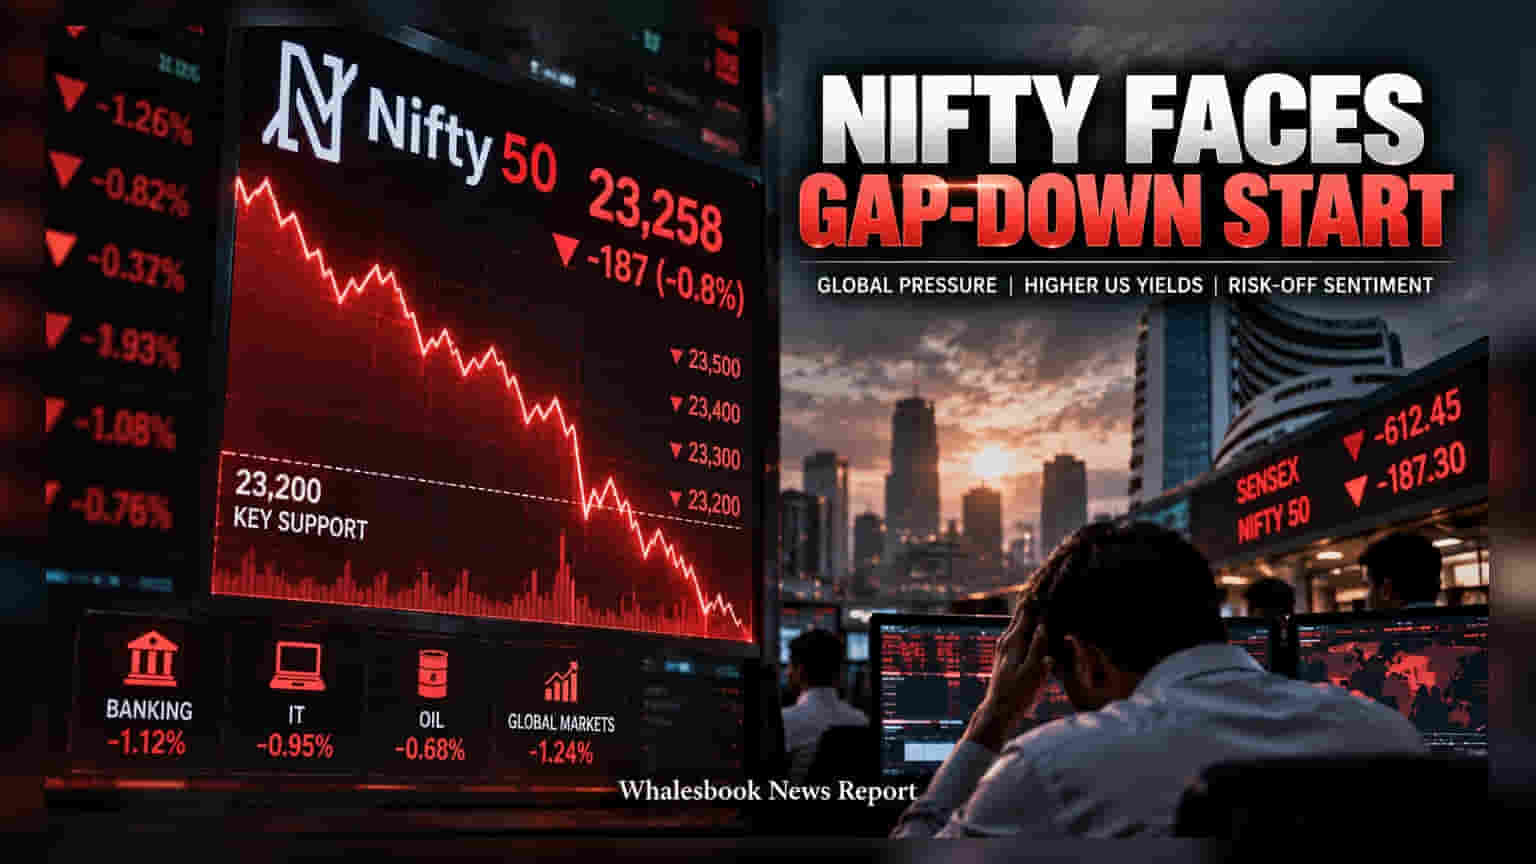
Domestic equity benchmarks are expected to open lower today, with GIFT Nifty indicating a decline of 187 points. The negative sentiment follows a selloff on Wall Street, driven by rising US Treasury yields and renewed concerns over Federal Reserve interest rate policies, which often pressure emerging markets.
Indian benchmark indices, the Sensex and Nifty, are set for a weak opening on Thursday. GIFT Nifty data is trading at 23,258, signaling a drop of approximately 187 points, or 0.8 percent, compared to Wednesday's closing level. This anticipated decline comes as global investor sentiment shifts following a selloff in US markets.
The pressure on global markets is primarily due to rising US 10-year Treasury yields, which have reached their highest levels since 2007. When US yields rise, these bonds become more attractive to global investors, which can lead to capital moving away from emerging markets like India. Strong business activity data from the US has fueled market expectations that the Federal Reserve may maintain or even increase interest rates, creating a risk-off environment for equity investors.
While the market sentiment is cautious due to global macro factors, institutional activity on Wednesday showed some resilience. Data from the exchanges revealed that foreign institutional investors net-bought Indian equities worth Rs 1,600 crore, while domestic institutional investors added Rs 2,341 crore. This suggests that while global sentiment is weak, domestic demand remained steady in the previous session, potentially providing some support as markets digest the overnight developments.
Technical analysts are focusing on the 23,200 level for the Nifty as a crucial support zone. If the index fails to hold this level during the opening trade, it could indicate further weakness in the near term. Conversely, the market will face immediate resistance around 23,500. Investors are often watchful of banking and IT sector stocks during such global volatility, as these sectors are generally more sensitive to shifts in interest rates and currency fluctuations.
Oil prices also remain a key monitorable. While Brent crude futures have eased to $102.13 a barrel in early Asian trade, the recent volatility in energy costs continues to affect the outlook for import-dependent economies. The primary focus for the trading day will be on whether the index can stabilize above the 23,200 support level after the initial selloff.