

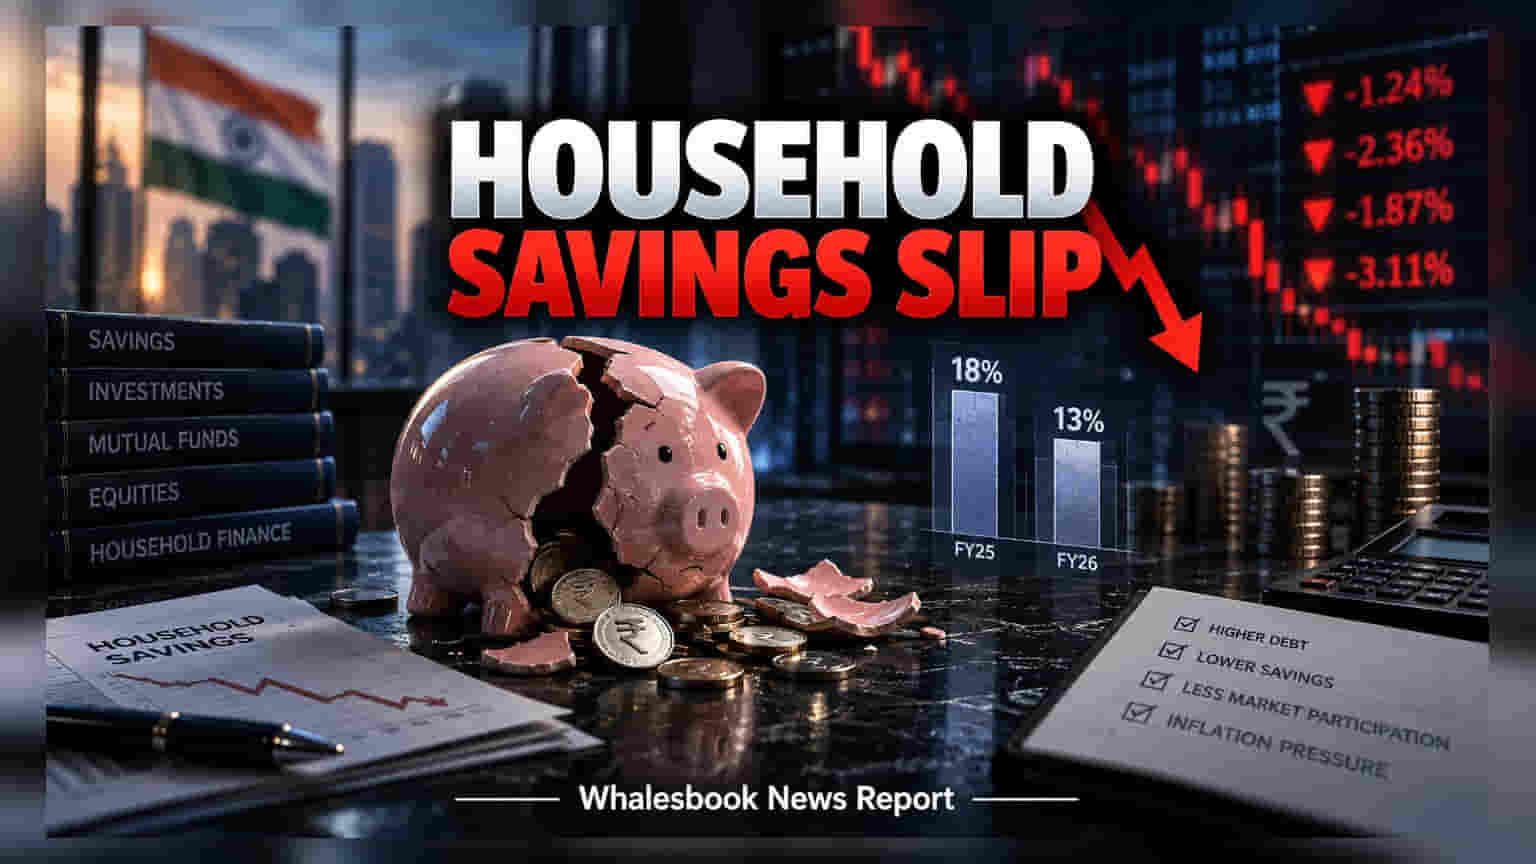
Net household financial savings fell to 6.2% of GDP in FY26, while debt-to-GDP reached 49%. Retail investors are shifting capital from stocks to bank deposits, reflecting lower liquidity. With a 15% monsoon deficit and rising inflation, investors are now watching for potential RBI policy changes and their impact on consumption.
Data for the financial year 2026 shows a shift in the financial habits of Indian households, with net financial savings dropping to 6.2% of GDP compared to 7% in the previous year. This decline is notable because it falls below the long-term average of 7.9% recorded since 2010. The primary reason for this trend is a rise in household debt, which has pushed the debt-to-GDP ratio to 49%, exceeding the typical 45% seen in similar emerging economies.
Impact on Market Participation
This shift has direct consequences for the stock market. With debt levels rising, households have less disposable income to invest in financial assets. The data highlights a distinct change in behavior: allocation into mutual funds and equities contracted to 13% in FY26, down from 18% in FY25. Instead, families are increasingly moving their remaining savings into safer, more liquid options like bank deposits and holding cash. For the stock market, this suggests a potential reduction in the flow of retail liquidity that has historically driven equity momentum.
Macroeconomic Pressures
Beyond individual savings, the broader economic environment is facing structural challenges that could influence corporate earnings and market sentiment. A 15% monsoon deficit, the lowest level since 2009, poses a threat to agricultural productivity and the rabi harvest. This, combined with firming global crude oil prices, is contributing to inflationary pressure. When inflation remains sticky, consumer demand for non-essential goods often slows down, which can directly affect the profit margins of listed companies in the consumption sector.
Future Policy Outlook
The Reserve Bank of India is facing a complex situation. With liquidity levels shifting, analysts are discussing the possibility of a move toward a more hawkish policy—meaning the central bank might aim to tighten money supply to manage inflation. If the RBI decides to use tools like open market operations to soak up liquidity, interest rates could remain elevated. For investors, the key monitorable will be the upcoming central bank commentary on monetary policy, as any shift could impact the cost of borrowing for companies and influence overall market valuations. Investors should also track upcoming inflation data and consumption patterns reported by listed companies, as these will provide the clearest picture of how household finances are affecting the real economy.