

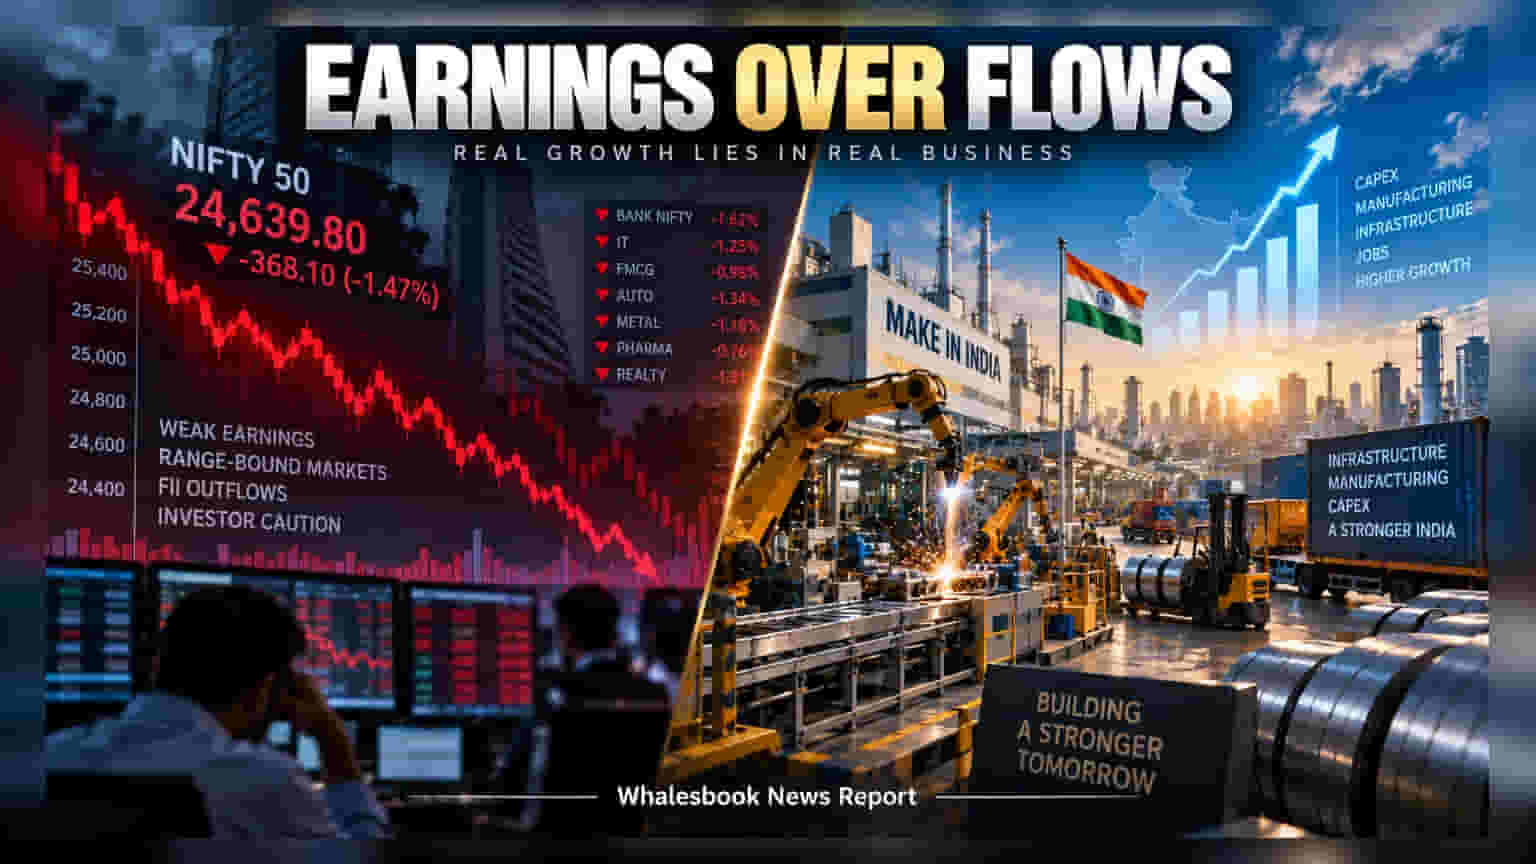
Indian stock markets are struggling not just due to foreign outflows, but because of stagnant large-cap earnings over the last two years. While benchmark indices show limited growth, analysts suggest focusing on long-term opportunities in manufacturing and infrastructure sectors. Investors may look beyond index tracking to identify companies benefiting from domestic capital spending and structural economic shifts.
The Indian equity market has seen a period of volatility, with major indices struggling to deliver the growth investors have become accustomed to. While many observers often blame Foreign Institutional Investor (FII) outflows for the recent sluggishness, market data suggests the underlying issue is more fundamental. The core reason for the market lag appears to be a two-year stretch of muted earnings growth among large-cap companies, which has effectively capped the potential for these indices to climb higher.
Why Large-Cap Earnings Matter
When large-cap companies—those with the biggest market value—do not grow their profits, the entire benchmark index struggles to gain momentum. Over the past 24 months, many of these giants have faced challenges ranging from global demand weakness to internal cost pressures. When these companies fail to deliver earnings growth, investors often pull back, and the market becomes more sensitive to performance gaps than to temporary fluctuations in foreign investment flows. Investors should remember that in the long run, stock prices generally follow the path of corporate earnings. If earnings remain flat, index returns are likely to remain range-bound.
Shifting Focus to Manufacturing and Capex
As the Nifty and other large-cap indices struggle, a shift is occurring in how investors identify value. Rather than sticking to traditional index-heavy strategies, there is a growing trend toward looking at sectors that have historically been sidelined. The national economic focus has moved toward manufacturing, infrastructure, and capital expenditure. These sectors are becoming the new engines of potential growth, fueled by domestic production cycles and government initiatives aimed at boosting local capacity.
This transition means the next wave of corporate winners may not come from the consumer-focused large caps that dominated the last decade, but from industrial firms building out the country's physical and digital capacity. For an investor, this change suggests that chasing index returns might be less effective than picking specific businesses that are successfully tapping into these structural trends.
Risks and What to Watch Next
While the long-term outlook for the Indian economy remains supported by favorable GDP projections and urban development, this shift is not without risk. Industrial and infrastructure projects often face long execution timelines, cost overruns, and funding challenges. Furthermore, reliance on a domestic manufacturing boom means investors must closely monitor company balance sheets for debt levels, as capital spending requires significant upfront money.
For investors, the most important monitorable is no longer just the daily movement of the Nifty 50. The focus should shift to quarterly earnings quality, specifically looking for companies that can protect their profit margins in a competitive environment. Tracking industrial production data, capital spending announcements by companies, and the successful execution of projects will be more critical than following the short-term noise of foreign investment sentiment.