

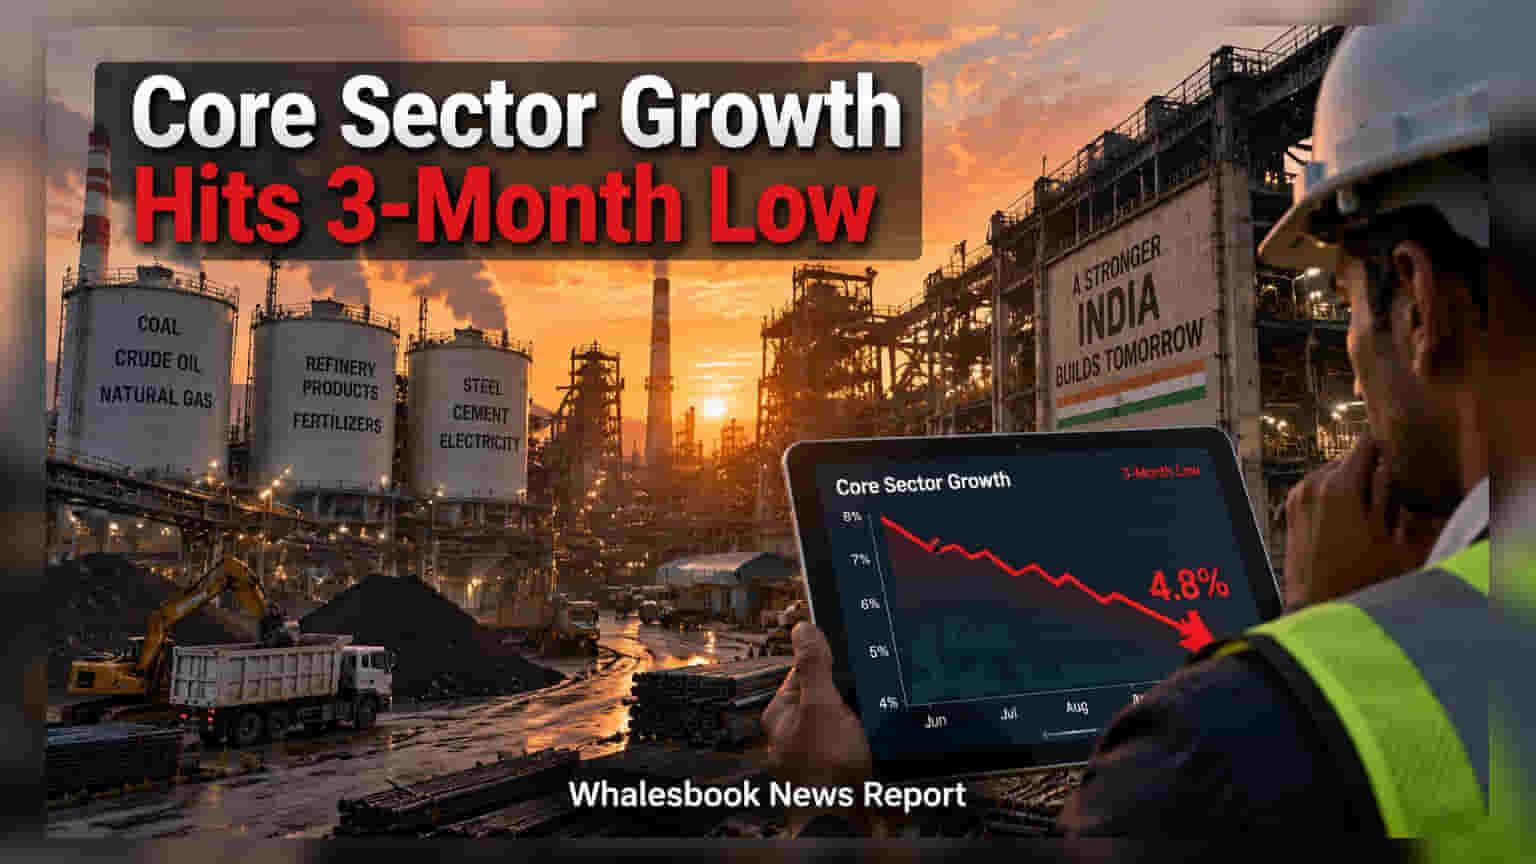
India's eight core sectors grew by 4.8% in August, hitting a three-month low, largely due to a dip in coal, crude oil, and natural gas production. While infrastructure segments like cement and electricity showed strength, investors should watch how potential energy cost increases might affect broader manufacturing margins in the coming months.
India’s core sector output, which serves as a major indicator of the country’s industrial health, slowed to 4.8% in August. This growth rate marks a three-month low and follows a downwardly revised 5% increase in July. These eight core industries—which include coal, crude oil, natural gas, refinery products, fertilizers, steel, cement, and electricity—make up roughly 40.3% of the total Index of Industrial Production (IIP). Because of this large weight, the data often acts as a preview for the country’s overall industrial performance.
The energy complex was the primary reason for the slowdown. Production numbers for natural gas fell by 4.9%, coal dropped by 3.8%, and crude oil production decreased by 3.6%. Analysts have pointed to ongoing instability in West Asia as a factor that may be disrupting supply lines and impacting the efficiency of commodity-heavy industries. When energy production fluctuates, companies across various sectors often face uncertainty regarding input costs and operational planning.
Despite the pressure on energy production, infrastructure-related segments showed resilience. Cement production led the growth with an increase of 12.5%, likely driven by ongoing government capital spending and private construction demand. Electricity generation also remained firm with an 11.6% rise, suggesting that industrial and residential power demand continues to be a steady driver. Steel production saw more moderate growth at 3.4%.
Other sectors faced specific hurdles. Fertilizer production saw a contraction of 12.4%, marking the sixth consecutive month of decline. This drop is largely attributed to a seasonal lull in agricultural sowing activities and a shift toward using more imported fertilizer supplies. Additionally, the iron ore sector experienced a deceleration, with growth slowing to 5.5%.
For investors, the key takeaway is the potential impact of these trends on corporate profit margins. When energy inputs such as coal and natural gas see lower production or supply volatility, it can lead to higher operational costs for manufacturers. If companies cannot pass these higher costs on to their customers through price increases, profit margins may come under pressure. The resilience in cement and electricity suggests that demand in the infrastructure space remains intact, but the broader manufacturing sector faces pressure if energy supply does not stabilize soon.
Moving forward, investors may track upcoming monthly data to see if the energy sector slump continues or if it is a temporary fluctuation. Keeping an eye on government capital expenditure updates and any shifts in global energy prices will also be important, as these factors directly influence the operational costs of the companies listed in these core sectors.