

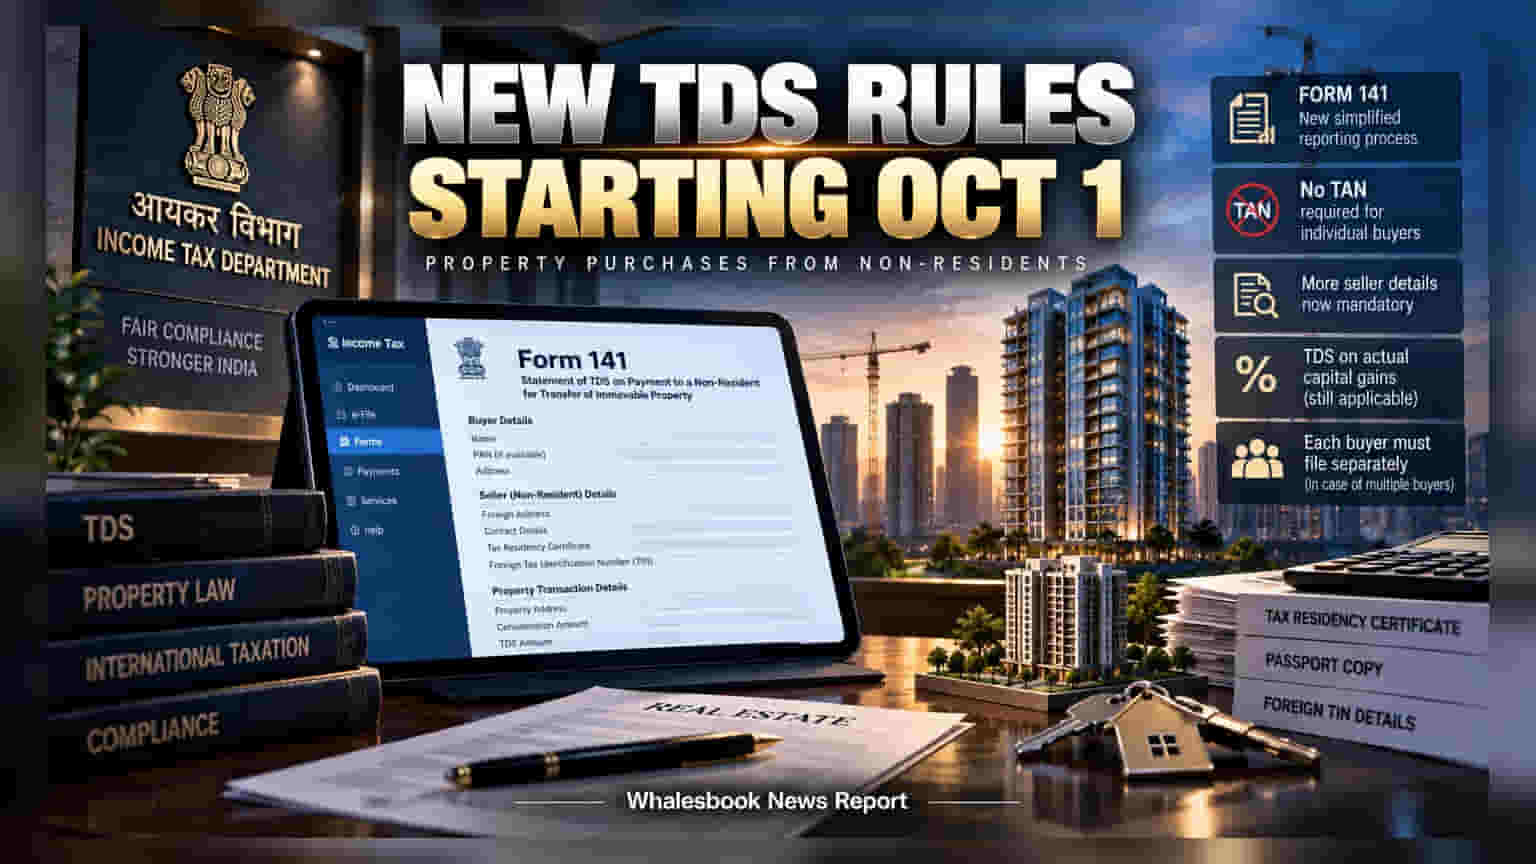
Effective October 1, 2026, the Income Tax Department is introducing Form 141 for residents buying property from non-resident sellers. This simplifies the process by removing the mandatory need for a Tax Deduction and Collection Account Number (TAN). However, buyers must now provide detailed disclosure of the seller’s foreign tax status to ensure better traceability, as the underlying capital gains tax obligations remain strict.
Starting October 1, 2026, the Income Tax Department is changing how resident individuals and Hindu Undivided Families (HUF) handle tax withholding when buying property from non-resident sellers. The new system replaces the previous requirement for buyers to obtain a Tax Deduction and Collection Account Number (TAN) with a simplified reporting method using the new Form 141. Previously, even individual buyers doing a one-time purchase had to register for a TAN, which was a complex administrative process. By removing this requirement, the tax department is trying to make compliance easier for individual buyers while still maintaining control over cross-border transactions.
While the paperwork for the buyer is becoming easier, the level of detail required for reporting is increasing. To ensure that authorities can better track money moving across borders, buyers must now collect and report specific information about the non-resident seller. This includes the seller’s foreign address, contact details, a Tax Residency Certificate, and their foreign Tax Identification Number (TIN) in cases where they do not have an Indian Permanent Account Number (PAN). This data collection is mandatory and helps the government link various payments to ensure that the correct taxes are paid on the transaction.
It is important for buyers to note that while the reporting process has changed, the actual tax rules have not. Buyers are still required to withhold tax based on the capital gains applicable to the non-resident seller, which includes any applicable surcharge and cess. This is distinct from the 1 percent tax deduction rate typically applied when buying property from a resident seller. Furthermore, the ₹50 lakh threshold, which often grants relief for resident transactions, does not apply here.
In scenarios where multiple buyers are involved in a single transaction, every buyer must file their own Form 141. Additionally, the buyer must issue a TDS certificate in Form 132 to the seller within 30 days after the month in which the tax was deducted. Failing to provide the correct tax identification or residency documentation will likely lead to tax being withheld at a higher rate. For property buyers, the key monitorable is ensuring that all necessary documents and foreign tax details are collected from the seller well in advance to avoid any issues with the tax authorities or delays in the transaction process.