

Global markets are focused on the upcoming Trump-Xi summit and US Federal Reserve policy signals as the rupee trades at 95.88 against the dollar. Investors are monitoring how these geopolitical and interest rate factors impact domestic liquidity and bond yields.
Global stock markets are currently focused on two primary triggers: the upcoming meeting between Donald Trump and Xi Jinping and the US Federal Reserve's future interest rate decisions. These events are driving uncertainty, as investors assess the potential impact on trade policies and the global cost of borrowing.
Fed Policy Outlook
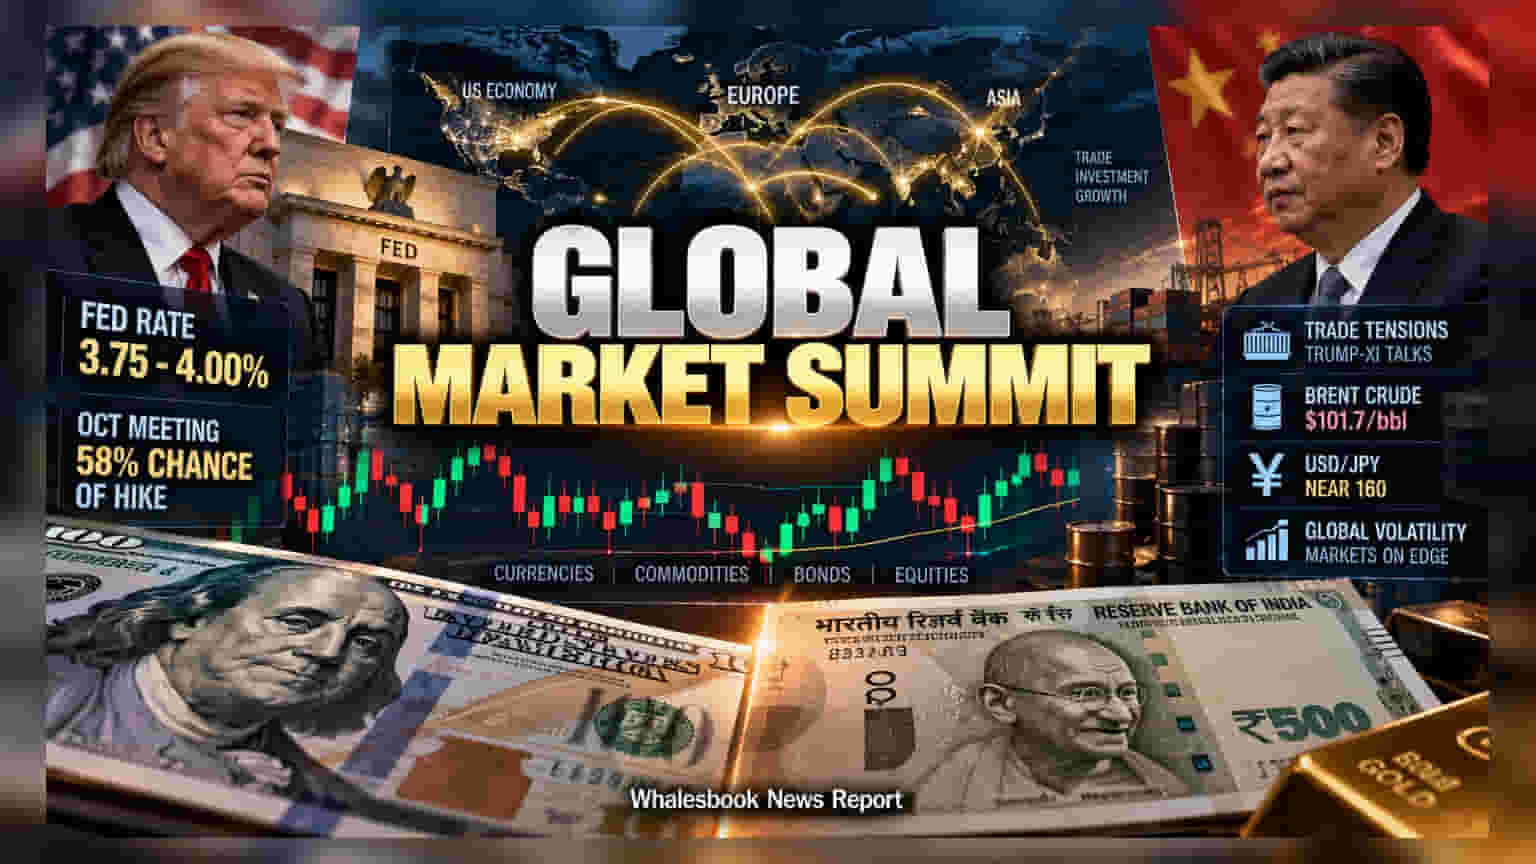
The Federal Reserve recently raised interest rates to a range of 3.75-4.00%. Markets are now pricing in a 58% chance of another rate increase during the October meeting. With 16 of 18 policymakers favoring more hikes, investors are looking for clues in speeches from Fed officials this week. These comments will help estimate how high interest rates might go before stabilizing, a concept often referred to as the terminal rate.
Indian Market Pressures
In India, the financial environment is under pressure due to a strong US Dollar. The Indian Rupee closed at 95.88 against the dollar on Friday, reflecting the challenge of a currency market dominated by dollar strength. Despite efforts by the Reserve Bank of India (RBI) to manage the situation, the combination of high global interest rates and crude oil prices remains a hurdle for local markets. Bond yields are also reflecting this pressure. The benchmark 10-year government bond yield closed at 7.07%, with expectations that it will trade between 7.00% and 7.15% in the near term. Rising bond yields often influence stock valuations, as safer government debt becomes relatively more attractive to some investors. Meanwhile, the RBI continues to use tools like variable rate reverse repo operations and open market sales to manage the amount of cash circulating in the banking system, ensuring stability.
Energy And Currency Volatility
Energy markets are providing mixed signals. Brent crude oil prices have softened slightly to around $101.7 per barrel, largely because Saudi Arabia increased its export volumes. However, oil remains expensive by historical standards, and concerns about shipping lanes due to regional conflicts continue to keep a risk premium on prices. For India, which imports a large portion of its oil, sustained high prices in this range can affect the trade deficit. In currency markets, the Japanese Yen is struggling despite a recent 0.25 percentage point rate hike by the Bank of Japan. The USD/JPY currency pair is trending near the 160 level, creating uncertainty about whether Japanese authorities will intervene to support their currency. Investors should monitor how the geopolitical tension from the Trump-Xi summit unfolds and watch for upcoming comments from US Federal Reserve speakers, as both will be critical in shaping market direction for the rest of the month.