

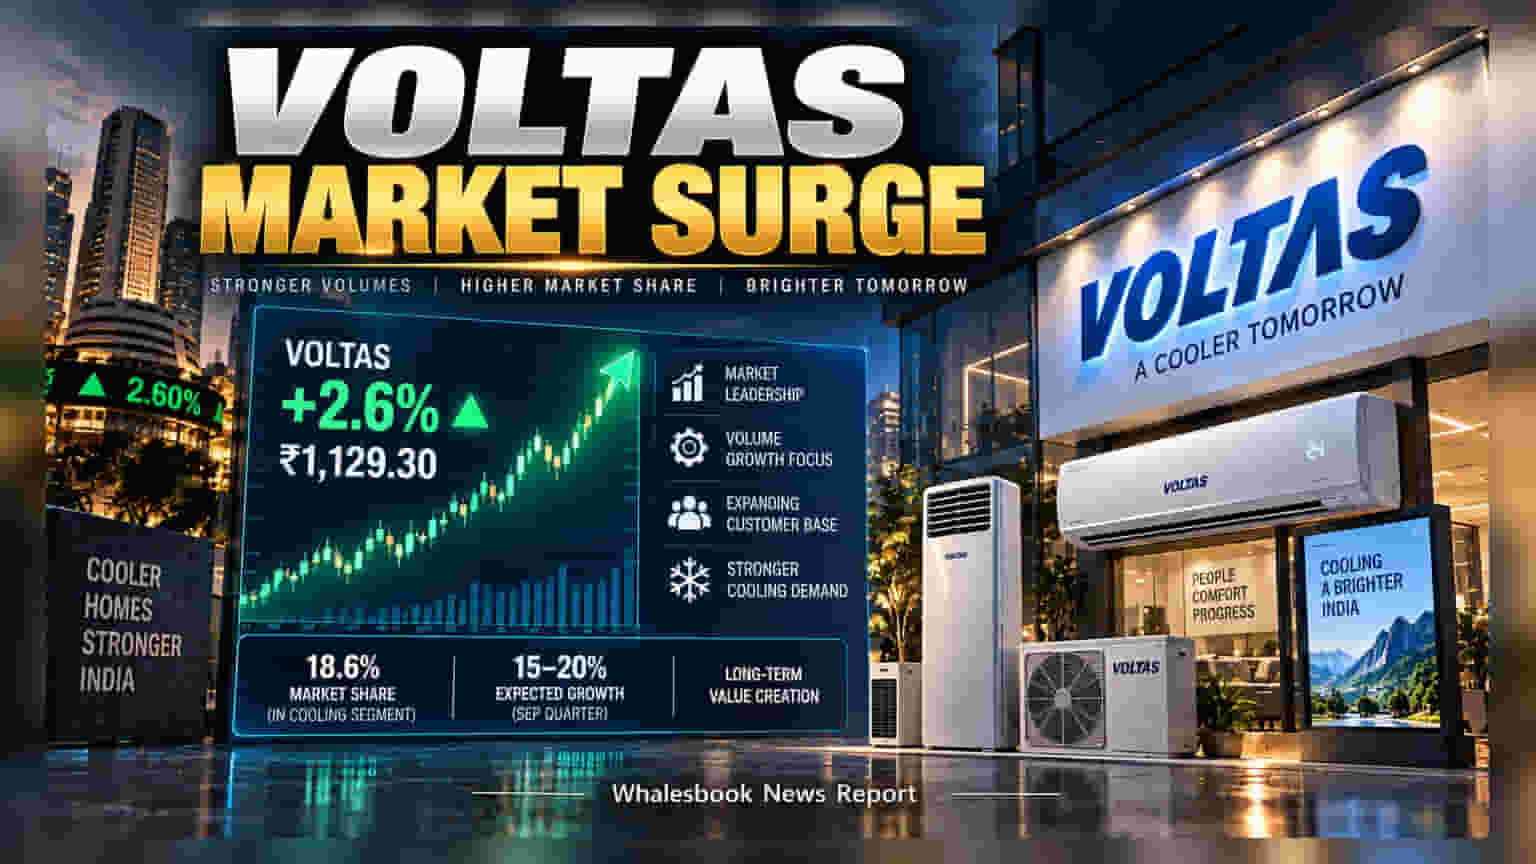
Shares of Voltas closed at Rs 1,129.30 after management confirmed a strategic shift to prioritize market share over immediate profit margins. The company holds an 18.6% market share in the air conditioner segment, but investors are now weighing this growth strategy against persistent raw material cost pressures.
Voltas shares closed 2.6% higher at Rs 1,129.30 on September 23 following an analyst meeting where management outlined a clear shift in business strategy. The company has decided to prioritize volume growth and increasing market share in its unitary cooling products business over immediate profit margin expansion. As of July 2026, Voltas reports an 18.6% market share in the cooling segment, maintaining its lead in a highly competitive market.
Understanding the Strategy Shift
For investors, this shift to prioritizing volume means the company is focused on selling more units and capturing a larger portion of the total market, rather than trying to maximize the profit made on each individual unit right now. The logic behind this approach is to build a larger customer base and achieve better operating leverage as the business grows. However, this strategy comes with inherent risks. The company is currently dealing with a 12% year-to-date increase in raw material costs, driven largely by geopolitical instability affecting global supplies. Prioritizing market share in an environment of rising costs could keep profit margins under pressure in the short term.
Brokerage and Market Views
Financial institutions have responded with mixed perspectives. Jefferies and HSBC have maintained a positive outlook, reiterating their 'Buy' ratings. These brokerages pointed to the company’s strong industry positioning and the likelihood of capturing 15% to 20% growth in secondary sales during the September quarter. Conversely, Motilal Oswal Financial Services remains more cautious with a 'Neutral' rating, reflecting concerns about the timing of margin recovery. While the long-term opportunity in the room air conditioner market is widely accepted, the disagreement between analysts highlights the tension between growth targets and the current inflationary environment.
Investor Monitorables
Moving forward, the primary factor for investors will be the company's ability to navigate cost pressures while executing this volume-led strategy. The management has not set specific, short-term margin milestones, suggesting that profitability improvements will be gradual and tied to the moderation of commodity inflation and a stronger currency position. Investors should watch for upcoming quarterly results to see if the increased sales volumes can effectively offset the rise in input costs, or if margins will continue to stay compressed. Additionally, the impact of raw material price trends and foreign exchange fluctuations remains a critical area to monitor, as these external factors have a direct influence on the company's bottom line.