

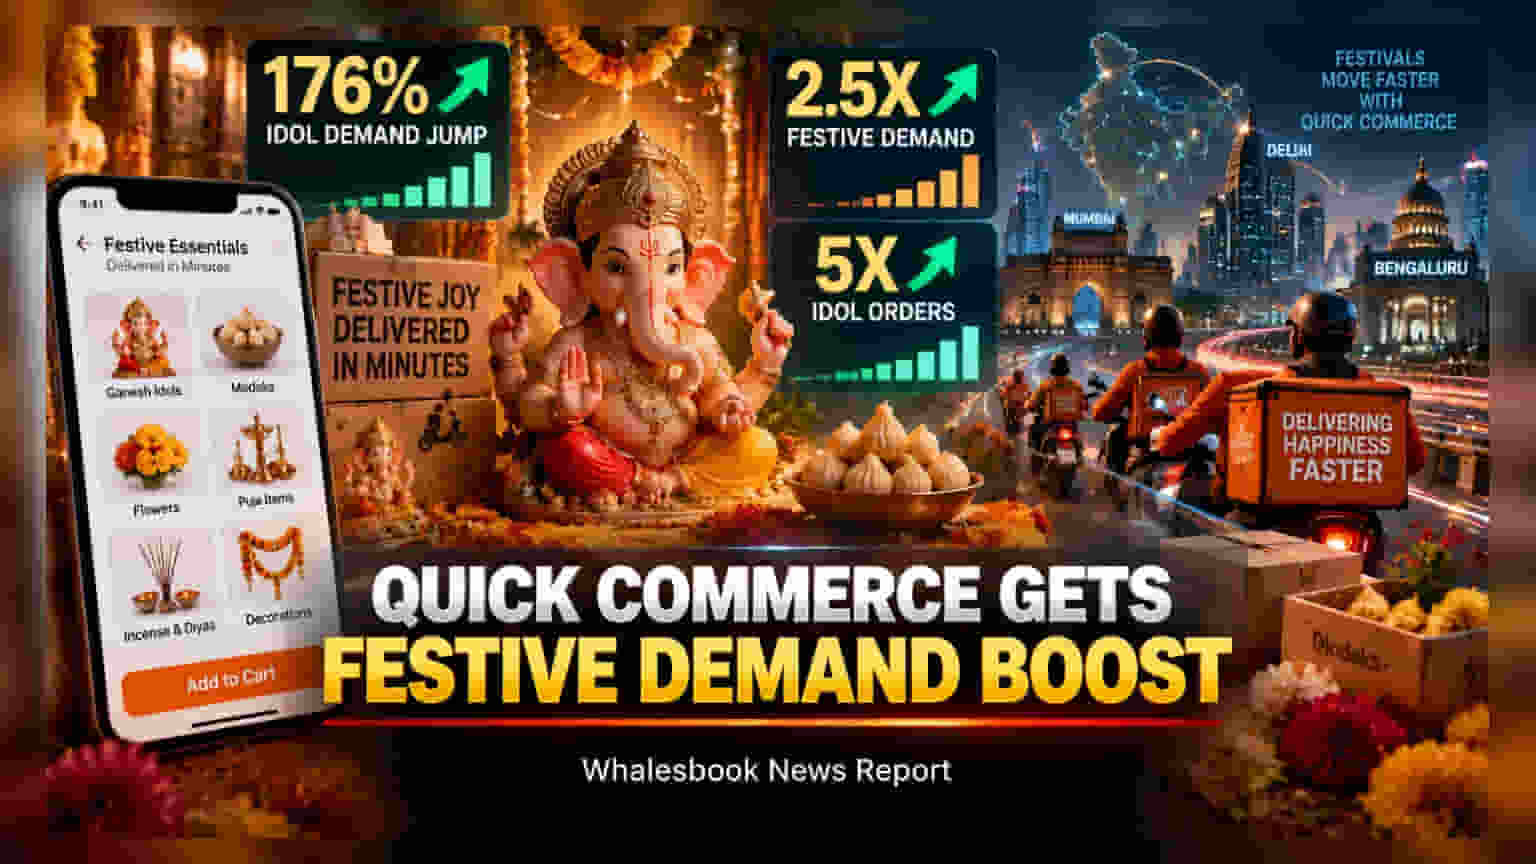
Swiggy Instamart reported a 176% jump in clay-idol demand during Ganesh Chaturthi, signaling quick commerce's move into seasonal retail. While this growth highlights strong consumer adoption, investors are tracking the company’s shift to an inventory-led model and intense competition from rivals like Blinkit and Zepto.
Swiggy’s quick-commerce arm, Instamart, recorded a 176% year-on-year increase in demand for clay idols during the recent Ganesh Chaturthi festival. This surge was accompanied by high interest in other festive essentials like modaks and flowers, indicating that quick-commerce platforms are successfully moving beyond emergency grocery deliveries into the broader, seasonal retail market. On September 16, 2026, Swiggy shares were trading around ₹270.50 as the market weighed this consumer demand against the company's ongoing strategic shifts.
The ability to deliver festive goods in minutes is a significant pivot for the sector. While traditional retail often relies on planned shopping trips, platforms like Instamart and competitors like Flipkart Minutes are capturing last-minute impulse purchases. For Swiggy, this creates an opportunity to increase order frequency and improve the efficiency of its dark store network, which is essential for scaling the business.
However, this growth comes during a critical transition period for the company. Swiggy is currently restructuring Instamart into a wholly-owned subsidiary and shifting toward an inventory-led business model. This change is designed to give the company more control over product availability and quality, which is vital for long-term profit margins. Investors are watching this transition closely, as it typically requires higher upfront capital spending and can lead to short-term margin pressure while the company adjusts its supply chain and operations.
The financial picture reflects these investments. In the first quarter of fiscal year 2027, Swiggy reported consolidated revenue of ₹7,112 crore, marking a 34% growth compared to the previous year. While the company is still reporting losses—with the net loss narrowing to ₹791 crore—the focus remains on scaling revenue and improving unit economics. Achieving profitability will depend on how efficiently the company can manage the inventory-led model in a sector where competition is fierce.
The quick-commerce landscape remains highly aggressive. Rivals such as Blinkit and Zepto are also rapidly expanding their dark store networks and investing heavily to capture market share. This high level of competition often results in continued cash burn, as companies spend on marketing, expansion, and rapid delivery infrastructure. Additionally, Swiggy faces regulatory and structural challenges. In August 2026, shareholders approved a 49.5% cap on aggregate foreign ownership to meet requirements for maintaining Indian-owned and controlled status, a development that has influenced investor sentiment and liquidity.
For shareholders and observers, the next important update will be how the inventory-led model affects the company’s profit margins in the coming quarters. While festive surges demonstrate strong demand, the long-term success of the business will rely on sustaining this growth throughout the year and managing the costs of the intense battle for market share against well-funded competitors.