

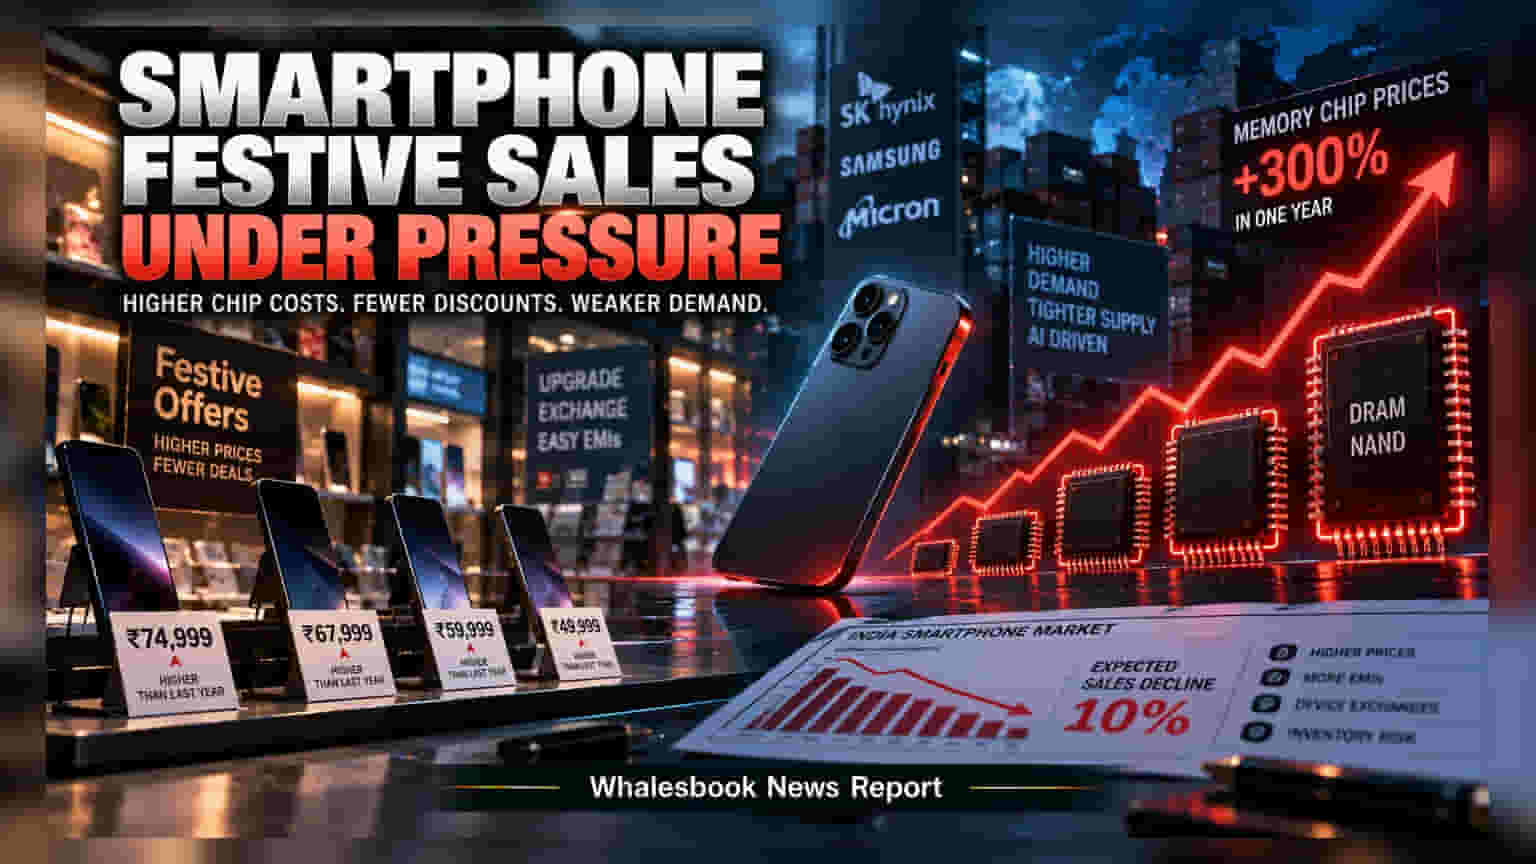
India’s smartphone industry expects a 10% volume decline this festive season as a 300% surge in memory chip costs forces brands to hike prices. Companies are shifting from traditional discounts to financing schemes to sustain demand.
The Indian smartphone market, traditionally a high-growth sector during the festive period, is facing a major headwind this year. Rising costs for memory components are forcing manufacturers to adjust their retail pricing, leading to a projected 10% decline in sales volume. This shift marks a notable departure from previous years when consumers could rely on deep festive discounts to drive purchases.
The primary driver of this cost pressure is a steep increase in memory chip prices, which have climbed nearly 300% over the last year. Major global chip suppliers, including SK Hynix, Samsung Electronics, and Micron Technology, have been prioritizing the production of high-value components used in AI infrastructure. This strategic shift has constrained the supply of memory wafers for consumer electronics, creating a supply-side bottleneck that experts anticipate could persist until at least 2027 or 2028.
Impact on Consumer Pricing and Brands
These component costs are now flowing through to the retail level. Leading smartphone brands, including Samsung, OnePlus, Realme, Oppo, and Vivo, have already adjusted price tags across their product lines to protect their profit margins. Apple has also implemented significant price increases for several models, including the iPhone 17 and the newly launched iPhone 18 Pro series. Manufacturers are increasingly pulling lower-cost, entry-level models from the market as the rising cost of parts makes them less profitable to sell.
Shifting Sales Tactics
With the cost of building phones rising, companies can no longer afford the aggressive direct discounts that previously defined the festive shopping season. Instead, brands are pivoting toward financial engineering to keep buyers active. Analysts expect that approximately 42% of smartphone transactions this year will be facilitated through credit-card EMIs, debit-card installments, and loans from non-banking financial companies (NBFCs).
Offline retail channels are becoming increasingly important in this strategy, as they often provide better underwriting and access to these credit products. Device exchange programs are also being promoted as a key tool to lower the initial cost for consumers, helping brands keep aspirational buyers engaged even as device prices rise.
Investor Monitorables
The move away from direct discounts to financing-led sales reflects a difficult balancing act for smartphone makers. While financing can help support demand, it does not solve the underlying issue of higher manufacturing costs. For investors, the key monitorable for the coming quarters will be how well these brands can manage their inventory levels and profit margins if consumer demand does not pick up as expected. Persistent high costs and lower sales volumes could force further inventory corrections for manufacturers, potentially impacting their short-term financial performance.