

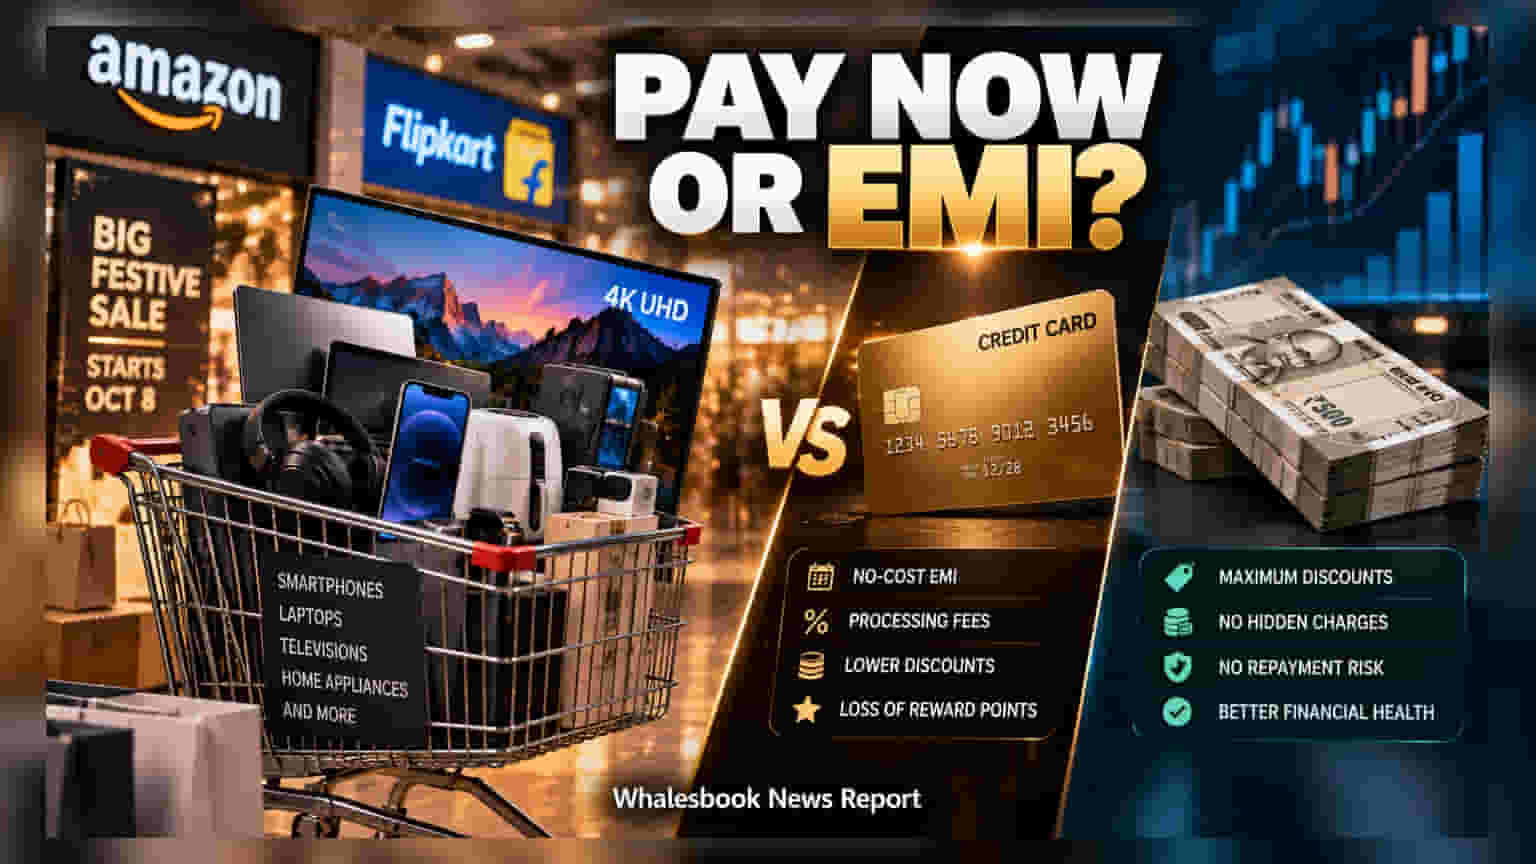
Amazon and Flipkart launch major festive sales on October 8. While retailers promote 'no-cost' EMI, shoppers should prioritize total cost over monthly payments to avoid hidden processing fees and lost discounts. Financial discipline requires checking the total out-of-pocket expense before committing to credit-linked financing.
As Amazon and Flipkart prepare to launch their major festive sales on October 8, many Indian consumers are planning to purchase electronics, appliances, and home goods. While e-commerce platforms aggressively market 'no-cost' EMI schemes to make expensive items appear affordable, financial experts suggest that buyers must look past the monthly installment amount to understand the true cost of their purchases.
The reality of 'no-cost' EMI is often more complex than the marketing suggests. These schemes frequently come with trade-offs, such as a lower discount for EMI buyers compared to customers who pay the full amount upfront. Furthermore, consumers often pay additional processing fees and GST on those fees. When these hidden costs are combined with the potential loss of credit card reward points, the actual cost of an EMI purchase can be significantly higher than the price tag suggests.
For those with adequate liquid savings, paying in full is generally the most cost-effective decision. According to industry experts, upfront payment often unlocks the maximum available discount and eliminates the future risk of repayment default. It also removes concerns regarding hidden charges or the impact of multiple small, recurring monthly payments on one's monthly cash flow.
A significant risk during the festive season is the accumulation of multiple small EMIs across different product categories. While a single monthly payment might seem manageable, the aggregate of several installments can quickly strain household budgets and eat into emergency savings. Financial experts at firms like BankBazaar suggest that total monthly loan obligations should ideally stay within 30 to 35 percent of an individual's take-home income to maintain financial health.
Before finalizing a purchase during the upcoming sales, consumers are encouraged to calculate the total transaction cost under both payment methods. This involves checking for processing fees, foreclosure charges, and the difference in discount amounts between paying via EMI and paying via debit, net banking, or UPI. Understanding the total cash outflow before checkout can prevent buyers from overextending their finances and ensure that festive shopping remains a celebration rather than a debt burden.