

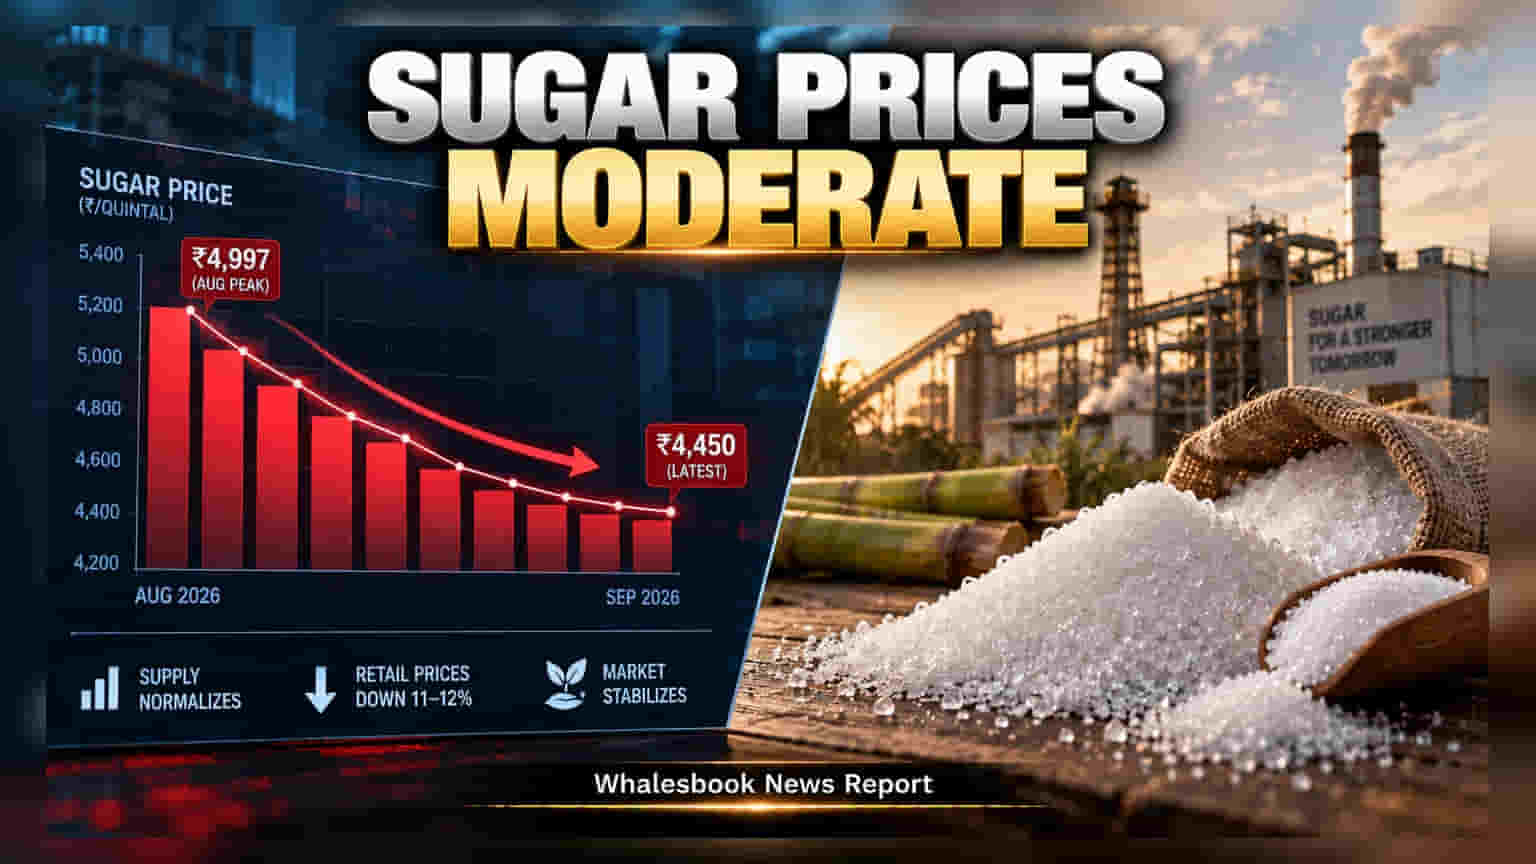
Sugar industry bodies reject claims of windfall profits, noting that recent price spikes were temporary and affected only 2.5% of annual supply. With retail prices down 11% and ex-mill rates normalizing, producers highlight that high sugarcane procurement costs continue to limit margins.
The domestic sugar industry has issued a formal response to recent claims that sugar mills generated excessive profits during a short period of market volatility in late August 2026. Industry bodies, including the Indian Sugar & Bio-energy Manufacturers Association and the National Federation of Cooperative Sugar Factories, have clarified that the price spike was localized and fleeting. As of late September, national average ex-mill prices have settled near ₹4,450 per quintal, reflecting a significant correction from the peak levels seen last month.
Understanding the Market Correction
The recent price volatility resulted in retail sugar prices rising briefly, but this trend has reversed as market supply normalized. Consumers are now experiencing a decline of 11% to 12% in retail sugar prices, which are currently hovering around ₹57.5 per kg. The correction reflects a nearly 30% reduction from the recent highs observed during the volatility. For the broader market, this return to stability suggests that the temporary supply-demand mismatch has been resolved without sustained inflation.
Addressing Profitability Concerns
Industry representatives emphasize that the August price surge did not lead to widespread windfall gains. Data covering the period between August 17 and August 31, 2026, shows that only 7.22 lakh tonnes of sugar were sold at the elevated average of ₹4,996.98 per quintal. When measured against India’s total annual domestic consumption of 285 lakh tonnes, this specific volume represents roughly 2.5% of the annual market. Over 97.5% of the total annual supply was moved at significantly lower price points, shielding the average consumer from the temporary spike.
Balancing Operational Costs
For industry stakeholders, the structural financial pressure remains more significant than the recent price window suggests. Since the start of the 2025–26 sugar season in October, the weighted pan-India average ex-mill realization has been approximately ₹4,100 per quintal. Producers state that this price level barely covers the rising statutory costs of sugarcane procurement and conversion expenses. The sector has maintained its financial commitments to the farming community, with mills having already disbursed ₹1.12 lakh crore for sugarcane procurement, covering about 97% of the total payments due this season. Future market performance will depend on the balance between stable domestic prices, the upcoming festive demand, and the ability of mills to manage high raw material costs.