

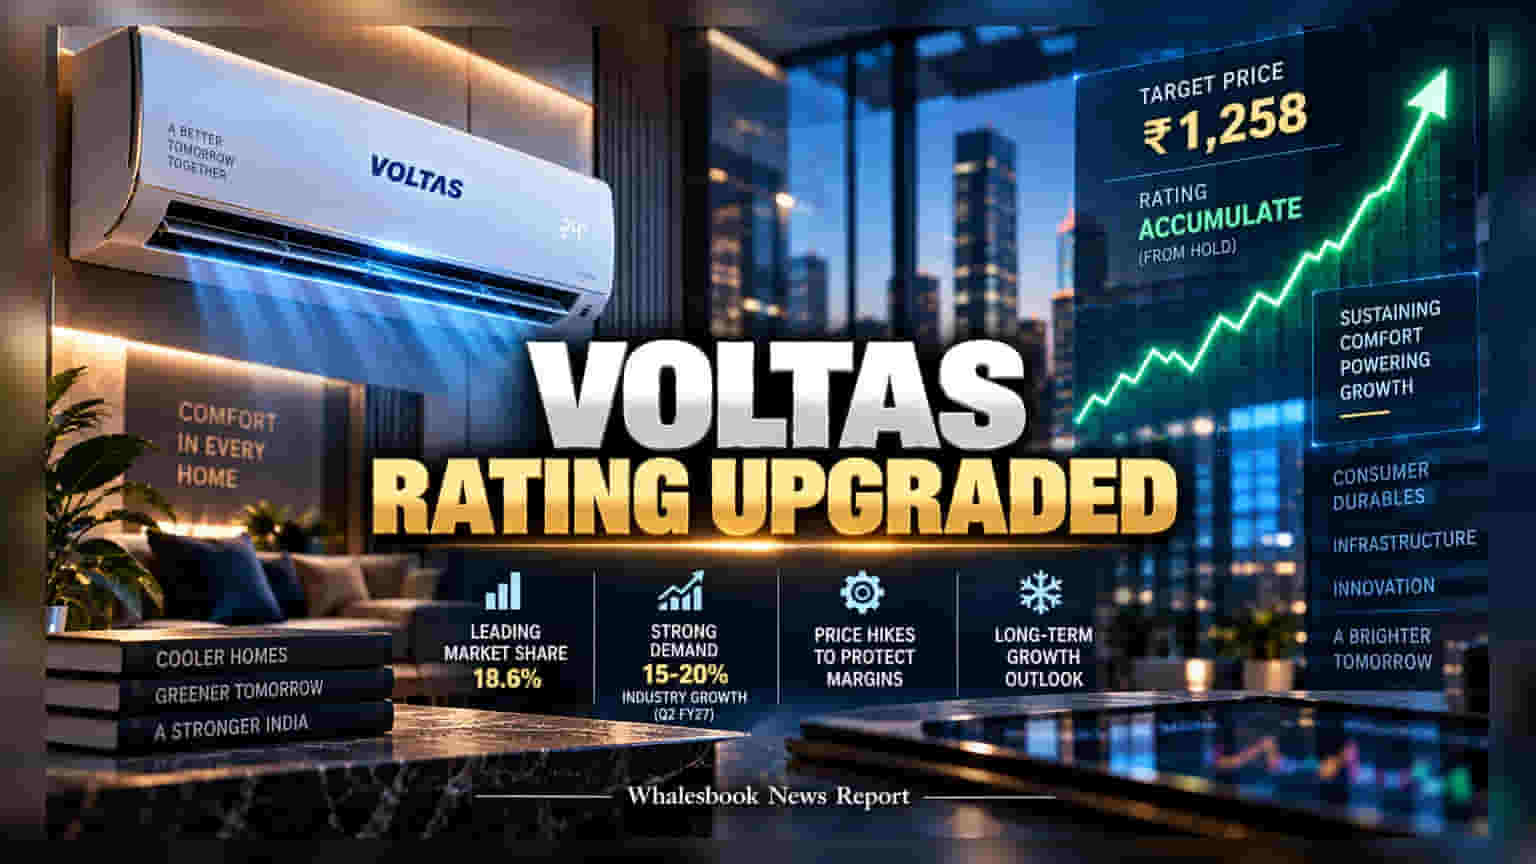
Brokerage firm Prabhudas Lilladher has upgraded Voltas to 'Accumulate' with a target of Rs 1,258, citing its strong 18.6% market share. While the company projects double-digit growth through fiscal 2029, investors should monitor how it manages margin pressure from commodity costs and new energy efficiency regulations.
Brokerage firm Prabhudas Lilladher has raised its rating for Voltas to 'Accumulate' from 'Hold,' setting a target price of Rs 1,258. This shift in stance follows the company’s recent performance in the Indian room air conditioner market, where it held an 18.6% market share as of July 2026. This figure places the company roughly 6.4 percentage points ahead of its closest competitor, maintaining a significant lead in the sector.
Operational Growth and Capacity Constraints
The company’s outlook remains supported by strong demand, with management projecting the room air conditioner industry to grow between 15% and 20% year-over-year in the second quarter of fiscal 2027. However, the company is navigating operational challenges. Its manufacturing plants are currently operating at near-full capacity. When production lines run at maximum volume without immediate expansion, it becomes harder to improve profit margins through higher efficiency. To offset rising costs and protect profitability, Voltas has implemented two separate price hikes of 7% and 5%.
Cost Management and Regulatory Impact
Profit margins have been under pressure due to a combination of rising commodity prices—such as steel and copper—and currency fluctuations. Additionally, the company is adjusting its manufacturing process to comply with the latest energy efficiency regulations from the Bureau of Energy Efficiency. These mandatory changes often require higher upfront technology and material costs, which can temporarily reduce margins before the company can pass them on to consumers through pricing adjustments or offset them with internal cost-saving measures.
Inventory management appears to be a disciplined point in the company's current operations. Channel inventory levels are reportedly held below 30 days, which suggests the company is efficiently moving products through its distribution network without building up excess unsold stock.
Future Growth Outlook
Prabhudas Lilladher’s updated financial estimates for the period through fiscal 2029 suggest a steady long-term trajectory. The brokerage forecasts a Compound Annual Growth Rate of 13.2% for revenue, 31.7% for EBITDA, and 39.7% for profit after tax between fiscal 2026 and 2029.
For investors, the most important monitorable remains the company's ability to protect its profit margins while maintaining its market lead. The effectiveness of the recent price hikes, combined with ongoing cost optimization efforts, will be critical in meeting these long-term growth targets. Investors may also track management commentary on capital spending to see if the company plans to expand manufacturing capacity to overcome current production constraints.