

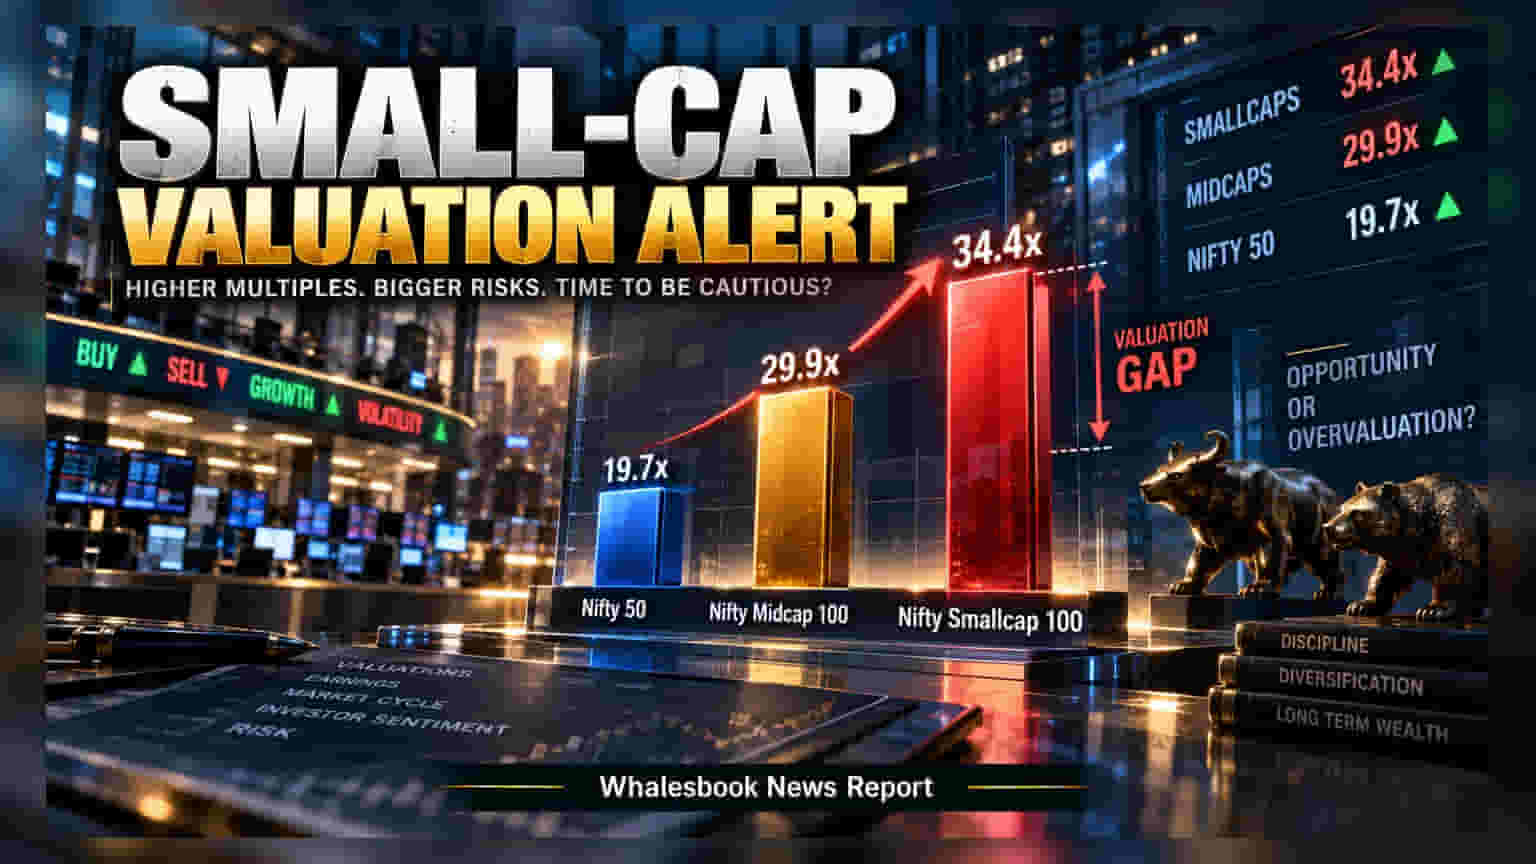
Smaller companies are currently trading at significantly higher price-to-earnings ratios than Nifty 50 giants, a historic shift in Indian market valuations. This premium indicates high investor optimism for future growth, though market history suggests such gaps often narrow over time. Investors are now monitoring whether smaller company earnings can justify these elevated prices or if large-caps will regain their traditional valuation lead.
The Indian stock market is currently experiencing a notable shift in how companies are valued. Historically, large-cap companies, such as those in the Nifty 50 index, have commanded a valuation premium because of their stable earnings and established business models. However, recent market data shows that smaller companies, represented by the Nifty Midcap 100 and Nifty Smallcap 100 indices, are now trading at significantly higher multiples than their larger counterparts.
Currently, the Nifty 50 index trades at a trailing price-to-earnings (P/E) ratio of approximately 19.7. In contrast, the Nifty Midcap 100 index sits at a P/E of 29.9, while the Nifty Smallcap 100 index has surged to 34.4. The P/E ratio is a primary tool used to determine how much investors are paying for every rupee of profit a company earns. When this ratio is higher, it means the market is pricing in expectations of very fast future growth. The current numbers suggest that investors are currently willing to pay much more for the same amount of profit in smaller, potentially faster-growing companies than they are for the profits of the largest, most stable giants.
This inversion in market hierarchy is largely driven by a high level of optimism among retail investors, who are aggressively betting on newer, digital, and growth-oriented businesses. While this excitement has pushed stock prices higher, it has also decoupled these valuations from current, realized earnings. The market is essentially paying for a future that is yet to happen, rather than the performance seen on the balance sheet today.
Financial history suggests that such anomalies rarely persist indefinitely. Market cycles often undergo a process called mean reversion, where asset prices eventually move back toward their long-term historical averages. If the high growth rates expected by the market do not materialize, there is a risk that smaller company valuations may cool down. Conversely, large-cap stalwarts, particularly in sectors like banking and capital goods, could eventually see their valuations rise if the market rotates back toward established value.
Another significant variable for investors to watch is the role of Foreign Institutional Investors (FIIs). These large global players have been inconsistent in their buying and selling activity over the past year. FIIs typically favor the stability and high liquidity of the Nifty 50 index. If global bond yields stabilize or if crude oil prices remain in check, renewed interest from these large institutional players could shift the focus back toward the broader, more established market indices. For now, the key monitorable for investors is whether the actual earnings of smaller companies can catch up to the high valuations currently set by the market.