

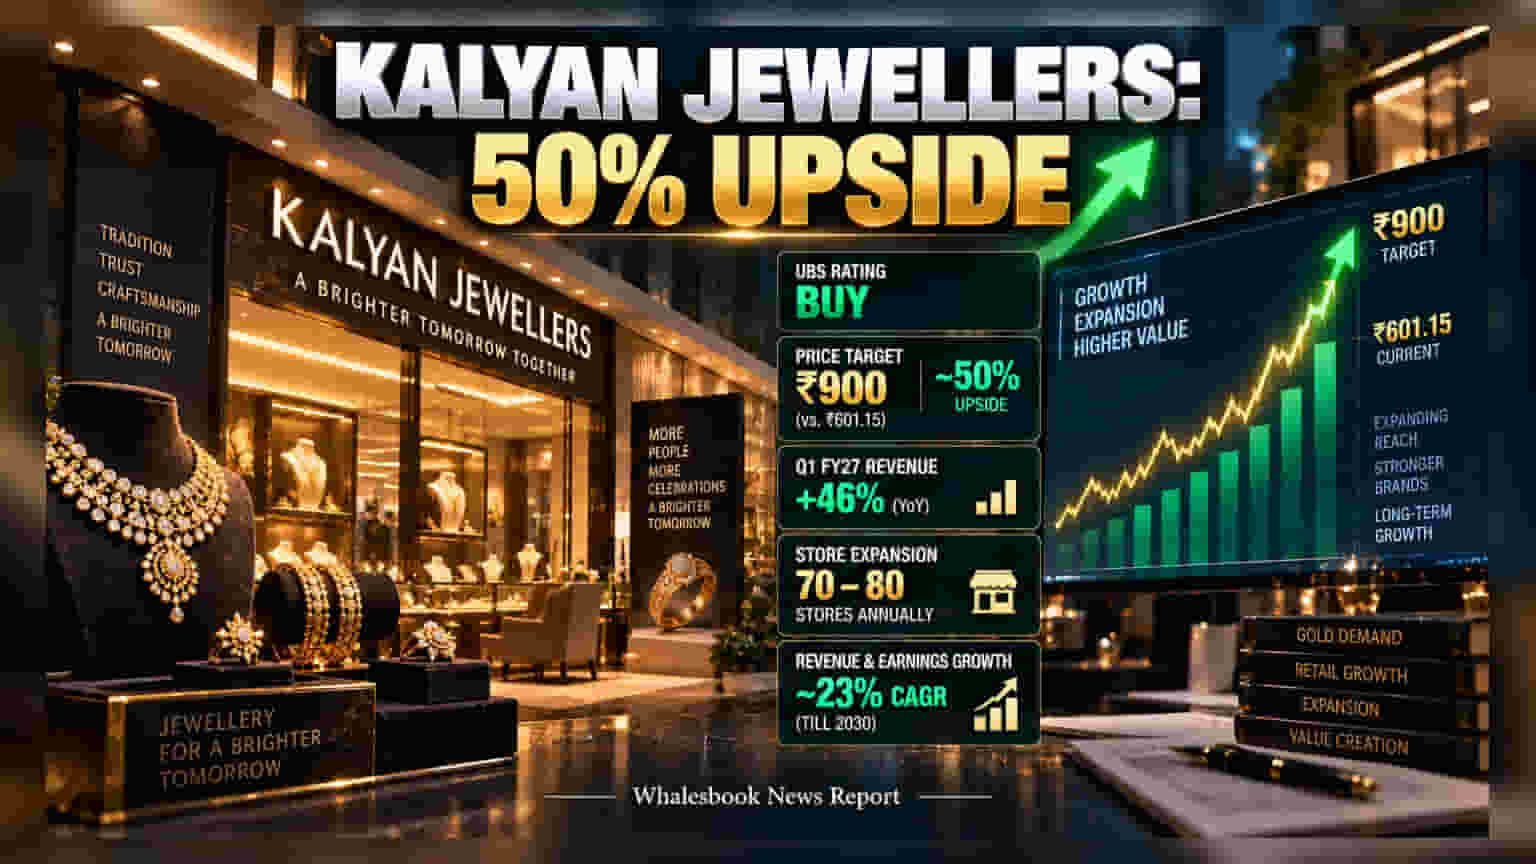
UBS has started coverage on Kalyan Jewellers with a 'Buy' rating and a price target of Rs 900. The brokerage highlights the company's aggressive, capital-light franchise model as a key growth driver. Investors are now watching whether the company can sustain this expansion pace while managing its debt reduction strategy.
Kalyan Jewellers India has received a positive outlook from UBS, which recently initiated coverage on the stock with a 'Buy' rating and a price target of Rs 900. This target implies a potential upside of approximately 50% from the stock's recent trading level of Rs 601.15. The market reacted to the news with investor interest in the retailer's aggressive expansion strategy.
At the heart of the brokerage's bullish view is the company's use of the Franchise-Owned, Company-Operated (FOCO) model. This strategy allows the company to expand its store network rapidly without the heavy financial burden of owning every location. By partnering with franchisees for capital, Kalyan Jewellers can focus on operations and brand reach. This model currently supports the addition of 70 to 80 stores annually, a pace that puts it ahead of several major competitors in the organized jewellery retail space.
Financial performance has been a core pillar of this positive outlook. The company recently reported strong results for the first quarter of fiscal year 2027, with a 46% year-on-year increase in consolidated revenue. Looking ahead, UBS analysts project that the company’s revenue and earnings could grow at a compound annual rate of about 23% through 2030. When compared to the industry leader Titan, Kalyan Jewellers is currently trading at roughly 30 times its estimated fiscal year 2028 earnings. The brokerage noted that this valuation represents a 45% discount compared to Titan, suggesting that the market has not yet fully priced in the potential of its current growth trajectory.
While the expansion plans and growth projections are the focus, investors should also consider the inherent risks in the jewellery retail sector. Business performance can be sensitive to gold price volatility, which affects consumer demand. Any shifts in government policy, such as changes in gold import duties or tighter capital regulations, can also impact the company's costs and supply chain. Additionally, running a large franchise-led network requires maintaining high operational standards across all locations. If the company faces challenges in managing these franchises or if promotional activities to drive sales put pressure on profit margins, the financial results could be affected.
Beyond expansion, the company’s balance sheet management is another area for investors to monitor. Kalyan Jewellers has outlined plans to liquidate non-core real estate assets and achieve full repayment of its standalone non-GML debt by September 2026. Successfully executing these financial goals, along with maintaining the pace of store openings, will be key factors in how the business sustains its current momentum.