

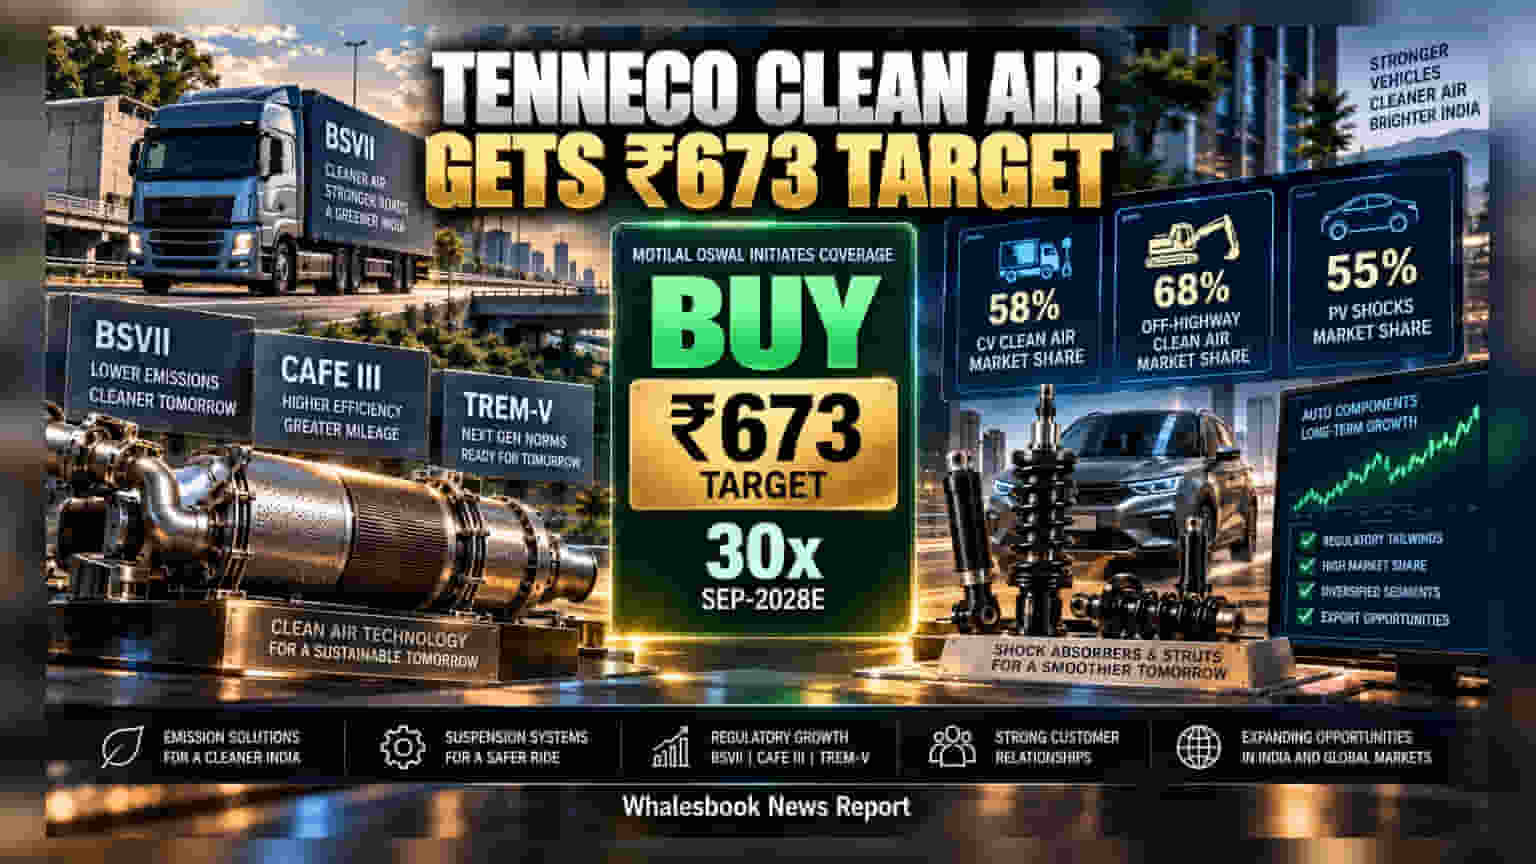
Motilal Oswal has initiated coverage on Tenneco Clean Air India with a 'Buy' rating and a ₹673 target price. The brokerage highlights the company's dominant market share in emission control and suspension systems. Investors are tracking how regulatory upgrades and export growth may shape future performance, alongside risks related to high customer concentration.
Motilal Oswal has initiated coverage on Tenneco Clean Air India with a 'Buy' rating and a target price of ₹673. The stock has recently traded in the ₹506–₹519 range, drawing attention from investors tracking the automotive components sector.
The brokerage's analysis is built on the company's strong market position. Tenneco Clean Air commands an estimated 58% share of the commercial vehicle clean-air market and roughly 68% of the off-highway clean-air systems business, excluding tractors. In the passenger vehicle segment, it holds an estimated 55% share in shock absorbers and struts. These figures indicate a business advantage that allows the company to operate across multiple vehicle categories rather than relying on a single segment.
Looking ahead, the investment thesis relies on tighter regulatory standards, such as Bharat Stage VII and Corporate Average Fuel Efficiency III norms. These mandates require more sophisticated emission and suspension technology. As vehicles adopt these advanced components, the value of parts supplied per vehicle is expected to increase, which could support revenue growth even if overall industry sales volume does not rise significantly.
However, the company faces distinct operational risks that investors should monitor. A significant portion of revenue, over 80%, is concentrated among the top ten customers. This makes the company highly dependent on the success and production schedules of these specific manufacturers. Furthermore, the company’s ability to remain competitive relies on its access to technology and research from its US-based parent group. Any disruption in this licensing or technical support arrangement could pose a risk to operations.
The ₹673 target price is based on a valuation of 30 times estimated earnings for September 2028. This valuation assumes the company will successfully execute on its export goals, localization of advanced products, and new customer programs. Because the automotive sector is cyclical, future stock performance will depend heavily on the company's ability to maintain these margins and navigate the industry's long-term transition toward electric vehicles, where demand for traditional clean-air and suspension products may shift.