

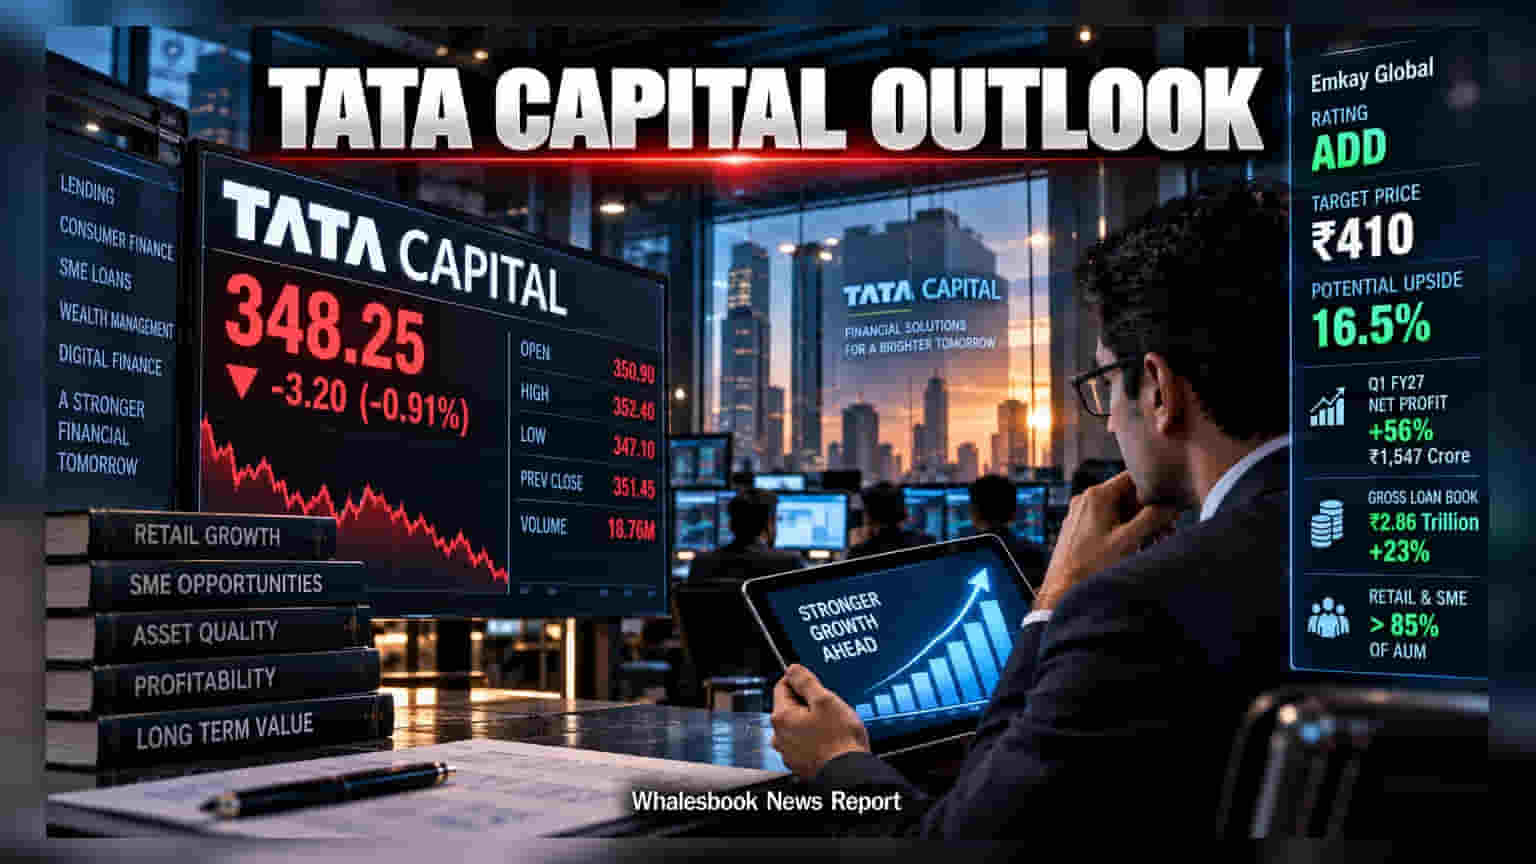
Tata Capital shares fell nearly 1% in recent trading even as Emkay Global maintained an 'Add' rating with a ₹410 price target. The company reported a 56% jump in Q1 net profit, with gross loans growing 23%. Investors are now focusing on the company’s retail and SME-led growth strategy and the expected margin recovery in the second half of the year.
Shares of Tata Capital experienced some selling pressure in early trade, dipping nearly 1% to ₹348.25. This move comes despite a positive assessment from brokerage firm Emkay Global, which has reiterated its 'Add' rating on the company. The brokerage has set a price target of ₹410, suggesting a potential upside of approximately 16.5% from current levels. The market reaction appears to be lagging behind the brokerage's optimistic outlook, which is rooted in the firm's recent financial performance and future growth projections.
Financial Growth and Profitability
The company’s latest quarterly performance for the first quarter of fiscal year 2027 has been strong, with net profit rising by 56% to ₹1,547 crore. This growth has been supported by a 23% expansion in the gross loan book, which now stands at ₹2.86 trillion. Management and analysts remain confident in the company's trajectory, with a firm outlook for AUM growth between 23% and 25% for the period spanning fiscal years 2025 to 2028. Analysts have pointed out that the company's core metrics, such as credit costs and profitability, are currently tracking well against internal management guidance.
Operational Strategy and Regulatory Outlook
A key focus for the company is its shift toward retail and SME portfolios, which now make up over 85% of its total assets under management. This concentration is part of a broader strategy to maintain high-quality asset growth. Looking ahead, the company expects a boost in momentum as the integration of the Tata Motors Finance book recovers, with positive impacts anticipated from the third quarter onwards. While profit margins remained flat in the second quarter, the brokerage expects an improvement in the second half of the fiscal year as the firm expands its high-yielding product offerings.
Investors have also been watching for any potential risks from regulatory changes, particularly following the Reserve Bank of India’s recent draft amendment directions regarding revolving credit lines. However, analysts at Emkay have downplayed these concerns, suggesting that the risk of a major crackdown on such credit lines is low. They argue that the unique capabilities of non-banking financial companies in originating these loans, combined with their current regulatory standing, make significant restrictions unlikely.
For investors, the most important aspects to watch moving forward will be the execution of the Tata Motors Finance book integration and the firm's ability to improve profit margins in the coming quarters. While the company's long-term AUM growth targets remain a positive signal, the ability to maintain strong asset quality while managing sector-wide regulatory changes will remain a primary monitorable for the business.