

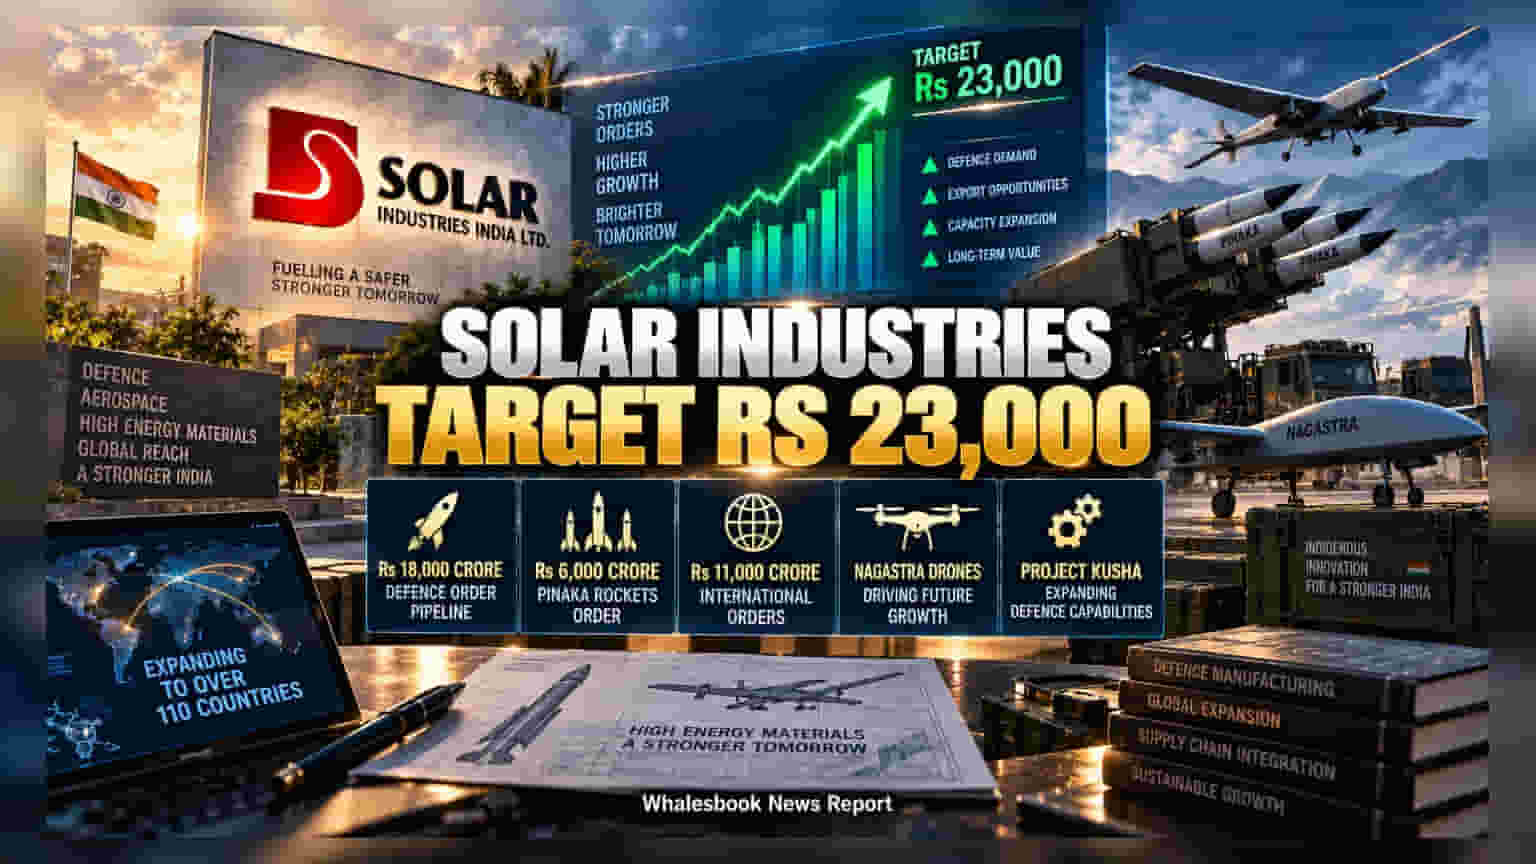
Motilal Oswal has initiated coverage on Solar Industries, highlighting its transition into a defense manufacturer. The brokerage expects significant defense revenue growth by FY30, driven by drone and rocket orders. However, investors should be aware of risks regarding project execution, international expansion, and margin volatility.
Solar Industries India Ltd is seeing a shift in its business outlook as it pivots from traditional industrial explosives to becoming a strategic defense manufacturer. Brokerage firm Motilal Oswal Financial Services has initiated coverage on the company, identifying this transition into high-energy materials—such as rockets, drones, and loitering munitions—as a key factor for its long-term valuation. This strategy marks a significant departure from its historical focus on explosives used in mining and infrastructure.
The brokerage highlights a strong order book as a primary growth driver for this transition. Solar Industries currently reports a defense order pipeline of approximately Rs 18,000 crore. This includes a major contract for Pinaka rockets valued at Rs 6,000 crore, alongside Rs 11,000 crore in international orders. Analysts project that the company’s defense revenue could scale to Rs 9,900 crore by FY30, supported by the delivery of Nagastra drones and the implementation of Project Kusha.
To support this capacity expansion, the company is also pursuing inorganic growth. The proposed acquisition of South Africa-based Omnia Holdings is intended to provide backward integration for ammonium nitrate, a critical raw material. If successful, this move could help the company secure its supply chain and expand its operational footprint to over 110 countries. The brokerage anticipates this could position the firm for strong revenue growth over the next four years.
However, investors should also consider the inherent risks in this defense-led growth strategy. The company’s performance is heavily dependent on the successful execution of large platform orders, where delays in government project timelines could directly impact revenue. Entering African markets also introduces specific challenges, including currency fluctuations and geopolitical risks in those regions. Additionally, as the company scales its defense business, maintaining profit margins will depend on its ability to manage raw material price volatility.
For investors, the key monitorables will be the actual execution of the current order book and the timeline for commissioning major projects like Project Kusha. Tracking the successful integration of international acquisitions and the stability of profit margins in the face of input cost changes will be crucial to assessing the company’s long-term defense transition.