

Shaily Engineering Plastics is scaling its medical device manufacturing capacity to support growing demand for GLP-1 drugs. While the healthcare shift and new semiconductor business offer growth potential, the stock trades at a high valuation of 48 times estimated FY28 earnings, increasing pressure on execution and delivery.
Shaily Engineering Plastics is shifting its business focus toward specialized medical device manufacturing, with the healthcare segment now contributing approximately 51% of its total revenue. The company is actively scaling its capacity to meet the rising demand for drug-delivery devices, particularly those used in GLP-1 treatments for diabetes and weight management.
Scaling Production and Capacity
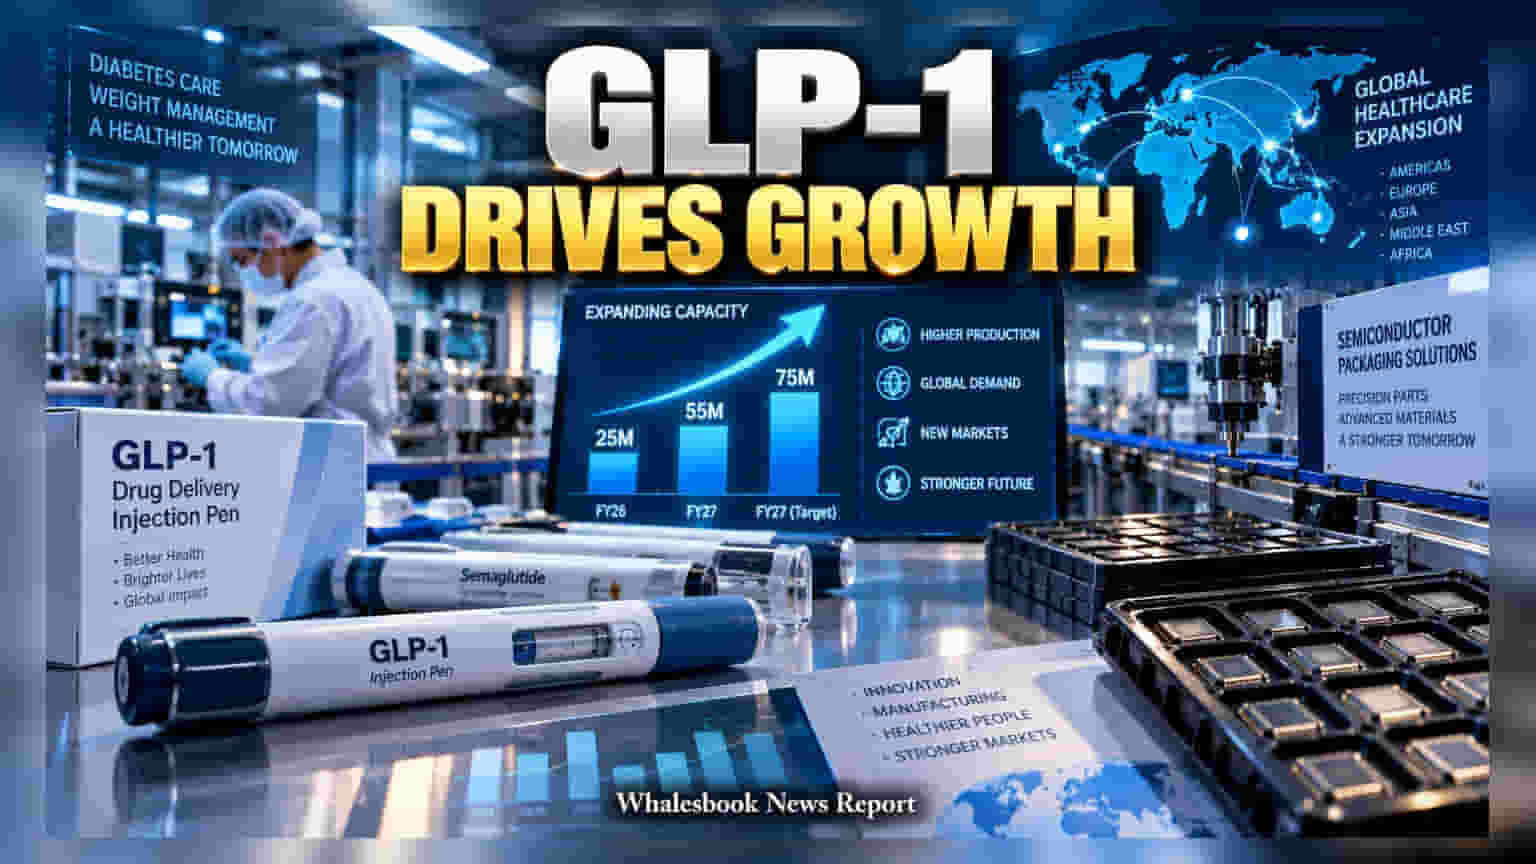
The company has significantly increased its annual production capacity for pen devices, rising from about 25 million units in FY26 to 55 million units. Management plans to further expand this capacity to nearly 75 million units by FY27. This growth is backed by confirmed customer commitments, which cover roughly 60% to 65% of the upcoming production capability. Operational improvements have also been significant, with the company reducing device rejection rates from nearly 30% to about 8%.
Expansion Beyond Existing Products
The company is looking to broaden its reach within the healthcare sector. This includes recent customer approvals for semaglutide pen programmes in Canada and Brazil. Additionally, Shaily is developing reusable auto-injectors expected to reach the market by late FY27. Beyond healthcare, the company is entering the semiconductor packaging business, with plans to produce conductive plastic trays for chip manufacturing starting in the fourth quarter of FY27. This move represents a new, long-term revenue stream for the company.
Segment Performance and Valuation Risks
While the medical and industrial segments show growth, the company's traditional consumer business continues to struggle. Revenue in the consumer segment fell by 24% year-on-year, primarily due to weak demand across the United States and Europe.
Investors are currently pricing in significant future growth, with the stock trading at approximately 48 times its estimated FY28 earnings. This higher valuation leaves little margin for error. Future performance will largely depend on the company's ability to maintain manufacturing efficiency, secure timely commercial launches for its new products, and navigate potential margin pressure. The key monitorable for investors will be whether the company can sustain its growth targets while managing the execution risks associated with its large-scale capacity expansion and entry into new business segments.