

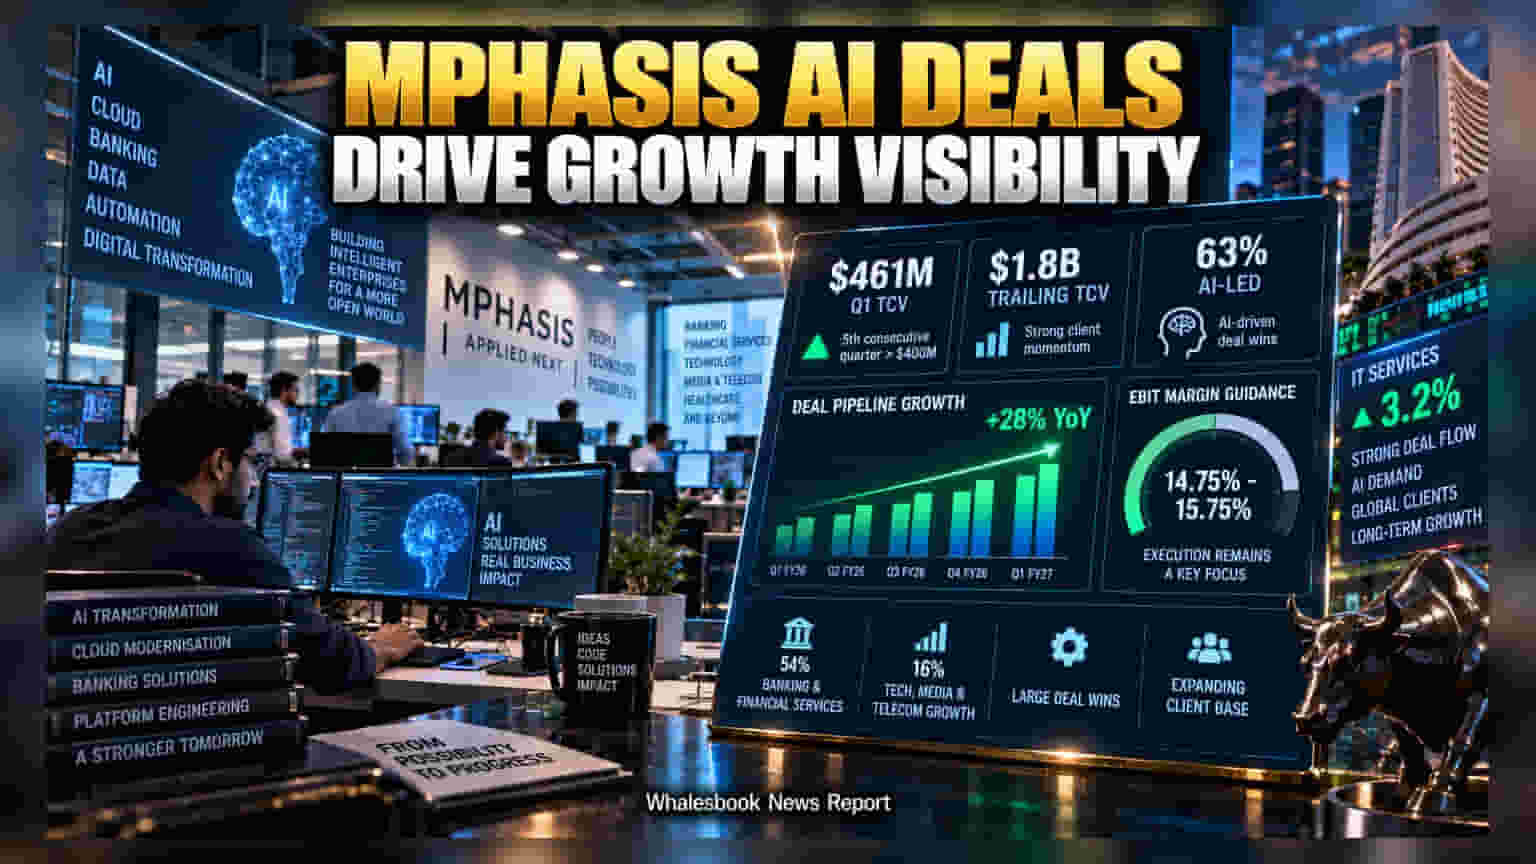
Mphasis secured $461 million in new contracts during Q1 FY27, marking its fifth consecutive quarter of strong bookings. With 63% of these deals tied to AI, the company is betting on tech modernization. Investors are now watching whether these deals convert into steady revenue growth and how the company manages margin pressure from new project costs.
Mphasis reported a strong start to FY27, with net-new total contract value reaching $461 million in the first quarter. This result continues a trend where the company has secured more than $400 million in bookings for five straight quarters. With total bookings over the last 12 months crossing $1.8 billion, the firm has clearly attracted interest from its clients.
A key driver for this business is artificial intelligence. In the first quarter, 63% of new bookings were linked to AI-related projects. The company’s pipeline, which represents potential future business, grew 28% compared to last year. This suggests that clients are actively looking for help with automation and data modernization, even as they remain cautious about their overall technology spending.
While deal wins are high, the main challenge for Mphasis now is converting these contracts into actual revenue. In the technology services sector, signing a contract is only the first step. The company must then staff projects, deploy technology, and ensure the work is completed on time. Investors will be looking to see if this strong booking pace can actually lift the company’s growth rate in the coming quarters.
The company’s business remains heavily tied to the banking and financial services sector, which accounts for about 54% of its revenue. While this area grew by about 8% compared to last year, the company is trying to reduce its reliance on it by growing other parts of its business. For instance, its technology, media, and telecommunications business grew by 16% in the recent quarter, showing that its efforts to diversify are gaining some traction.
Operating margins, which measure profit as a percentage of revenue, stood at 14.8% for the quarter. This figure was somewhat pressured by the costs associated with starting up these new, large contracts. Mphasis has maintained its profit margin guidance for the full year between 14.75% and 15.75%. However, the company faces a balancing act: it needs to continue investing in new AI platforms and capabilities to stay competitive, while also ensuring that these investments do not hurt profitability in the short term.
The next steps for the company will involve moving these signed contracts into the delivery phase. If Mphasis can improve its profit margins as these projects ramp up, it would show that its strategy of focusing on platform-based services is working. Investors should track whether the company can maintain this booking momentum without needing to spend significantly more on costs, which could otherwise limit its ability to increase profits.