

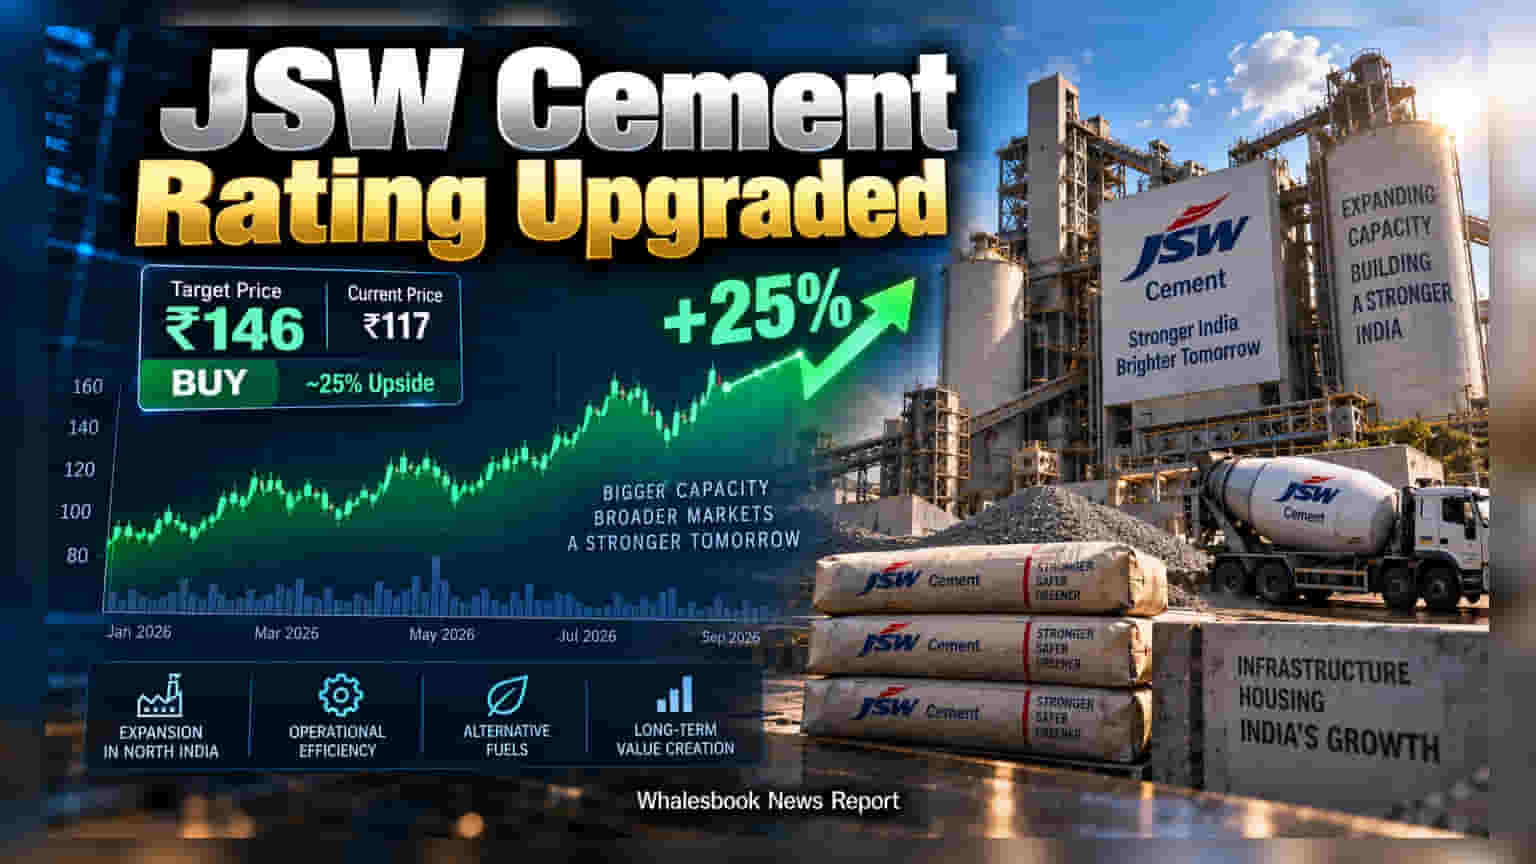
Motilal Oswal has upgraded JSW Cement to a 'Buy' rating, predicting a 25% upside to ₹146 per share. The brokerage highlights the company's shift into North India as a key growth driver. However, investors should note that the broader cement industry currently faces challenges, including high input costs and pricing pressure that could impact profit margins.
Motilal Oswal Financial Services has revised its outlook on JSW Cement, upgrading the stock to a 'Buy' rating. The brokerage set a target price of ₹146, which suggests an upside of approximately 25% from its recent trading price of ₹117. This shift in sentiment is driven by the company’s strategic transition from a regional player, which historically relied on ground granulated blast furnace slag, to a geographically diversified and fully integrated cement manufacturer.
The central pillar of this optimism is the company's expansion into North India. Historically, many cement companies have found that geographic diversity helps in managing regional demand cycles. By entering the North Indian market, JSW Cement aims to access regions where pricing dynamics may allow for better profitability compared to its traditional strongholds. This expansion is designed to scale capacity and move the business toward a model that is less dependent on specific industrial by-products.
To justify this valuation, the brokerage used a ratio of 14 times the estimated EV/Ebitda for the financial year 2028. In simple terms, this is a method to measure the company's total value relative to its operational earnings. The stock is currently trading at 12 times this same metric, which analysts view as a discount compared to its initial listing levels. This gap between current trading and the target price forms the basis of the brokerage's positive outlook.
However, the cement industry as a whole is currently facing pressure. Companies across the sector are grappling with high input costs, such as energy and coal prices, which can eat into profit margins. Additionally, the industry has seen subdued pricing power, meaning companies often struggle to raise cement prices even when costs are high, due to stiff competition from established giants like UltraTech Cement, Ambuja Cements, and ACC. These 'margin headwinds' are a reality that investors should keep in mind, as they can lead to lower-than-expected profits even if the company's volume grows.
To combat these industry-wide pressures, JSW Cement is focusing on operational efficiency. The company is actively working to reduce variable costs by stabilizing its production facilities in North India. Other initiatives include optimizing logistics networks, increasing the use of alternative fuels to reduce reliance on traditional power sources, and expanding its renewable energy footprint. These steps are intended to provide earnings stability, but the final impact will depend on how successfully the company manages these costs against volatile industry prices.
Moving forward, investors may track whether the company can execute this expansion without cost overruns. Other important factors to watch include the actual demand levels in the new markets, the trend in cement prices across India, and how efficiently the company manages its debt during this capital-intensive expansion phase.