

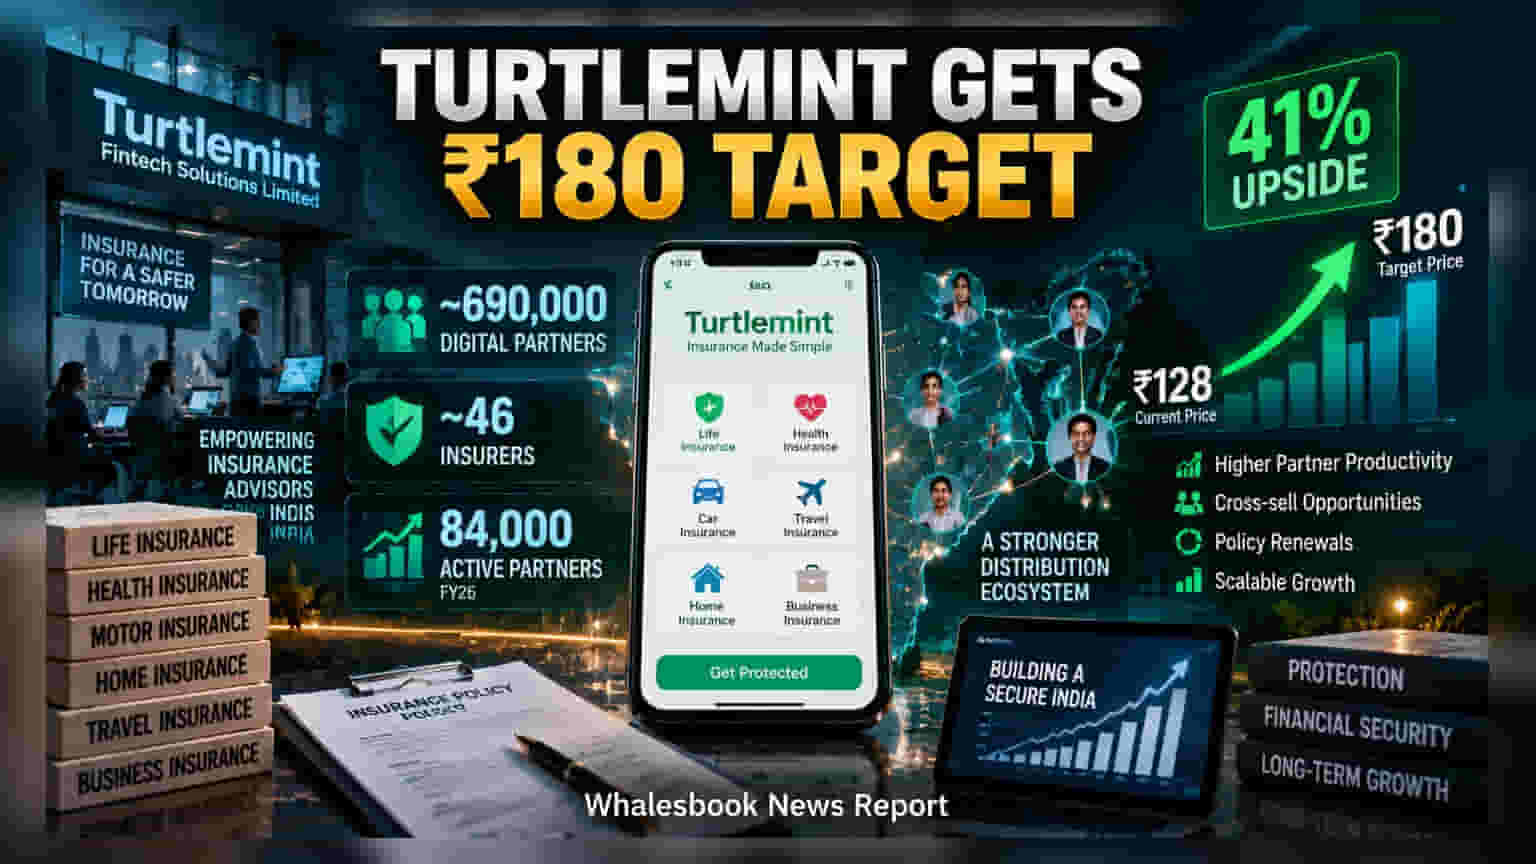
Brokerage firm Motilal Oswal has initiated coverage on Turtlemint Fintech Solutions with a Buy rating and a target price of ₹180. The report highlights a shift in the company’s business strategy, focusing on generating more revenue from its existing network of 690,000 digital partners rather than just adding new ones.
Motilal Oswal has begun tracking Turtlemint Fintech Solutions, initiating coverage with a Buy rating and setting a target price of ₹180. This target suggests an upside of approximately 41% from the recent trading price of ₹128. As a company that only listed on the stock exchanges on June 29, 2026, this brokerage coverage marks a new phase for the insurance technology firm as it looks to prove its business model to public market investors.
The core of the brokerage's investment case is not about the company's ability to add new partners, but rather its capacity to monetize the massive network it has already built. Turtlemint currently operates with a network of over 690,000 digital partners, also known as Point of Sale Persons, who distribute insurance products. The brokerage notes that the company is transitioning toward getting these existing partners to be more productive, cross-sell insurance products, and ensure policies are renewed, which provides a more stable revenue stream.
Data points mentioned in the report show a positive trend in activation. The number of active transacting digital partners reached roughly 84,000 in the 2026 financial year, up from 63,000 in the previous year and 50,000 in the year before that. This progression is what the brokerage is watching closely, as turning a registered partner into a revenue-generating, active partner is essential for the company's long-term profitability.
Challenges and Execution Risks
While the growth potential is a key focus, investors should be aware of the execution risks inherent in this business model. A large registered partner base does not automatically guarantee high revenue. The company’s financial performance depends heavily on the activation rate of these partners, meaning the firm must consistently keep them engaged to sell insurance policies. If the company fails to maintain or improve advisor productivity, it could face pressure on its revenue growth.
Additionally, the insurance distribution sector is highly regulated in India. Any changes in government policy regarding insurance distribution, commission structures, or regulatory requirements could directly impact the company's business model. As a recently listed entity, the stock may also experience higher price volatility as the market adjusts to the company's performance relative to these expectations. Investors should keep an eye on key operating indicators such as partner activation rates, renewal ratios, and the company's ability to successfully sell a mix of insurance products through its partners in the coming quarters.