

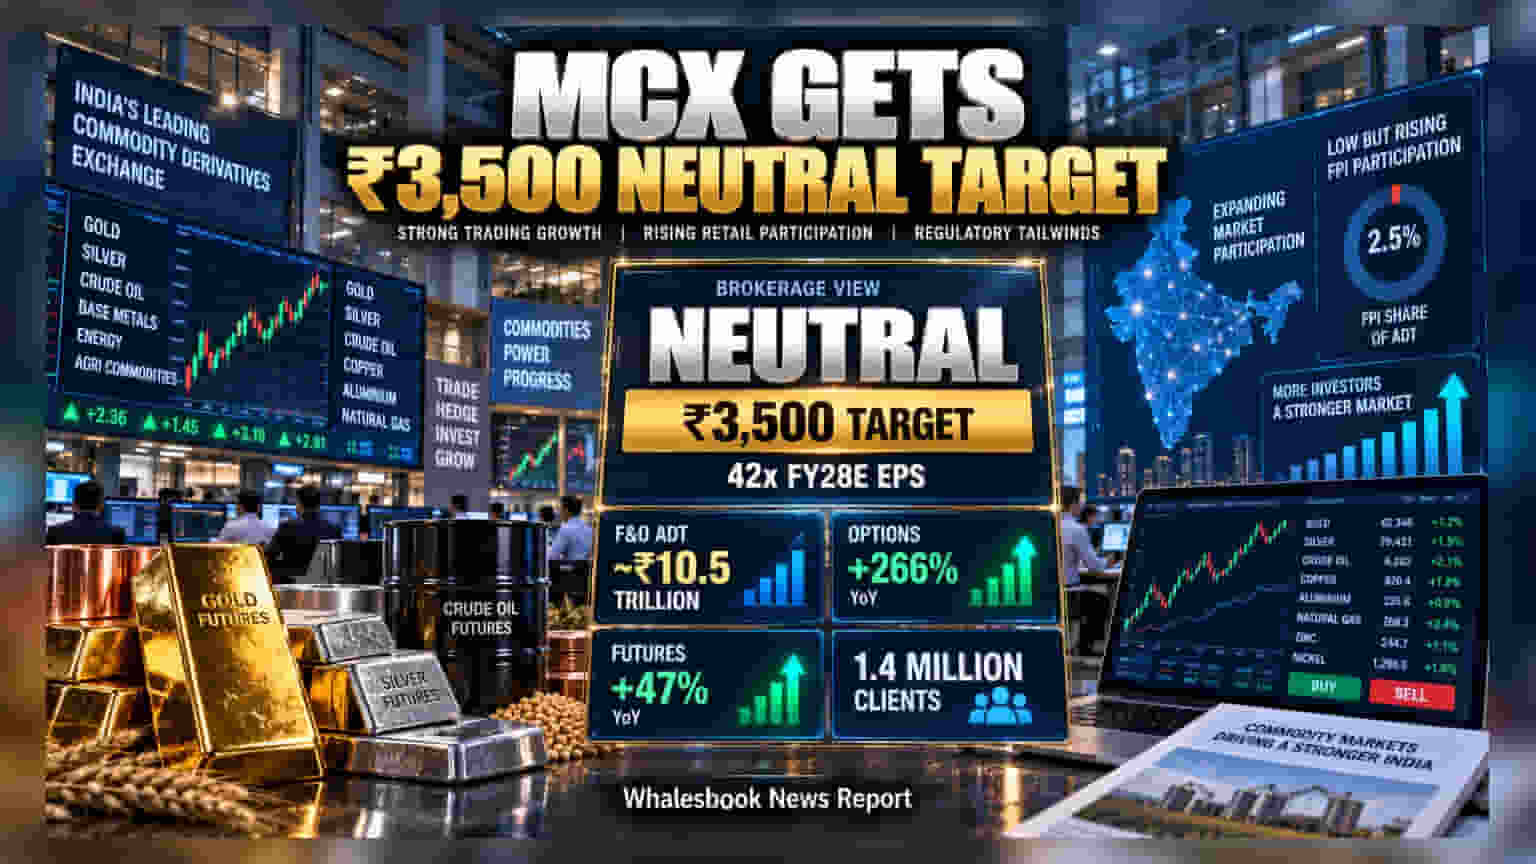
Motilal Oswal has kept a 'Neutral' rating on Multi Commodity Exchange of India (MCX) with a target of ₹3,500. While the exchange saw a 266% jump in options turnover and strong client growth in Q1 FY27, the brokerage believes the stock's current valuation already reflects these gains.
Motilal Oswal has reiterated a 'Neutral' rating on the Multi Commodity Exchange of India (MCX) with a one-year target price of ₹3,500. This stance comes even as the exchange reports strong operational growth, highlighting a disconnect between current business performance and stock valuation.
The exchange's business has grown significantly, supported by a 266% year-on-year surge in options notional average daily turnover and a 47% rise in futures turnover during the first quarter of fiscal year 2027. Trading activity on the platform also deepened, with the number of active clients increasing by 95% year-on-year to 1.4 million. In its recent financial results for Q1 FY27, MCX reported a net profit of ₹413.44 crore, marking a 103% increase compared to the same period last year. However, investors may note that this figure represented a 22% decline compared to the previous quarter (Q4 FY26), reflecting some sequential volatility in earnings.
Despite the strong year-on-year operational performance, the brokerage has stopped short of a 'Buy' recommendation. This cautious approach is primarily linked to the stock’s valuation, which currently stands at 42 times estimated earnings for FY28. According to Motilal Oswal, the market has already factored in much of the expected growth, leaving limited room for immediate upside unless the company can deliver sustained, high-level execution.
Looking ahead, the exchange's future performance may depend on regulatory developments. SEBI is currently working on proposals to allow co-location services and expand access for foreign portfolio investors (FPIs) in the commodity derivatives market. These changes could potentially boost liquidity and institutional participation. Currently, institutional engagement remains low, with FPIs contributing only about 2.5% of the average daily turnover despite a small increase in the number of active foreign participants.
For shareholders, the primary monitorables remain the persistence of elevated derivatives turnover and the actual impact of regulatory changes on market liquidity. While the growth in retail participation is a positive sign for exchange economics, the stock's performance will likely hinge on whether the company can maintain these high trading volumes while managing operational costs and proving that it can justify its current market valuation through consistent future earnings growth.