

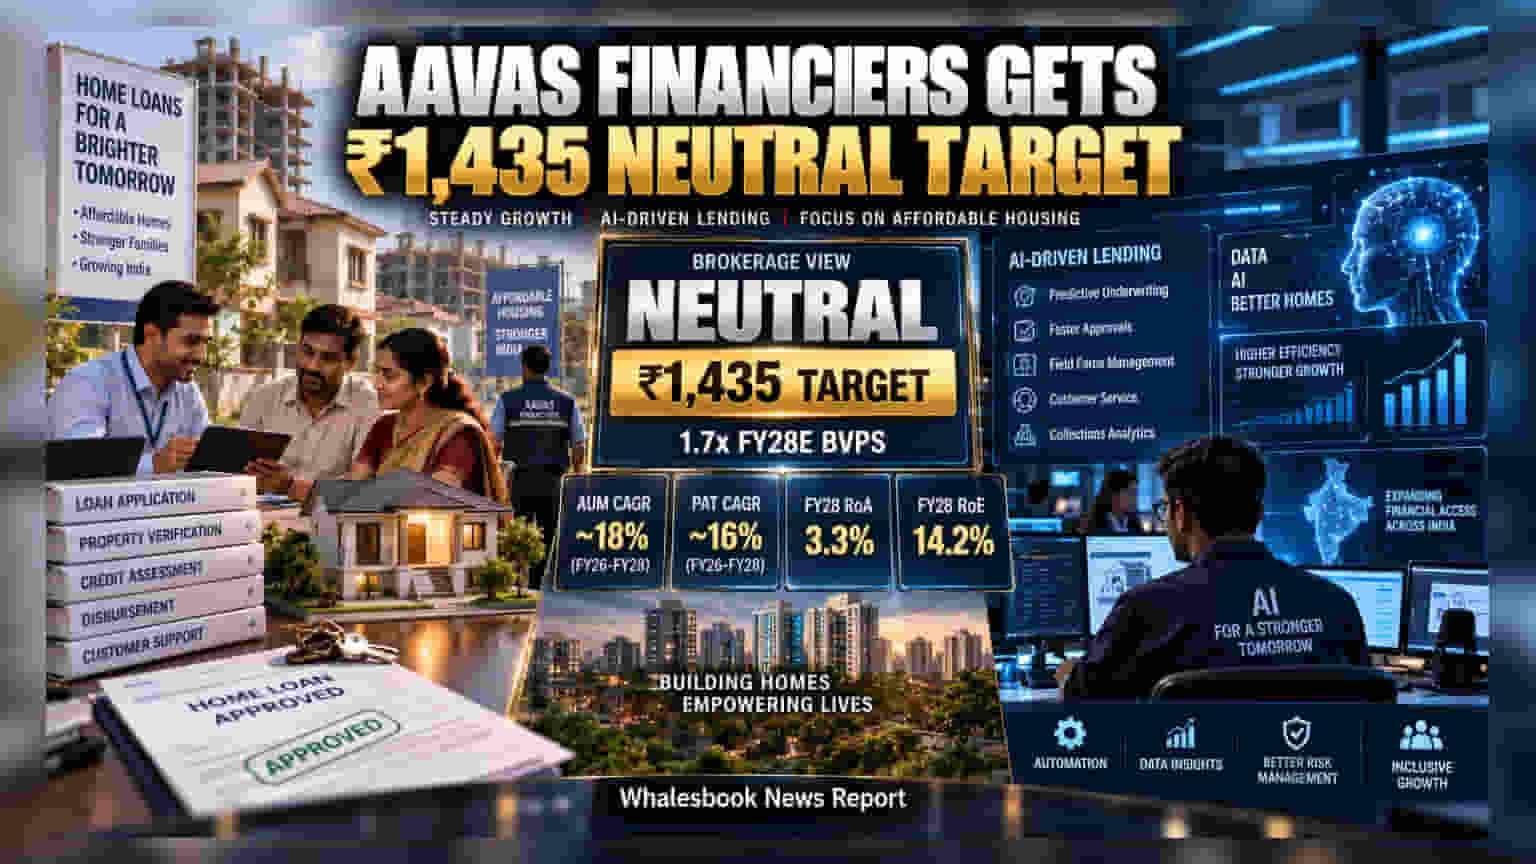
Motilal Oswal has kept its Neutral rating on Aavas Financiers with a target price of ₹1,435 following a review of the lender’s technology and AI strategy. While the brokerage expects healthy double-digit growth in assets and profit through FY28, the current valuation keeps the rating unchanged.
Motilal Oswal has reiterated a Neutral rating on Aavas Financiers, setting a target price of ₹1,435 per share. This decision follows a detailed review of the housing finance company’s technology infrastructure and its integration of artificial intelligence across various lending operations.
The housing financier is actively deploying data and AI tools to manage different parts of its business, including loan origination, underwriting, field-force management, and customer service. According to the brokerage, the goal is to shift from manual, paper-heavy processes to more automated digital workflows. By using predictive analytics and AI applications, Aavas Financiers aims to improve the speed of processing loan applications and ensure greater consistency when deciding who gets a loan.
From a financial perspective, the brokerage has outlined a positive growth outlook for the company. It projects that Aavas Financiers’ assets under management will grow at a compound annual growth rate of approximately 18% between FY26 and FY28. Over the same three-year period, profit after tax is expected to grow at about 16%. By FY28, the brokerage estimates the company could achieve a return on assets of 3.3% and a return on equity of 14.2%.
Despite these growth projections, the brokerage maintains a Neutral stance. This suggests that while the company's expansion plans and technology investments are viewed positively, the current market price and valuation leave limited room for further upside in the short term. The valuation is based on approximately 1.7 times the estimated book value per share for FY28.
For investors, it is important to distinguish between the company’s tech-driven operational changes and the actual financial results. Technology upgrades in areas like underwriting and customer retention are designed to drive efficiency, but their success will ultimately be measured by whether they can boost volumes and profitability without compromising on credit quality.
Like many peers in the affordable housing finance sector, Aavas Financiers faces inherent challenges. These include the risk of execution when rolling out large-scale digital platforms and the competitive pressure to maintain profit margins in a cost-sensitive market. Additionally, the sector remains sensitive to interest rate fluctuations and shifts in housing demand. As the company continues its digital journey, investors may track whether these technology initiatives translate into sustained improvements in operating productivity, asset quality, and loan growth in the coming quarterly results.