

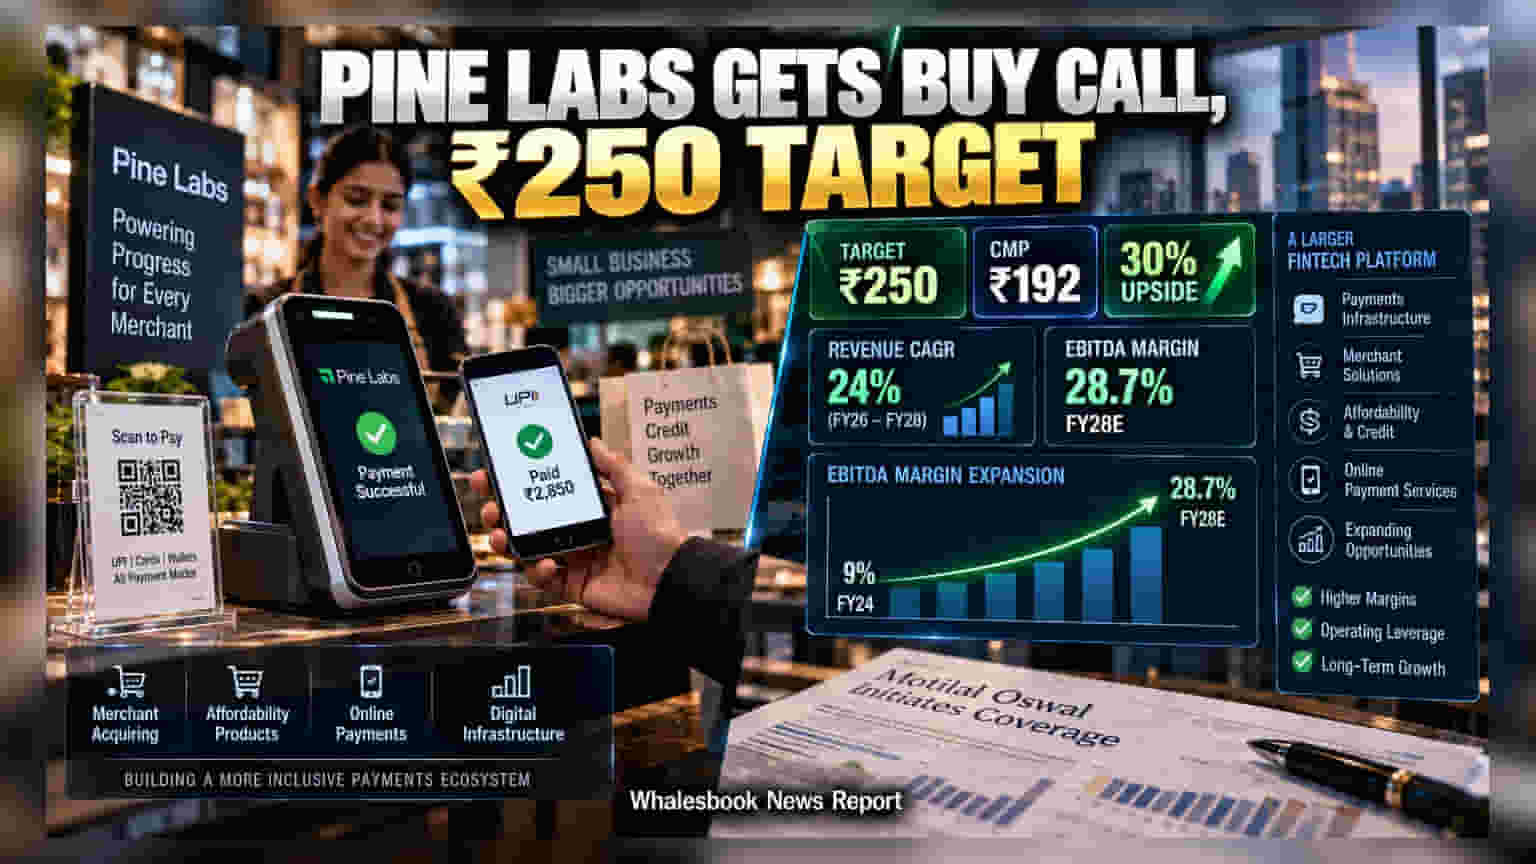
Motilal Oswal has initiated coverage on unlisted fintech firm Pine Labs with a target price of ₹250, indicating a potential 30% upside from its unlisted market price of ₹192. The brokerage projects a 24% compound annual revenue growth through FY28, with a significant shift toward higher-margin transaction and affordability services.
Motilal Oswal has initiated research coverage on the unlisted financial technology company Pine Labs, assigning it a target price of ₹250. This initiation follows the company's valuation in the unlisted or pre-IPO market, where the stock has been trading around ₹192. As a private entity, Pine Labs does not trade on the main Indian stock exchanges like the NSE or BSE, meaning investor access is currently limited to the unlisted equity space.
The brokerage's report builds a case for growth by looking beyond traditional payment processing. The investment thesis centers on Pine Labs evolving into a comprehensive platform that includes digital infrastructure, merchant-focused affordability solutions, and online payment services. Motilal Oswal expects the company's revenue to grow at a compound annual rate of approximately 24% between FY26 and FY28. The core of this revenue growth is expected to come from digital infrastructure and transaction-platform services, which are projected to account for about 68% of the company's total revenue.
A significant part of the brokerage's positive outlook depends on a sharp improvement in profitability. The report projects that Pine Labs' adjusted EBITDA margin could climb from approximately 9% in FY24 to 28.7% by FY28. This expectation assumes that the company will successfully scale its higher-margin transaction-led businesses and benefit from stronger operating leverage as its platform grows. The brokerage also forecasts that EBITDA could grow at a compound rate of 46% during the same three-year period, with Profit After Tax (PAT) growth expected to be even steeper.
The report also identifies potential revenue support from the possible implementation of a 0.4% merchant discount rate (MDR) on specific person-to-merchant payment flows. Since Pine Labs operates a large merchant-acquiring network, any move to monetize these transactions could create a new revenue stream. However, the brokerage noted that the final impact on financials will depend on the implementation details, transaction eligibility, and the volume of payments processed through these channels.
For investors monitoring this space, the primary risks involve the company's ability to execute its expansion strategy while maintaining profitability. The valuation provided by the brokerage already accounts for strong growth, meaning that any failure to hit the projected 24% revenue growth or any struggle to reach the 28.7% EBITDA margin target could affect the outlook. Furthermore, as a player in the competitive fintech sector, Pine Labs faces pressure to scale its higher-margin products like affordability and online payment services. The mix of revenue between these segments and the company's established digital infrastructure will be a key factor to watch, as it will determine the extent of the operating leverage the company can generate in the coming years.