

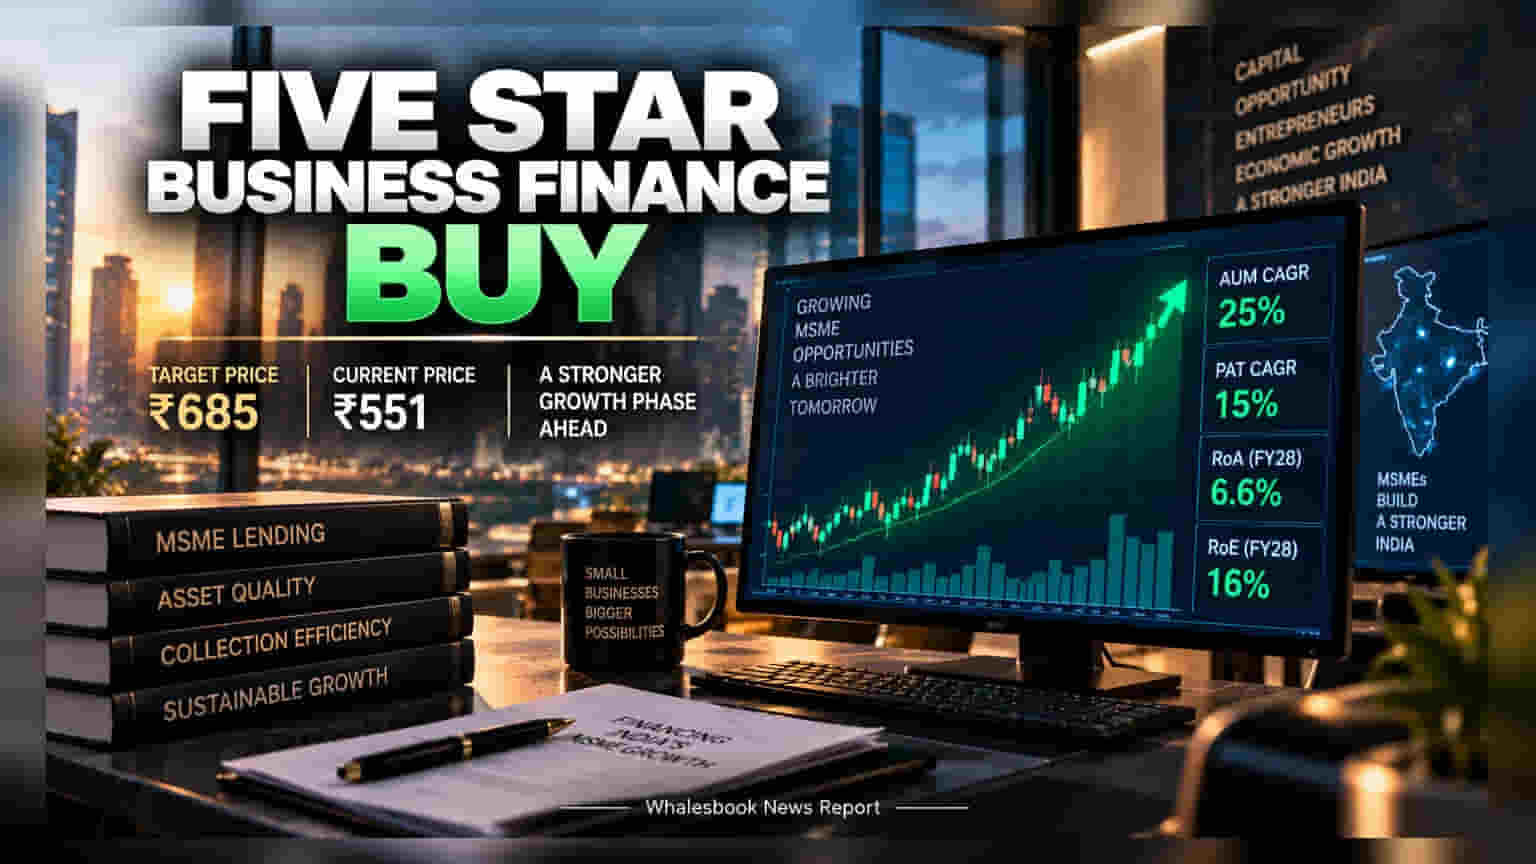
Motilal Oswal has initiated a 'Buy' rating on Five Star Business Finance with a target price of Rs 685. The brokerage expects the company to return to growth as it shifts focus from a collection-heavy strategy back to new loan disbursements. Investors are tracking this transition as the company aims for a 25% CAGR in assets under management over the coming years.
Motilal Oswal has assigned a 'Buy' rating to Five Star Business Finance, setting a target price of Rs 685 per share. As of mid-September 2026, the company's stock was trading around the Rs 551 level. The brokerage's positive outlook is based on a shift in the company's operational strategy, which is expected to support future growth.
Transition from Collection to Growth
Five Star Business Finance, which operates in the MSME lending sector, has spent the recent past focusing heavily on collections rather than new loan growth. This shift was largely a response to sector-wide challenges, including borrower overleveraging and regulatory pressures that made it difficult to expand aggressively. By prioritizing the collection of existing dues, the company worked to maintain asset quality and manage risk during a challenging period.
Motilal Oswal notes that these operational headwinds are now beginning to subside. With slippages stabilizing and collection efficiency showing improvement, the company is now in a position to pivot back toward growth. This involves accelerating new loan disbursements, which is a key driver for future revenue.
Financial Projections
The brokerage anticipates that this return to growth will reflect in the company’s financial performance over the FY26-28 period. Financial projections suggest a compound annual growth rate (CAGR) of approximately 25% for Assets Under Management (AUM) and 15% for Profit After Tax (PAT). By FY28, the brokerage expects the company to achieve a Return on Assets (RoA) of 6.6% and a Return on Equity (RoE) of 16%.
Risks and Market Context
While the outlook is positive, the company still operates within a sector sensitive to economic cycles. A primary risk for investors remains the potential for borrower overleveraging, which could resurface if economic conditions tighten. Furthermore, the company’s portfolio yields may be subject to pressure if it decides to pass on cost savings to borrowers through lending rate cuts. Regulatory developments also remain an important factor, as any sudden change in rules regarding MSME lending can impact operational flexibility.
The stock currently trades at roughly 1.9 times its projected FY27 book value. Moving forward, investors should monitor the company's actual disbursement momentum and its ability to maintain asset quality as it scales its loan book. The sustained stability of collection efficiencies will be a critical metric to watch in upcoming quarterly reports, as it will determine whether the company can meet its growth targets without compromising its balance sheet.