

Motilal Oswal has identified Emcure Pharmaceuticals and Cholamandalam Investment and Finance as growth prospects for the week of September 15, 2026. The brokerage focuses on Emcure’s international expansion and Cholamandalam’s strategic shift toward a diversified lending model.
Motilal Oswal Wealth Management has featured Emcure Pharmaceuticals and Cholamandalam Investment and Finance Company in its recent outlook, highlighting them as key growth prospects for the week. The brokerage’s focus centers on the unique strategic paths both companies are taking within their respective sectors.
Emcure Pharmaceuticals: Scaling Global Operations
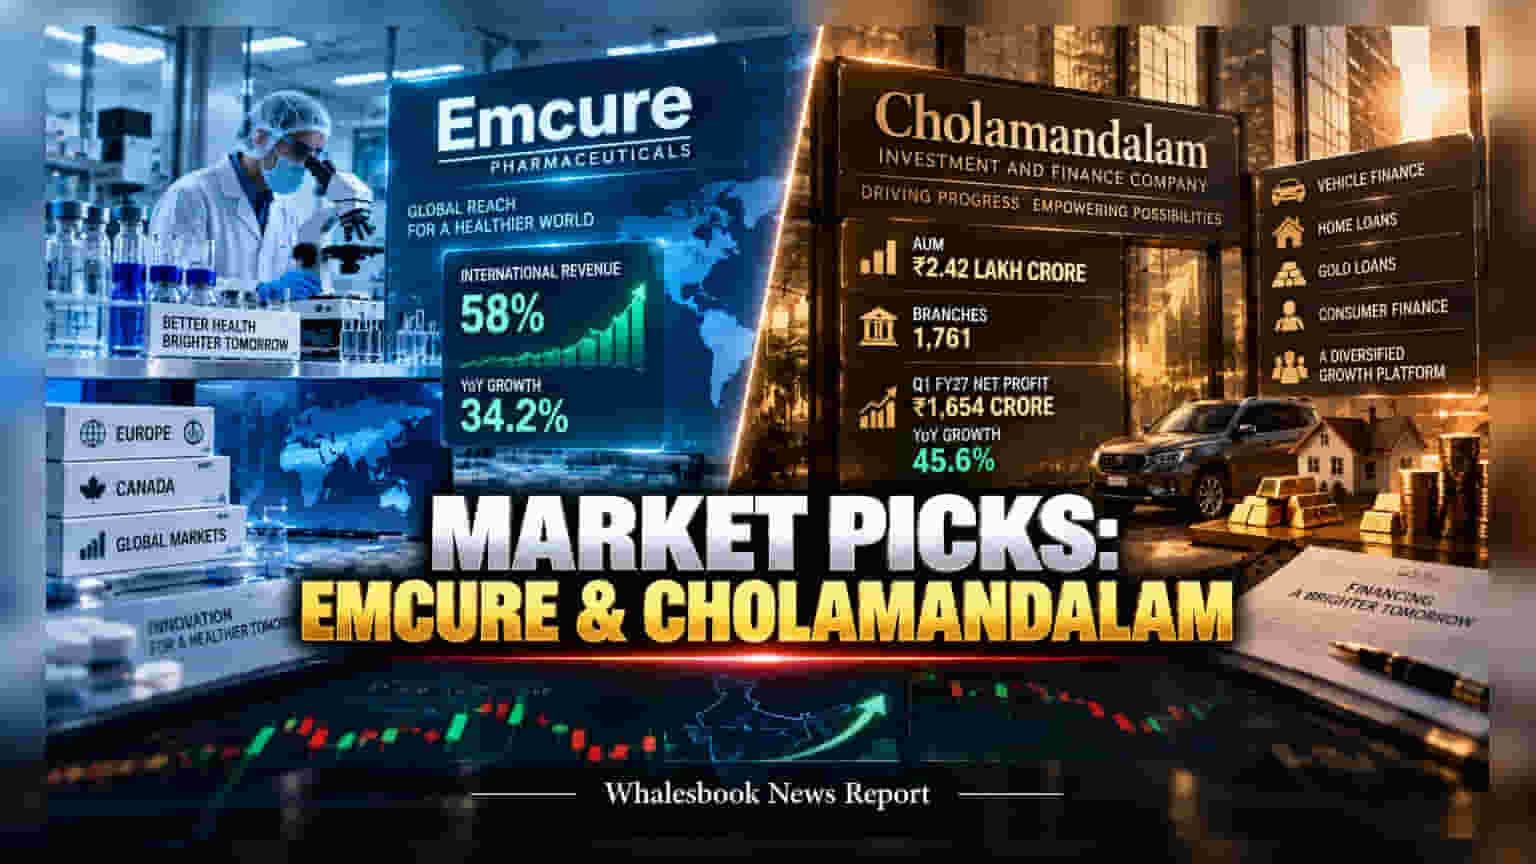
Emcure Pharmaceuticals has been drawing attention for its aggressive expansion into international markets, including Europe and Canada. According to recent data, the company’s international business now accounts for 58% of its total revenue, growing at 34.2% year-on-year. This global pivot is a core element of the firm’s strategy to reduce dependency on domestic markets.
Financially, the company reported a revenue of INR 25.8 billion for the first quarter of fiscal year 2027, marking a 22.8% increase compared to the previous year. While the revenue trajectory appears positive, investors may keep an eye on profit margins. The company faces potential margin pressure as it balances its evolving product mix with the costs associated with international expansion and domestic operational execution. Monitoring how the company maintains its profitability while funding its global growth will be an important factor for shareholders.
Cholamandalam Investment and Finance: Broadening the Lending Base
Cholamandalam Investment and Finance Company is in the midst of a significant shift, moving from its traditional base in vehicle finance to a more diversified lending platform. This transition includes scaling up its mortgage, gold loan, and consumer finance segments, which the firm expects will stabilize its earnings profile.
The company’s scale is notable, with assets under management exceeding INR 2.42 lakh crore, supported by an expansive network of 1,761 branches. In the first quarter of fiscal year 2027, the company reported a revenue of INR 8,933 crore and a net profit of INR 1,654 crore, reflecting a 45.6% year-on-year growth. Despite this strong operational performance, the company faces potential headwinds from interest rate volatility. Analysts anticipate a rise in funding costs by 10 to 20 basis points in the second half of fiscal year 2027, which could test the resilience of net interest margins.
Furthermore, while the firm’s growth outlook remains robust, investors may note that the stock currently trades at a valuation of approximately 4.1x to 5.16x the projected price-to-book ratio for fiscal year 2027. This premium valuation suggests that the market has high expectations for the company’s ability to maintain its return on equity and asset growth, making these metrics key monitorables for the coming quarters.