

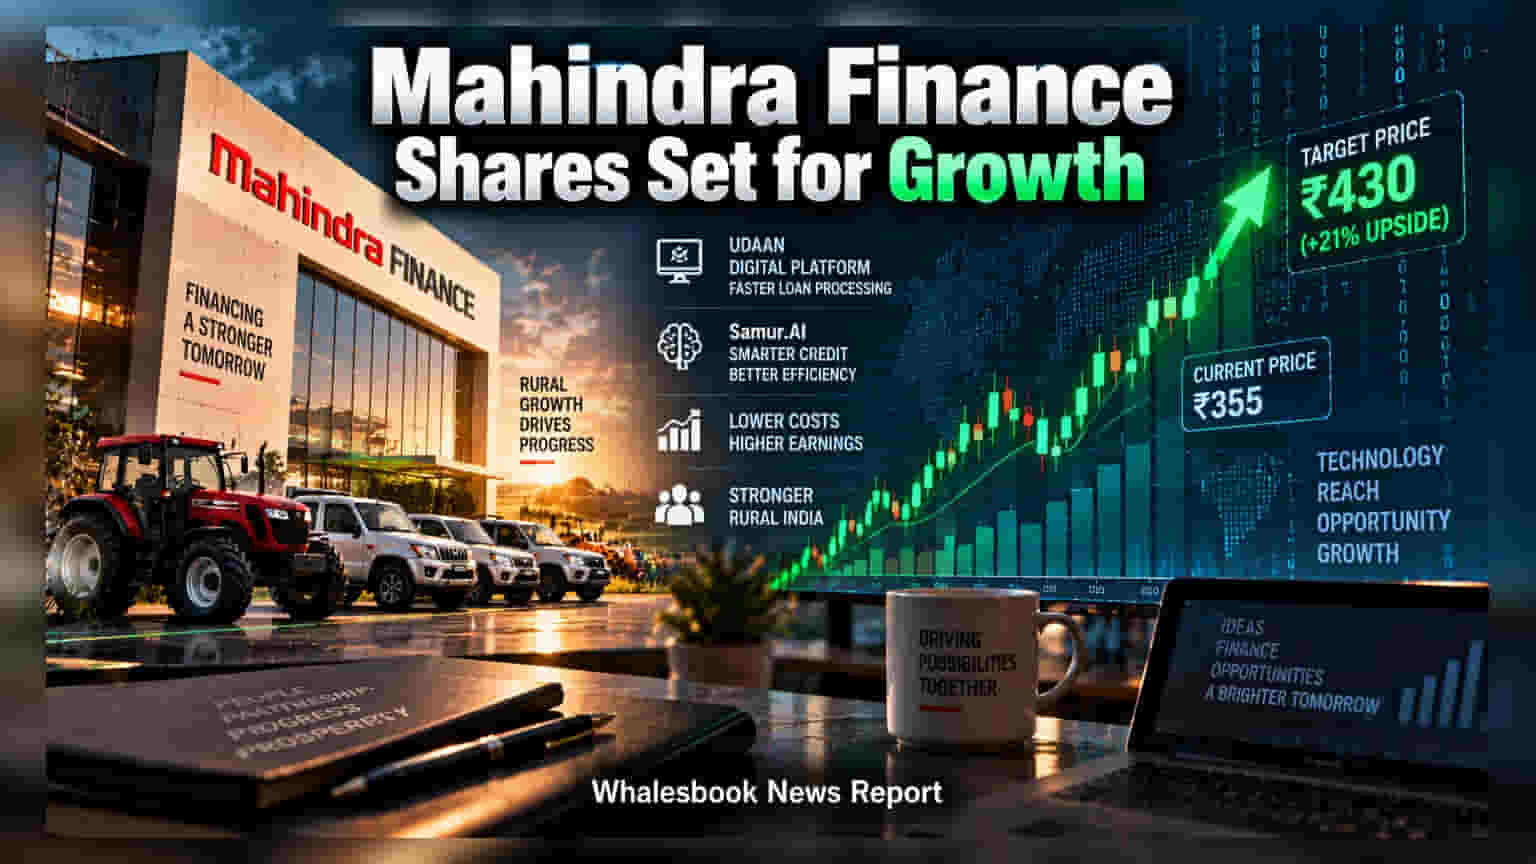
Motilal Oswal has maintained a positive outlook on Mahindra & Mahindra Financial Services with a price target of Rs 430. The brokerage believes the company's digital 'Udaan' platform and AI tools will improve operational efficiency. Investors are now watching to see if these technology investments can lower costs and sustain profit margins in a competitive NBFC sector.
Motilal Oswal has maintained a positive stance on Mahindra & Mahindra Financial Services, setting a price target of Rs 430. Based on the recent trading price of approximately Rs 355, the brokerage projects a potential upside of about 21%. This outlook is tied to the company's strategy of using digital technology to lower costs and boost earnings.
Scaling Through Digital Initiatives
At the center of this strategy is the 'Udaan' digital platform. The company is using this tool to speed up loan processing and improve how it handles dealer conversions. In the NBFC sector, where physical branch networks have historically been necessary for rural and semi-urban lending, digital platforms are being used to reduce the cost of doing business. By automating parts of the process, the company aims to increase productivity without needing to open as many new branches as it did in the past.
Furthermore, the integration of artificial intelligence, specifically the 'Samur.AI' system, is being used to streamline back-end operations. The goal is to improve the speed of service delivery and credit assessment. If successful, this can lead to better profit margins by reducing the cost-to-income ratio, which is a common metric used to measure efficiency in financial companies.
Business Risks and Monitoring
While technological updates are helpful, investors should remember that Mahindra Finance operates in the rural and vehicle finance sector, which is sensitive to economic cycles. The demand for tractors and vehicles in rural areas depends heavily on factors like crop cycles and monsoon patterns. Even with better technology, the company’s ability to maintain profit growth remains linked to how well it manages credit risk and collects payments from borrowers in these areas.
Historically, the key monitorable for any NBFC is asset quality, which refers to the level of bad loans. Investors should track whether the new digital tools help in better recovery of loans or if credit costs remain high. The company's strategy of deeper branch-level penetration to drive cross-selling of financial products will also determine if it can grow its income in a crowded market where it competes with both large banks and other major non-banking lenders.
The next few quarters will provide a clearer picture of whether these technology-led efficiency gains are translating into long-term improvements in the company's financial health, particularly in its credit cost management and overall profitability.