

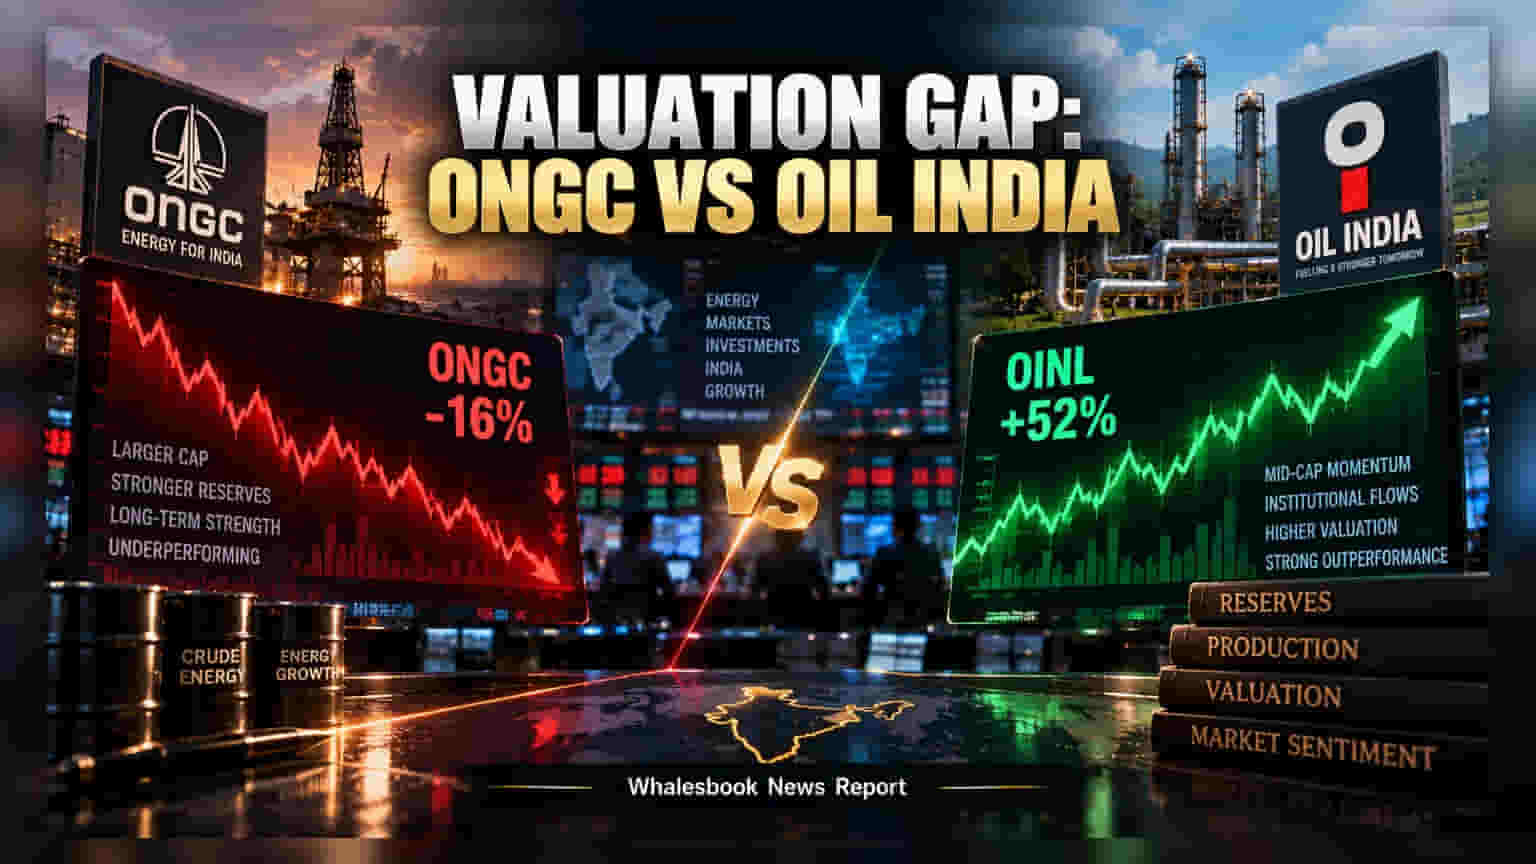
Kotak Securities notes that Oil India’s recent market outperformance relative to ONGC is driven by investor interest in mid-cap stocks rather than operational superiority. Analysts point to ONGC’s stronger long-term reserve base and production outlook as reasons why the valuation gap may not be fundamentally supported.
Kotak Securities has flagged a growing valuation gap between Oil India and its larger peer, Oil and Natural Gas Corporation (ONGC). In a recent analysis, the brokerage highlighted that Oil India has significantly outperformed ONGC since February 2026, a trend that experts believe is being driven by market sentiment rather than a fundamental difference in business quality. Despite operating under similar fiscal regimes and navigating the same global energy environment, the two state-owned companies have seen a divergence in their share price performance that analysts find difficult to justify.
The Mid-Cap Rally Effect
The primary driver behind this performance difference appears to be institutional capital flows. Recent market trends show a distinct investor preference for mid-cap stocks, which has provided a boost to Oil India’s share price. As investors shift money into mid-cap mutual funds and strategies, companies like Oil India benefit from the liquidity, even if the underlying business metrics have not improved disproportionately compared to large-cap peers like ONGC. This structural preference for mid-cap equities has created what the brokerage describes as a valuation premium for Oil India that is not backed by operational advantages.
Fundamentals vs Market Sentiment
While Oil India has shown growth in crude oil volume projections for the upcoming fiscal year, ONGC maintains a structural advantage in terms of its long-term reserve-to-production ratio. This ratio is a vital indicator for long-term investors, as it measures the sustainability of a company’s production capacity. Analysts note that claims suggesting ONGC suffers from poor capital allocation or lack of terminal value are not supported by the data. When comparing the two, ONGC’s larger, more stable reserve base typically provides greater earnings durability, which the current market pricing seems to be ignoring in favor of the mid-cap momentum that is lifting Oil India.
The Crude Price Anomaly
The market’s reaction to energy sector volatility also presents an interesting case of mispricing. Despite a sharp increase in global crude oil prices—up by 77% since the rise of geopolitical tensions in West Asia—ONGC’s stock has paradoxically declined by 16% over the same period. This suggests that the market may be prioritizing short-term trends and liquidity over the actual production capacity and long-term earnings potential that traditional valuation models would typically value. For investors, this disconnect raises questions about whether the current market pricing is ignoring the potential value in large-cap energy holdings.
Moving forward, investors may track whether the mid-cap momentum sustains or if valuation gaps begin to narrow as the market refocuses on fundamental metrics like reserve strength, production efficiency, and long-term earnings durability. The key monitorable will be whether ONGC can attract renewed investor interest if the broader market preference shifts away from the current mid-cap-heavy cycle.