

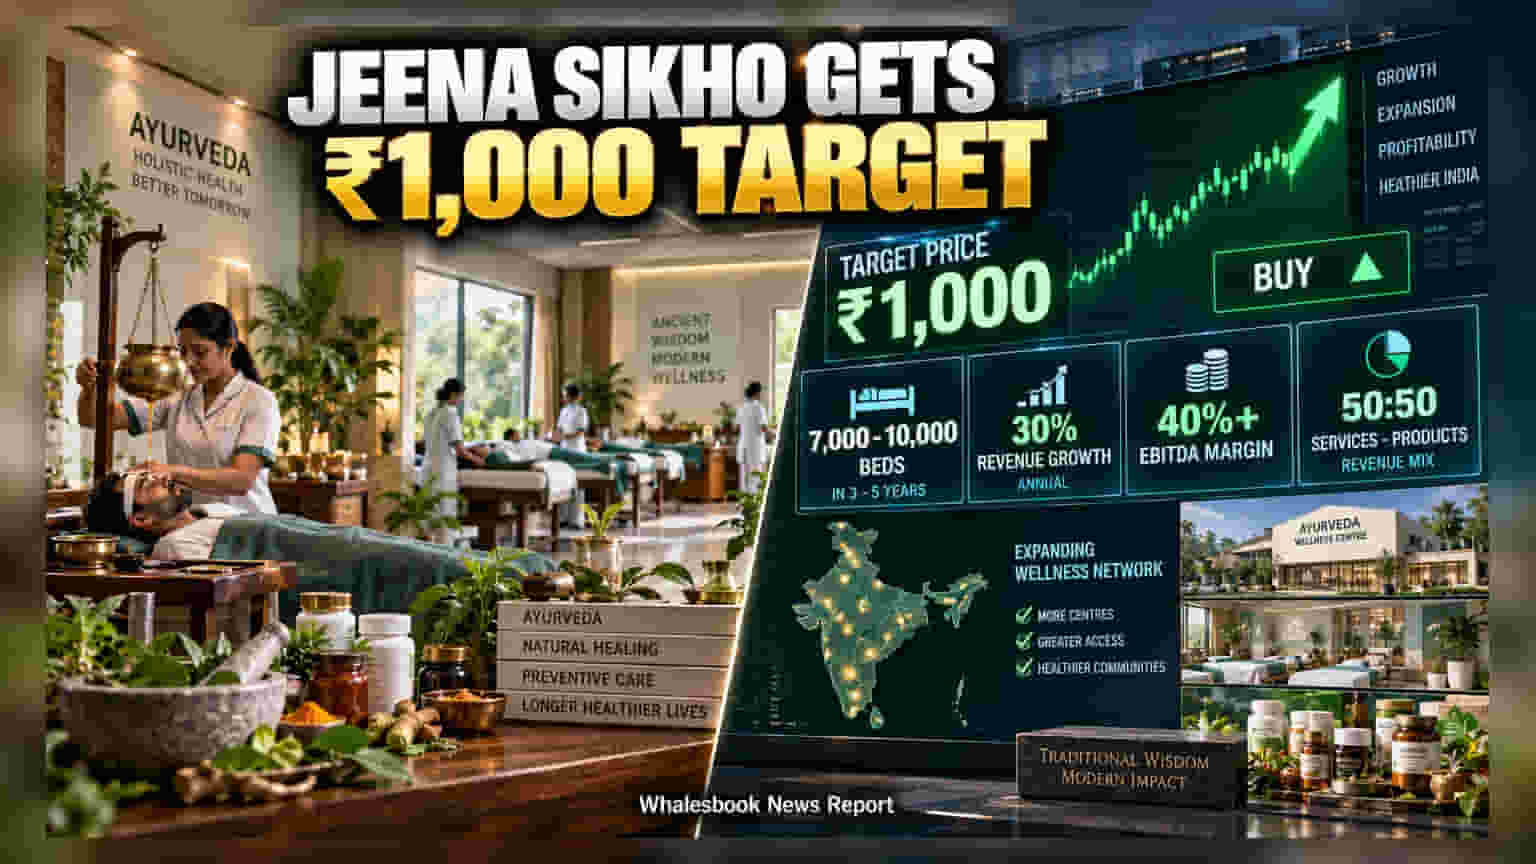
Jeena Sikho Lifecare plans to expand its Ayurveda network to 7,000-10,000 beds over five years, targeting 30% annual revenue growth. Choice Institutional Equities has released a report with a ₹1,000 target, citing the company's expansion strategy. However, the company faces the challenge of maintaining high profit margins and service quality while scaling up its operations.
Jeena Sikho Lifecare is embarking on an ambitious expansion plan to scale its Ayurveda healthcare network. The company management has outlined a goal to increase its total operational capacity to between 7,000 and 10,000 beds within the next three to five years. This strategy, which relies on a capital-efficient expansion model rather than heavy upfront spending on every location, has drawn attention from market analysts.
Choice Institutional Equities recently issued a report on the company, projecting a target price of ₹1,000. This valuation is based on the brokerage's assessment of the company's future earnings potential and its ability to manage growth without excessive capital investment. The report highlights that successful execution of this plan could lead to significant financial growth for the company.
Management has set high bars for performance, guiding for roughly 30% annual revenue growth over the next few years. The company is also working to balance its income sources, aiming for an equal split between its treatment services and its wellness product portfolio. This approach is intended to reduce reliance on any single revenue stream and support long-term stability. The stated financial targets include maintaining profit margins above 40%, with management aiming for net profit to increase four to five times over the next few years.
However, expanding a healthcare and wellness business comes with clear operational tests. The main hurdle for the company will be scaling its network without diluting the quality of care or the efficiency of its operations. High-growth healthcare models often face pressure on profit margins if facility costs, staffing expenses, and patient utilisation rates are not managed carefully. Sustaining a 40% margin while adding thousands of new beds will require disciplined execution.
Investors will need to monitor several key indicators as the company executes this plan. The primary monitorables include the actual pace of new bed additions, whether the company can maintain its projected profit margins, and if the revenue mix successfully shifts to the targeted 50:50 split between services and products. The brokerage's positive outlook is contingent on the company achieving both rapid growth and strict operating discipline at the same time, making the upcoming quarterly updates on expansion progress crucial for tracking performance.