

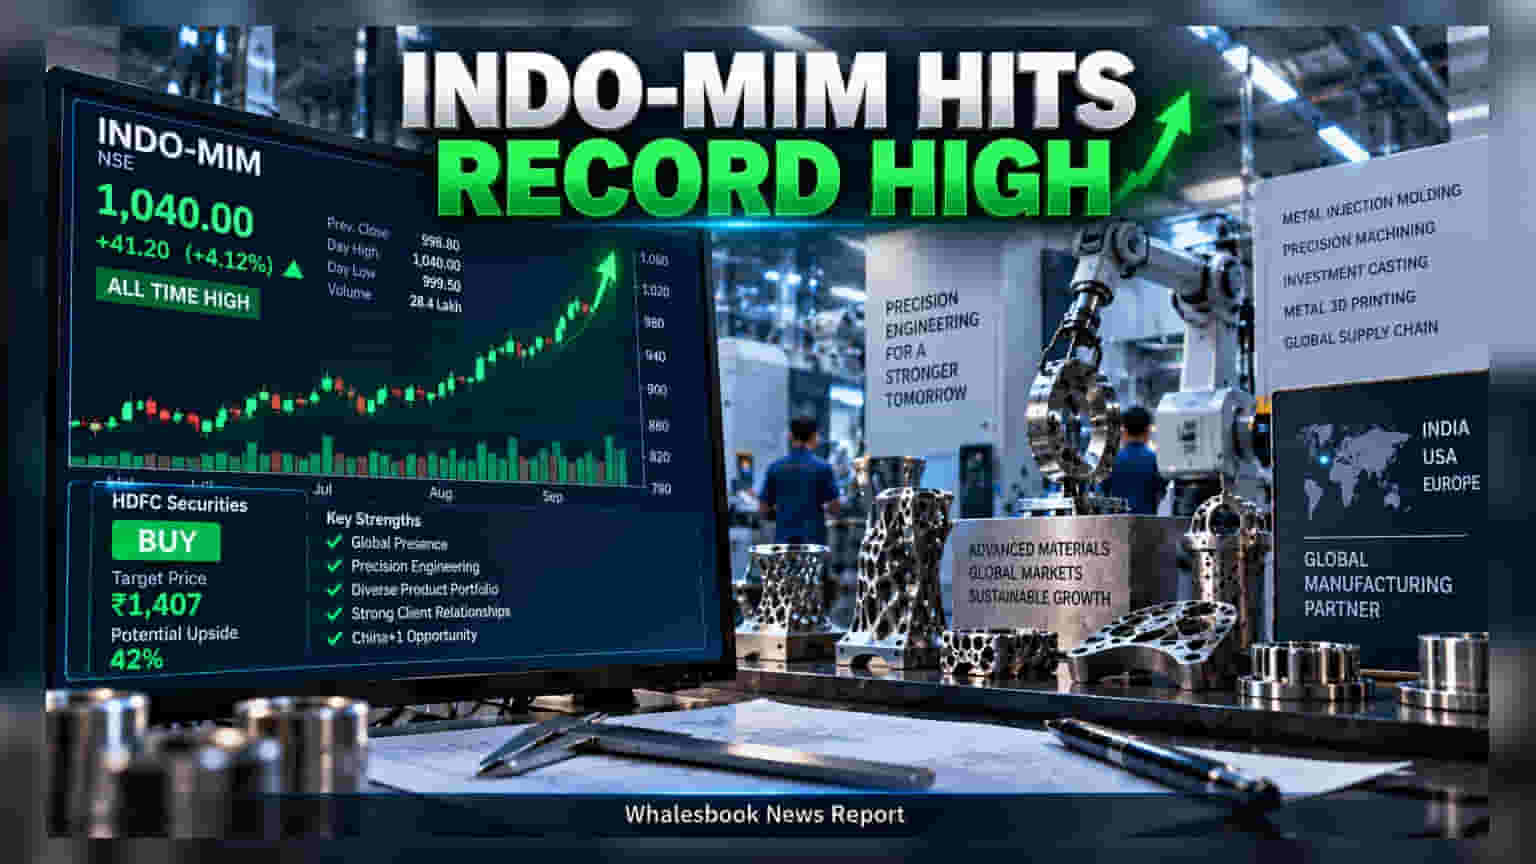
Indo-MIM shares reached a record high of Rs 1,040 following an initiation report by HDFC Securities, which set a price target of Rs 1,407. The company is recognized for its global leadership in metal injection molding, though investors should note that its high reliance on exports makes its performance sensitive to global demand and economic changes.
Shares of Indo-MIM Ltd. recently reached a new record high, rising over 4% to Rs 1,040 on the National Stock Exchange. This price movement follows a research report from HDFC Securities, which initiated coverage on the company with a 'Buy' rating. The brokerage set a target price of Rs 1,407, suggesting a potential 42% upside from the stock's previous closing price of Rs 993.
Indo-MIM specializes in metal injection molding, a process that uses fine metal powders to create complex components. Beyond this, the company has diversified into precision machining, investment casting, and metal 3D printing. This expanded range of services has allowed the firm to move beyond its role as a niche supplier and become a comprehensive manufacturing partner for original equipment manufacturers on a global scale. The company currently holds an estimated 7% share of the global metal injection molding market.
A core part of the company's growth strategy involves its global footprint, with operations spread across India, the United States, and Europe. Indo-MIM is often viewed as a potential beneficiary of the 'China+1' supply chain strategy, as global manufacturers look for production alternatives outside of China. However, this model comes with a distinct risk profile. Exports account for 77% of the company's total revenue, making its financial performance highly dependent on the manufacturing cycles and economic conditions of its international clients.
While the company benefits from a stable revenue base—with 91% of its income generated from repeat client contracts—its future growth depends on the successful execution of its expansion plans. Investors may want to look beyond the current market optimism and track the company's ability to maintain profit margins amid fluctuating raw material costs, which are critical in the precision engineering sector.
Ultimately, the company's performance will depend on its ability to manage global demand risks while successfully scaling its newer precision engineering and 3D printing segments. Investors should continue to monitor updates on export demand, contract renewals, and the company's ability to manage its international cost structures as it continues its expansion efforts.