

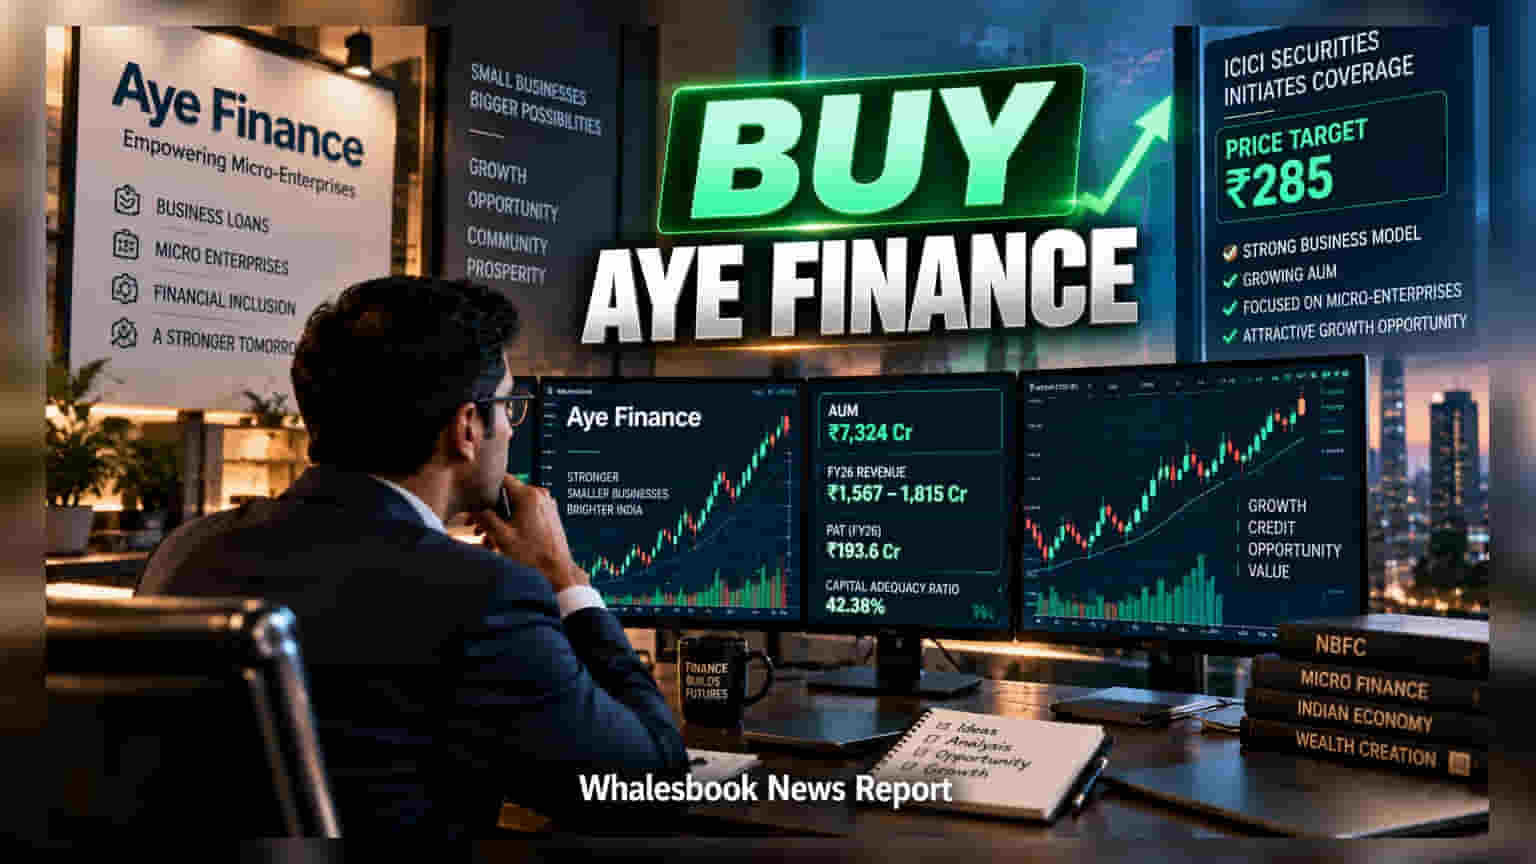
ICICI Securities has initiated coverage on non-banking financial company Aye Finance with a 'Buy' rating and a price target of Rs 285. The brokerage highlights the lender's strategic focus on the mid-sized micro-enterprise loan segment. Investors may track the company's asset quality and growth as it navigates the market following its February 2026 listing.
ICICI Securities has started tracking Aye Finance, assigning a 'Buy' rating to the stock with a price target of Rs 285. The coverage focuses on the company’s business model, which specializes in lending to micro-enterprises, a segment often underserved by larger financial institutions.
Strategic Focus on Micro-Loans
Aye Finance operates as a non-banking financial company (NBFC) that targets a specific niche in the lending market. While many lenders focus on either very small microfinance loans or larger vehicle and mortgage loans, Aye Finance concentrates on loan amounts ranging between Rs 1.5 lakh and Rs 5 lakh. By addressing this mid-sized loan segment, the company aims to support micro-enterprises that need more capital than standard microfinance offers but do not fit the profile of larger secured loan products.
Since its listing on the NSE and BSE on February 16, 2026, the company has worked to establish its presence in the public market. As of June 2026, the company reported assets under management (AUM) of approximately Rs 7,324 crore. For the full fiscal year 2026, Aye Finance recorded total revenue between Rs 1,567 crore and Rs 1,815 crore, with a profit after tax of approximately Rs 193.6 crore. The company maintains a strong capital buffer, with a capital adequacy ratio reported at 42.38%, which indicates a solid foundation to support potential lending growth.
Business Risks to Monitor
While the company has shown consistent growth, investors should consider the inherent risks associated with its business model. The primary challenge for any NBFC focused on small-ticket, unsecured, or micro-loans is asset quality. If the borrowers face financial difficulties, it can directly impact the company's ability to recover loans, potentially leading to higher bad debts or provisions that hurt profitability.
Furthermore, the micro-enterprise lending space is highly competitive, with various banks and other NBFCs vying for market share. Changes in interest rates or a general economic slowdown could also affect the demand for credit among micro-businesses, which might pressure the company's growth targets. Additionally, as the company relies on technology and specific cluster-based underwriting models to assess borrowers, any disruption in these operational processes could pose challenges.
The key monitorable for shareholders will be the company’s ability to manage its loan book quality while maintaining its growth pace. Future quarterly reports will provide more clarity on how the company manages net interest margins and credit costs in different economic environments.