

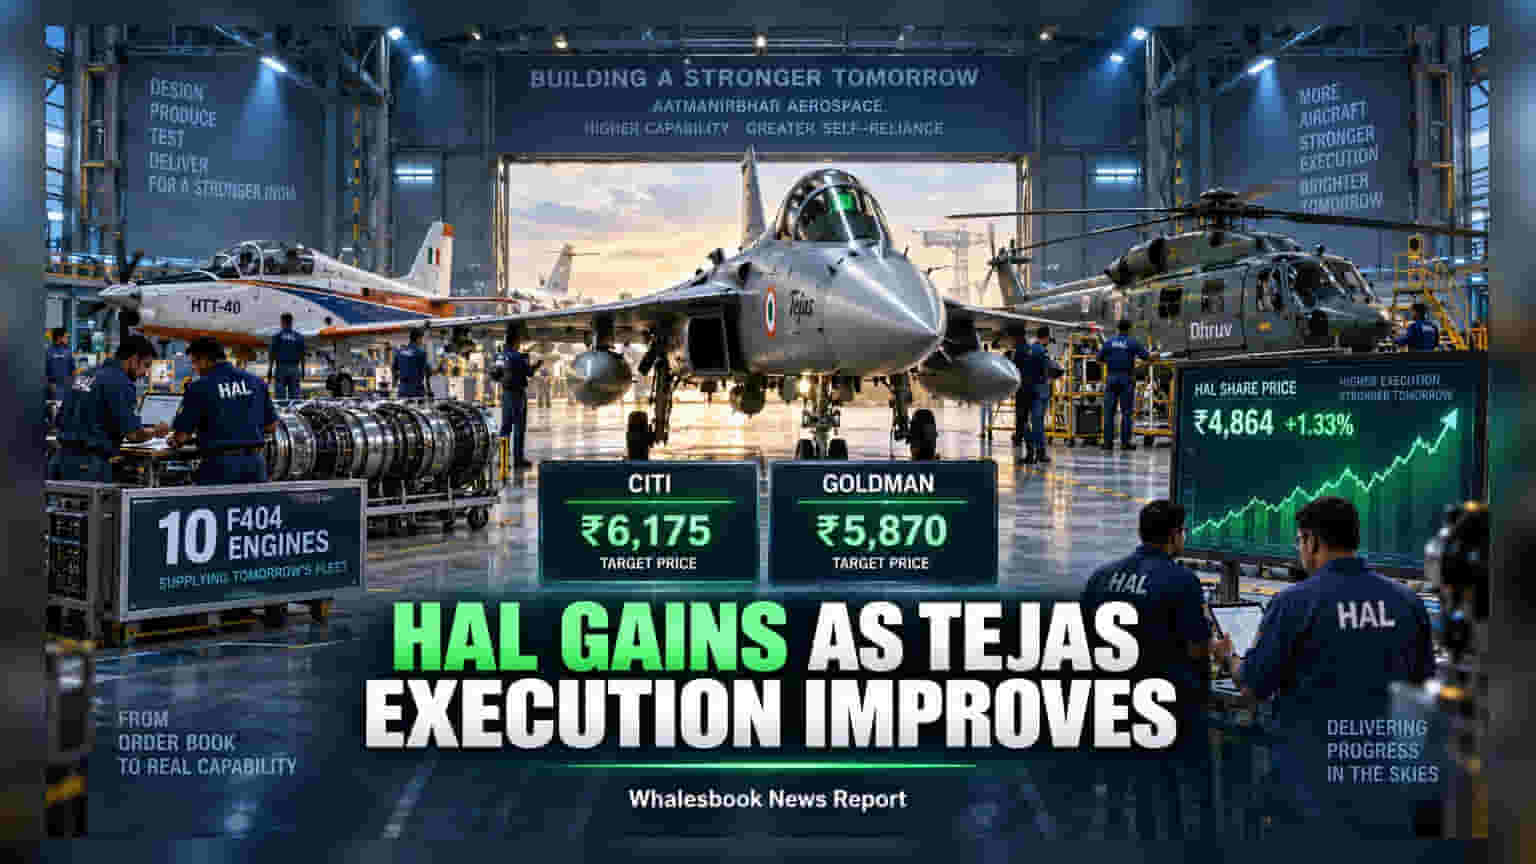
Hindustan Aeronautics Limited shares gained 1.33% to ₹4,864 following reports from Citi and Goldman Sachs on improved production of Tejas and Dhruv platforms. With the focus shifting to the delivery of the 180-aircraft LCA Mk-1A order, the company’s ability to manage engine supplies and sustain current delivery rates remains critical for future revenue growth.
Hindustan Aeronautics Limited (HAL) shares rose 1.33% to ₹4,864 in early trade, reflecting positive sentiment after major global brokerages reaffirmed their confidence in the company's manufacturing momentum. The recent handovers of key aircraft have shifted investor focus toward the company's ability to translate its massive defence order backlog into actual revenue, an area that has historically been the primary operational concern for the public sector enterprise.
The improved delivery visibility comes after HAL handed over the final two LCA Tejas FOC twin-seat trainers, three HTT-40 basic trainers, and four Dhruv Next Generation helicopters on September 18. By delivering across multiple programmes, the company is demonstrating that its manufacturing bottlenecks are easing, providing a clearer path for the execution of its larger contracts.
Engine Supply and Mk-1A Execution Targets
The central monitorable for investors remains the LCA Mk-1A programme, which involves a significant order for 180 aircraft. Management has set a delivery target of 10 aircraft by March 2027, making this timeline a critical indicator of the company's execution capability. Success in meeting these deadlines depends heavily on the supply of GE F404 engines, a key component that has faced potential constraints.
HAL has received 10 F404 engines so far, and the continuity of these supplies will largely dictate the pace of production. While the recent delivery of trainers and helicopters provides evidence of improving operational efficiency, the Mk-1A programme is significantly larger in scale and complexity. The company’s ability to maintain these production schedules while managing global supply chain dependencies will determine whether it can achieve its long-term revenue growth targets.
Stock Performance and Market Outlook
Brokerages have maintained their positive stance on the stock, with Citi keeping a target price of ₹6,175 and Goldman Sachs retaining a target of ₹5,870. This support comes as the stock has shown notable relative strength, rising 9.2% so far in 2026, even as the Nifty 50 has declined by 10.7% during the same period. This outperformance suggests that market expectations are already high, placing pressure on the company to sustain its current delivery trajectory.
Moving forward, investors will track three specific areas: the inflow of GE F404 engines, the speed of testing and final delivery of the Mk-1A units, and the overall pace at which the order book converts into quarterly profit. Since the company is heavily involved in government-led defence procurement, future revenue recognition will depend not just on order wins, but on the successful, timely commissioning of these complex aviation projects.