

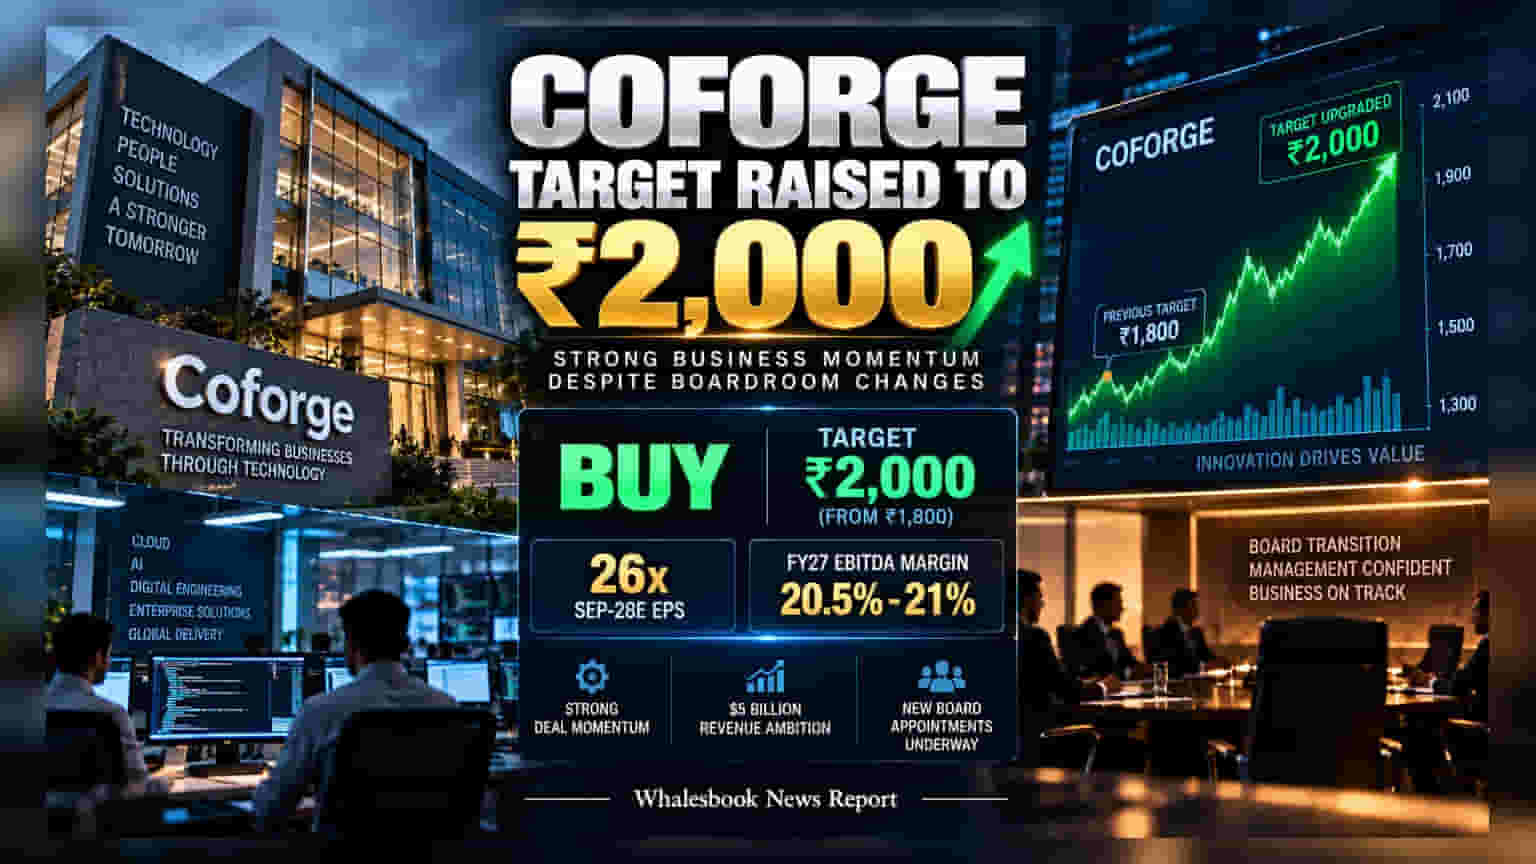
Emkay Global Financial has raised its target price for Coforge to ₹2,000, maintaining a positive view despite recent boardroom changes. The brokerage cited strong deal momentum and consistent financial guidance, even as the company addresses governance concerns raised by a recent internal audit. Investors should track how management handles the ongoing board search while maintaining operational focus.
Emkay Global Financial has raised its price target for Coforge to ₹2,000, suggesting confidence that the IT services provider's business performance remains insulated from recent governance challenges. The revision comes as the company navigates a transition following the departure of its Chairman, O.P. Bhatt, and independent director D.K. Singh earlier this month.
The board exits occurred after an internal audit conducted by KPMG revealed that certain board evaluation reports had been withheld. This raised questions among market observers about the company's internal governance and whether such issues could distract management or harm operations. However, the brokerage firm noted that company management and remaining board members have clarified that these developments do not impact the firm’s financial reporting or core business processes.
To fill the vacancies, the company has appointed Vivek Sharma as interim chairperson and engaged the executive search firm Egon Zehnder to recruit new independent directors. This move is seen as an effort to restore governance stability.
Despite the boardroom turbulence, the company has reaffirmed its financial guidance for FY27. Management continues to project an EBITDA margin—a key measure of operating profit—between 20.5% and 21%. Furthermore, the company maintains its long-term ambition of reaching $5 billion in revenue over the next four years.
Operational strength appears to be the primary reason for the bullish outlook from analysts. The company has indicated that the second quarter of FY27 is on track to be its strongest ever in terms of large-deal signings. If this momentum in securing high-value contracts continues, it could act as a buffer against negative sentiment surrounding the recent board exits.
For shareholders, the core narrative remains a tug-of-war between strong business performance and governance risks. The valuation increase to ₹2,000 reflects the view that the business side is currently outperforming the noise. Investors will need to monitor two specific areas: the successful appointment of new board members to close the governance gap and the actual conversion of these reported large deals into revenue. Any slowdown in deal execution or a delay in governance remediation could test the market's confidence in the current valuation.