

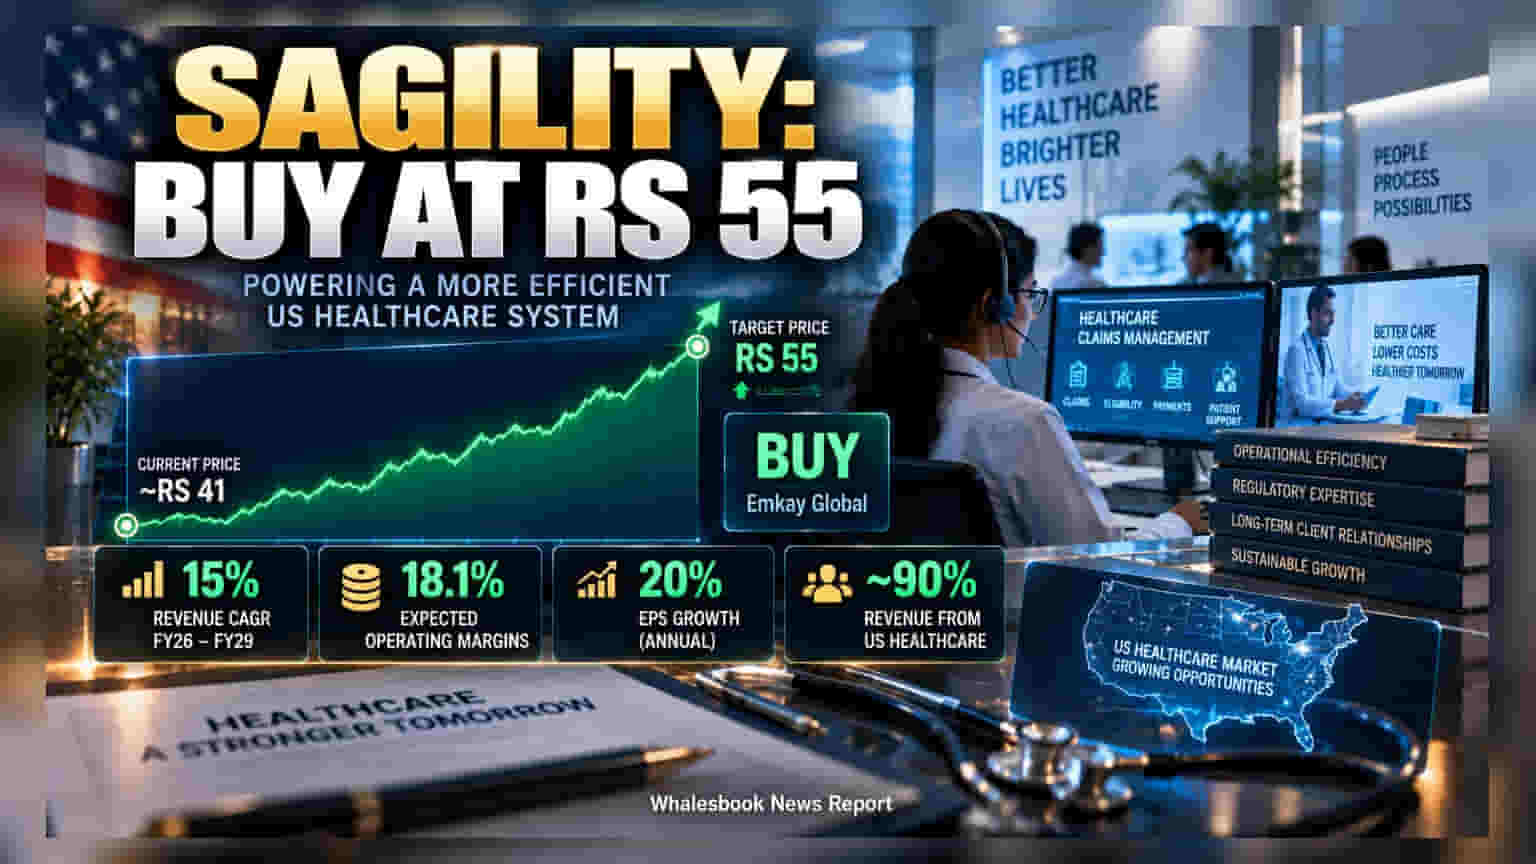
Emkay Global has started coverage on Sagility India with a Buy rating and a target price of Rs 55. The brokerage expects the company's healthcare services to grow by 15% annually through 2029, supported by steady demand from the US market. Investors should focus on how the company manages client relationships and competitive pricing.
Emkay Global Financial has begun tracking Sagility India with a Buy rating, setting a 12-month target price of Rs 55. The brokerage believes the company is well-placed to capture demand within the US healthcare market, which is currently facing rising operational costs and complex regulatory changes.
Sagility India provides specialized services for healthcare payers in the US. This area generates nearly 90% of the company's total revenue. Because the US healthcare system involves intricate rules and increasing expenses, service providers often rely on outsourcing partners to manage their operations efficiently. This creates a steady flow of income for the company, as it often holds long-term contracts with its clients.
The brokerage expects Sagility India to grow its revenue at an average rate of 15% annually between the 2026 and 2029 financial years. This growth is projected to come from winning more business from existing clients and expanding into new mid-market segments. Emkay Global also anticipates that operating margins, a measure of core profitability, could move toward 18.1%. If achieved, this is expected to drive earnings per share up by 20% annually over the same period.
However, there are risks investors should consider. A significant portion of the company’s business is tied to a limited set of large clients in the US. Any change in US healthcare policies or a loss of key contracts could hurt revenue. Furthermore, the healthcare services market is competitive, and companies often face pressure to lower prices to retain clients. Balancing the need for high-volume growth while maintaining these price points will be an important factor for the company's future performance.
The target price of Rs 55 is based on a valuation of 18 times the expected adjusted earnings for September 2028. Moving forward, the most important updates for shareholders will be the company's ability to maintain its client base, improve profit margins through operational efficiency, and navigate the pricing pressures common in the outsourcing industry.