

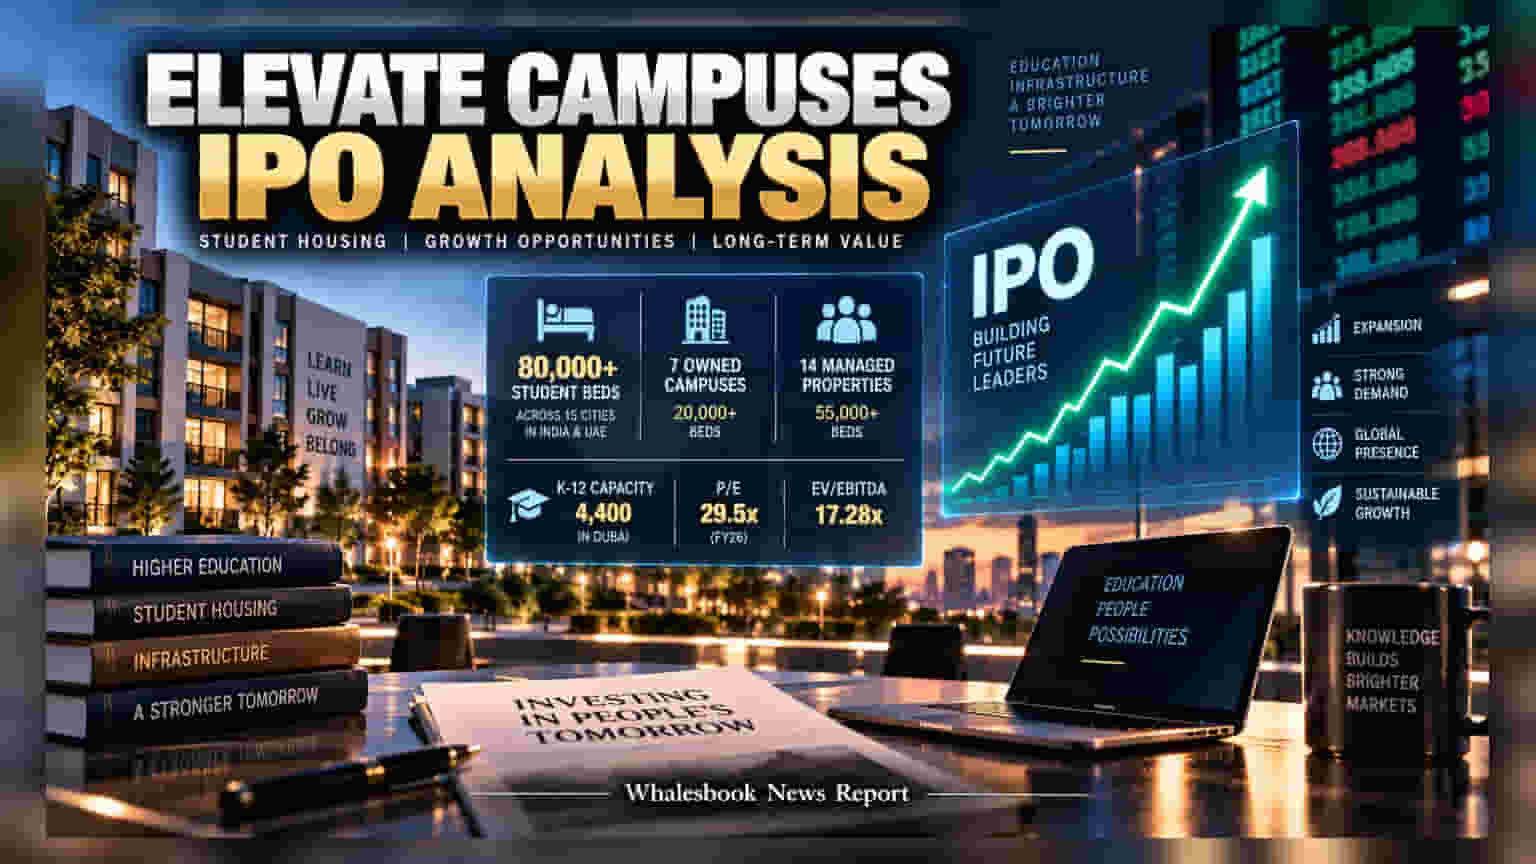
Elevate Campuses Limited has opened its IPO with a market valuation of ₹6,100 crore. Brokerage house Anand Rathi suggests a long-term subscription based on the company's footprint in student housing. The company operates a mix of owned and managed campuses across India and the UAE.
Elevate Campuses Limited has launched its Initial Public Offering (IPO), aiming to expand its footprint in the education infrastructure sector. With the upper price band set, the company’s post-issue market capitalization stands at approximately ₹6,100 crore. Brokerage firm Anand Rathi has issued a long-term subscription recommendation, noting the company’s established presence in student housing.
The company operates through a distinct business model that mixes owned and managed campuses. As of March 2026, the company manages a total capacity of over 80,000 student beds across 15 Indian cities and the UAE. Its operations are split between seven owned campuses with over 20,000 beds and 14 managed properties accounting for more than 55,000 beds. It also holds a K-12 student capacity of 4,400 in Dubai. This two-part approach allows the company to balance heavy-asset ownership with asset-light management contracts, which typically require less upfront capital.
From a financial perspective, the IPO is priced at a price-to-earnings (P/E) ratio of 29.5 times based on FY26 earnings. The enterprise value to EBITDA ratio, a common metric for evaluating capital-intensive businesses, is pegged at 17.28 times. Analysts suggest that these valuations reflect a fully priced issue, implying that investors are pricing in future growth expectations for the education infrastructure sector. Because of these valuations, the brokerage view emphasizes a long-term holding horizon rather than focusing on immediate short-term gains.
Investors evaluating this company should pay close attention to the difference between its owned and managed business segments. Owned campuses require significant ongoing spending on maintenance and capital improvements, which can impact cash flow if occupancy remains low. In contrast, the managed campus model relies on long-term contracts with educational institutions. Success in this segment depends on securing and retaining these institutional partnerships, which can be subject to competitive bidding.
Additional risks include the seasonal nature of the education business, where occupancy can fluctuate during breaks and academic transitions. Furthermore, operating across different geographies, including the UAE, introduces exposure to foreign regulatory and currency changes. The company’s ability to maintain healthy profit margins will depend on how efficiently it manages the high fixed costs associated with its owned campus portfolio while expanding its managed services. Investors should track the occupancy rates across these campuses and the company's success in signing new management contracts in upcoming quarters.