

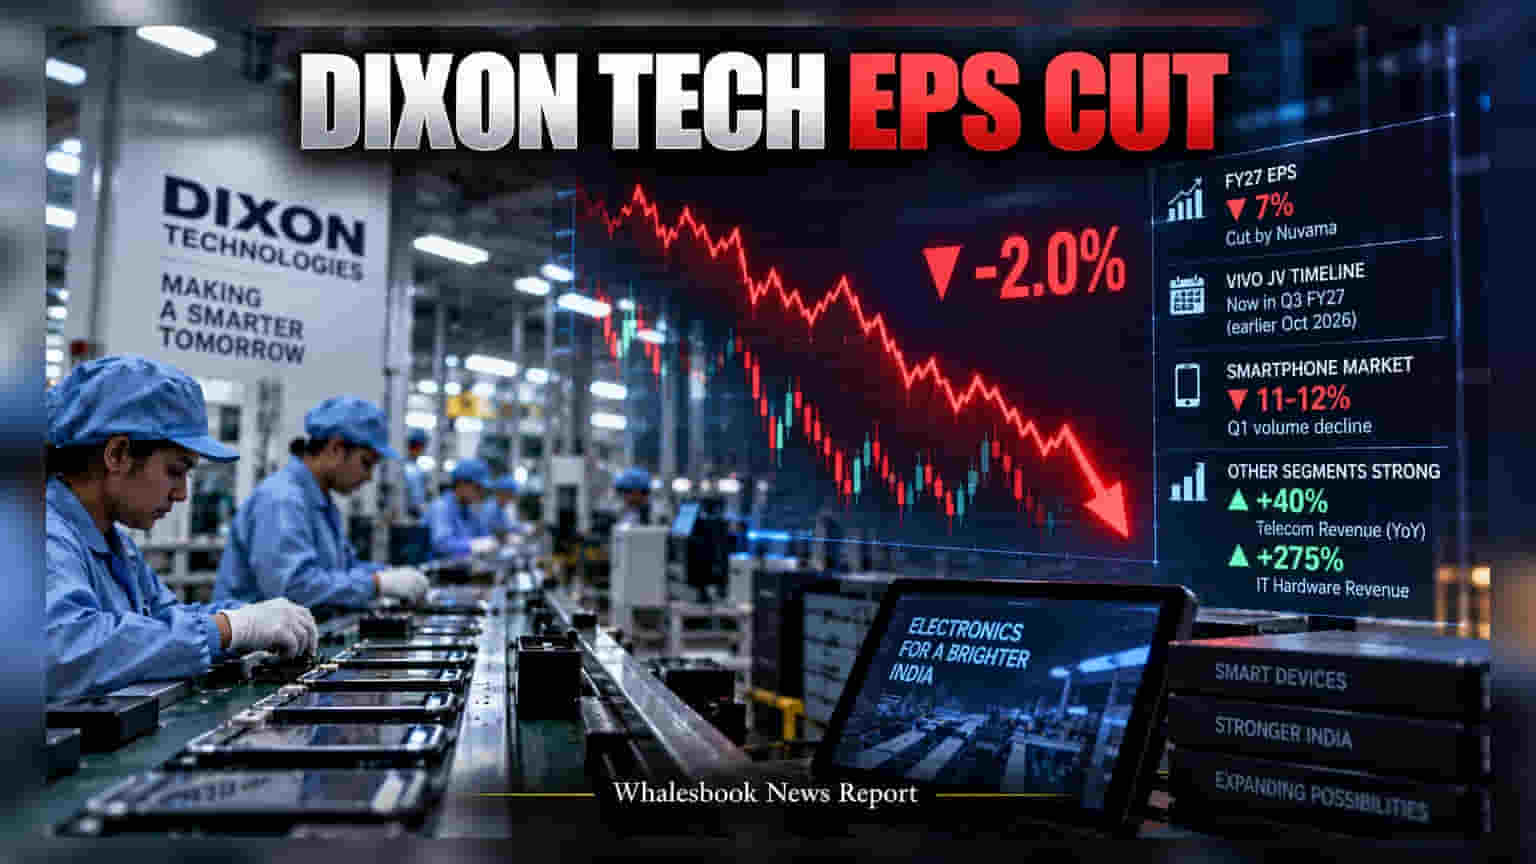
Shares of Dixon Technologies declined 2% on September 22 after brokerage Nuvama reduced its profit expectations for fiscal year 2027 by 7%. This revision follows a delay in the company's joint venture with Vivo and softer demand in the smartphone market. However, the brokerage raised its profit estimates for fiscal year 2028, citing potential for long-term growth through scaled-up component manufacturing.
Dixon Technologies shares fell by approximately 2% on September 22 as investors assessed a revised profit outlook for the company. Nuvama Institutional Equities lowered its profit-per-share forecast for the electronics manufacturer for fiscal year 2027 by 7%. This adjustment is primarily linked to a shift in the timeline for the company's joint venture with Vivo. The partnership, which was initially expected to start in October 2026, is now projected to begin in the third quarter of the 2027 fiscal year.
Smartphone Market Pressure
The brokerage pointed to persistent difficulties in the Indian smartphone sector as a key factor for the adjustment. The domestic market saw an 11-12% decline in volume during the first quarter, with expectations of a further 15-20% drop in the second quarter. Higher prices for memory chips have driven up the overall cost of handsets, which in turn has reduced demand, particularly in the mid-to-low price segments. While Dixon is expected to maintain its market position with projected volumes of 9.4 to 9.5 million units for the second quarter, the company is managing challenges related to export volumes and global pricing targets.
Growth in Other Segments
Despite the pressure in the smartphone division, the company continues to see strong performance in other key areas. Dixon's telecom business is expected to generate revenue between Rs 6,500 crore and Rs 7,000 crore, marking a 40% increase compared to last year. The IT hardware division is also showing significant momentum, with projected growth of 275%, pushing revenue beyond Rs 6,000 crore. Looking further ahead, Nuvama raised its profit forecast for fiscal year 2028 by 9%, anticipating that the company will successfully scale its component manufacturing business more quickly than previously expected.
Looking Ahead
For the current financial year, Dixon maintains a volume guidance of 33 million units, excluding the impact of the Vivo joint venture. As the company navigates the current market environment, investors will likely track the actual start date of the Vivo partnership and the recovery of export volumes. Management has indicated that export growth may pick up in the third quarter as new model approvals are processed and government incentive schemes provide support. The brokerage currently holds a 'Hold' rating on the stock with a target price of Rs 14,800, which reflects a balance between the current short-term demand concerns and the potential for long-term expansion in the IT and telecom hardware sectors.