

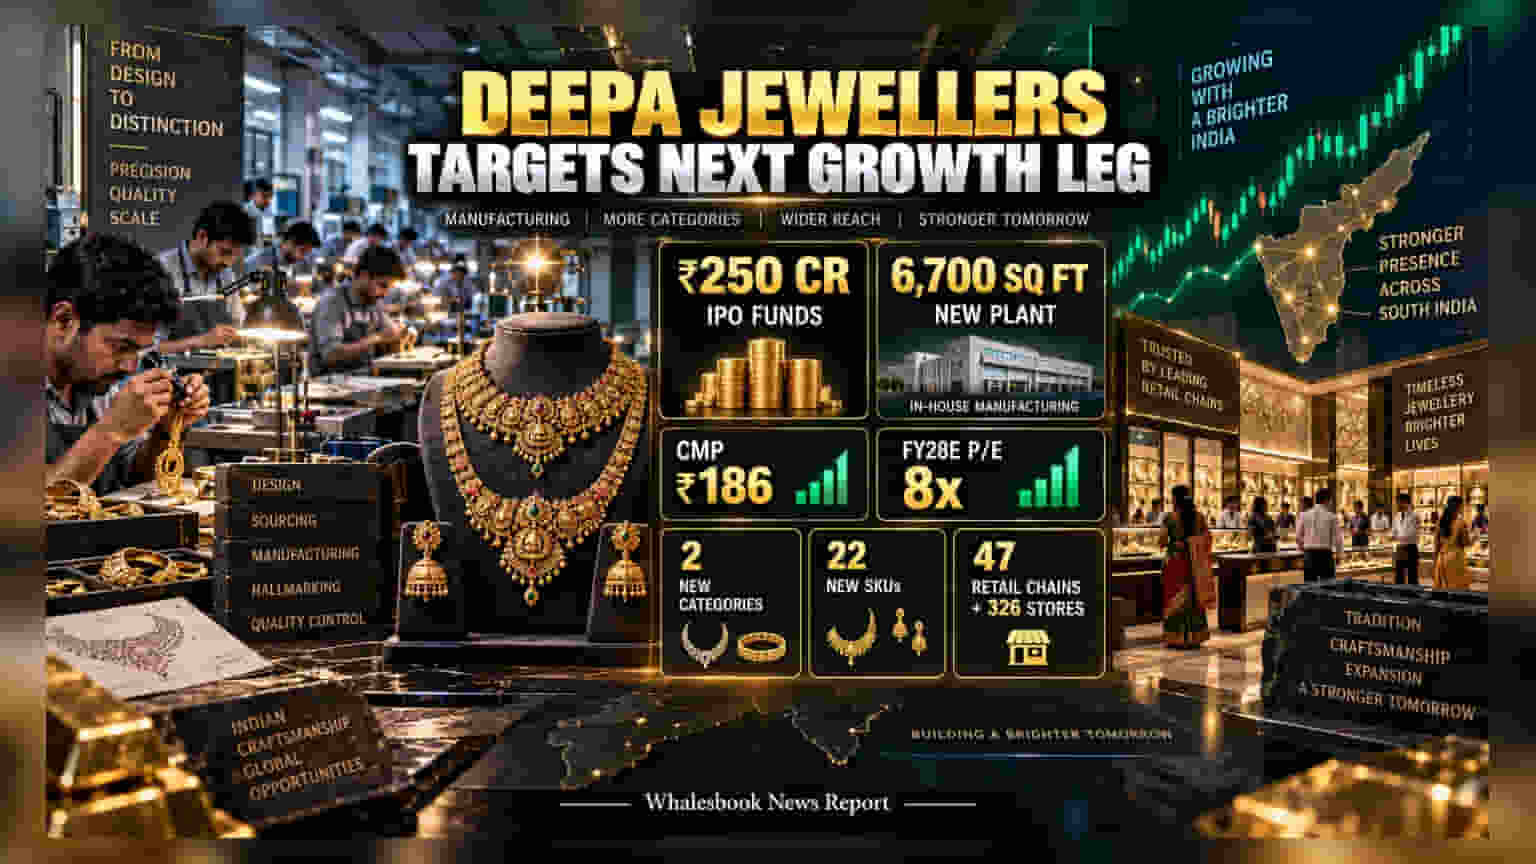
Deepa Jewellers, which recently listed on the stock exchanges, is utilizing a portion of its ₹250 crore fresh IPO proceeds to set up a new manufacturing facility in Hyderabad. This move aims to bring production in-house and improve margins. While expansion is underway, investors should be aware of the company's high reliance on a small group of large clients and its regional concentration in South India.
Deepa Jewellers, which listed on the stock exchanges on September 8, 2026, is now shifting focus toward executing its growth plans. The Hyderabad-based company is using a portion of the ₹250 crore fresh capital raised during its recent initial public offering to open a new 6,700-square-foot in-house manufacturing facility. The company's total IPO size was ₹459.72 crore, which included the ₹250 crore fresh issue and an offer for sale.
Historically, the company has operated using an outsourced model, where external artisans, known as karigars, handle the manufacturing process while the company manages product design, gold sourcing, hallmarking, and quality checks. By establishing this new facility, the company intends to capture a portion of the manufacturing margins that were previously paid to third parties and gain tighter control over its production schedules and quality standards. This is a significant operational shift as the firm continues to scale, with plans to introduce 22 additional stock-keeping units, including specialized nakshi kundan jewellery.
From a financial perspective, the IPO proceeds have strengthened the balance sheet. The infusion of fresh capital is expected to reduce the company's debt-to-equity ratio, offering more financial flexibility to support working capital needs. For the 2026 financial year, the company reported revenue of ₹1,926.7 crore and a profit of ₹104.8 crore. However, as the company scales its operations, effective working capital management will be a critical factor in maintaining cash flow health.
Investors should also consider the specific risks inherent in the company's business model. A primary concern is customer concentration; in the 2026 financial year, the top 10 customers accounted for approximately 64.67% of total revenue. This means the company is highly dependent on a small number of retail chains and standalone stores. If any major retail client faces a business slowdown or shifts its sourcing strategy, it could have a direct and material impact on the company's financials. Furthermore, the company’s operations are heavily concentrated in Southern India, making it vulnerable to any region-specific economic slowdowns or shifts in local consumer demand.
Additionally, the business is exposed to the volatility of gold and diamond prices. Since the company deals with precious metals, any sharp movement in global commodity prices can affect its profit margins. As the company moves from an outsourced model to an in-house manufacturing process, it will also face the execution risk of ramping up the new facility successfully and integrating it into the existing supply chain. Moving forward, the most important updates for investors will be the operational progress of the new Hyderabad plant and the company's ability to diversify its client base beyond its current large-chain partners.