

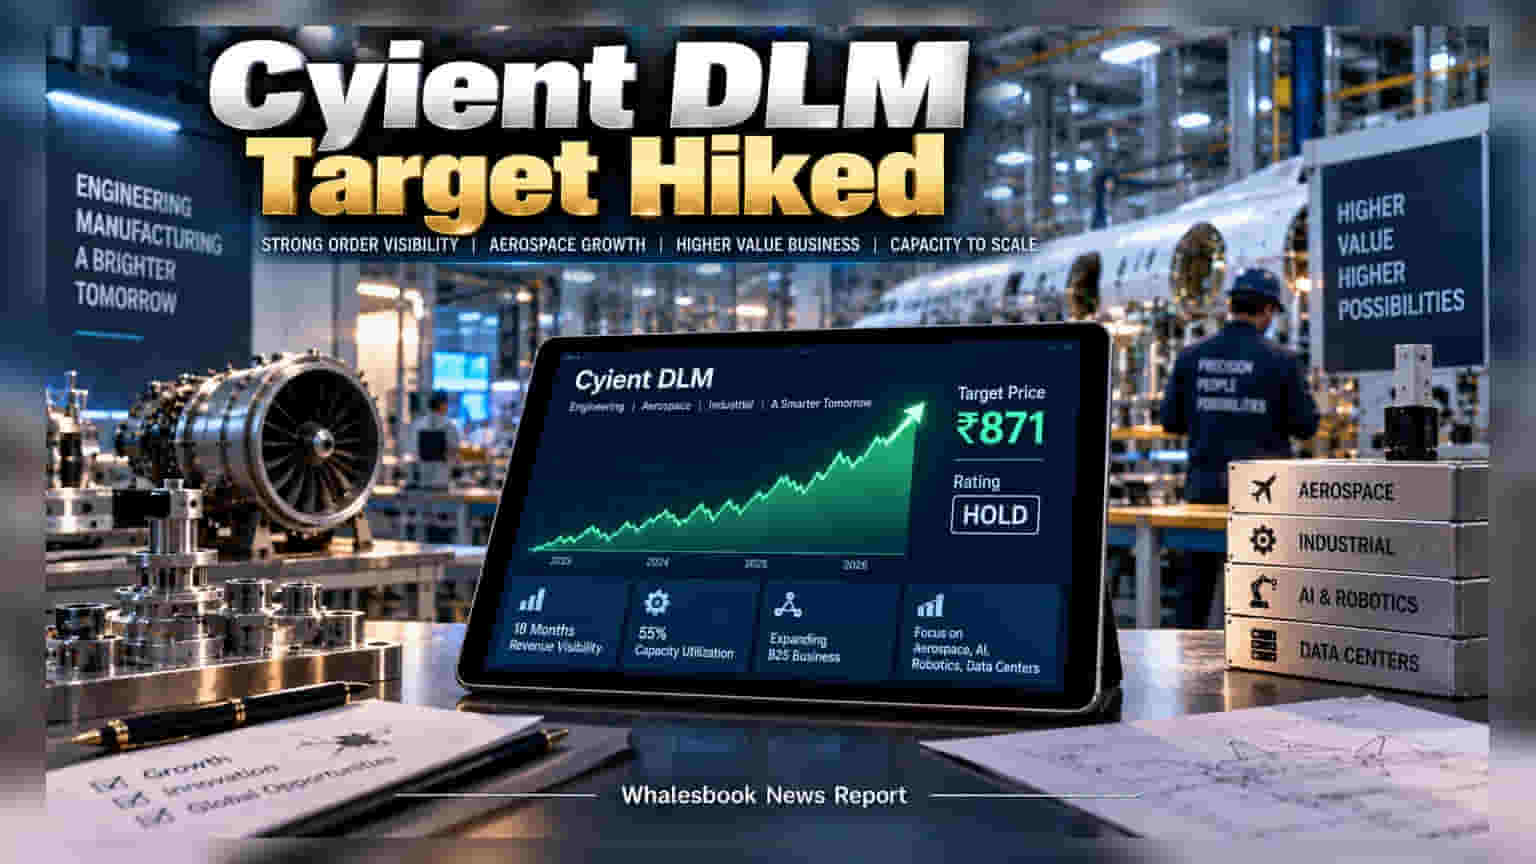
Brokerage firm Prabhudas Lilladher has maintained a 'Hold' rating on Cyient DLM while raising its price target to ₹871. The report highlights strong order visibility and a strategic shift toward higher-value aerospace and industrial products. Investors will watch how effectively the company manages its current capacity and commercializes new client programs.
Prabhudas Lilladher has updated its outlook on Cyient DLM, keeping a 'Hold' rating while increasing the price target to ₹871. This update follows a visit to the company’s manufacturing facilities, where analysts noted strong order visibility in the aerospace and industrial sectors. The company’s current order pipeline provides roughly 18 months of revenue visibility, with long-term programs extending for up to two years. A key takeaway for investors is that the company is currently using about 55% of its available manufacturing capacity. This means it can likely support higher revenue levels without needing large amounts of new money for expansion in the near term. This operational flexibility allows the company to focus on scaling up its existing infrastructure to support future growth.
Cyient DLM is actively shifting its focus toward annuity-based business models, particularly within its aerospace and industrial segments. The company is expanding its Build-to-Specification (B2S) business, where it expects to see revenue share reach double digits by fiscal year 2028. This move is significant because B2S is generally a higher-value service compared to standard assembly, aiming to capture demand in areas such as artificial intelligence, robotics, and data center hardware. By moving toward these more complex products, the company aims to move up the value chain.
Financial projections for the coming years suggest growth in revenue, operating profit, and net profit. The brokerage projects a 120-basis-point expansion in EBITDA margins over this period. While the long-term outlook appears positive, the company’s success will depend on how quickly it can turn new client leads into commercialized projects. Scaling operations efficiently remains a key factor for maintaining and improving profit margins. Investors should track the company’s ability to execute on its current order book and manage the transition toward more complex, higher-value product offerings. The speed at which it converts new programs into active revenue will be a crucial indicator of its future operational and financial performance.