

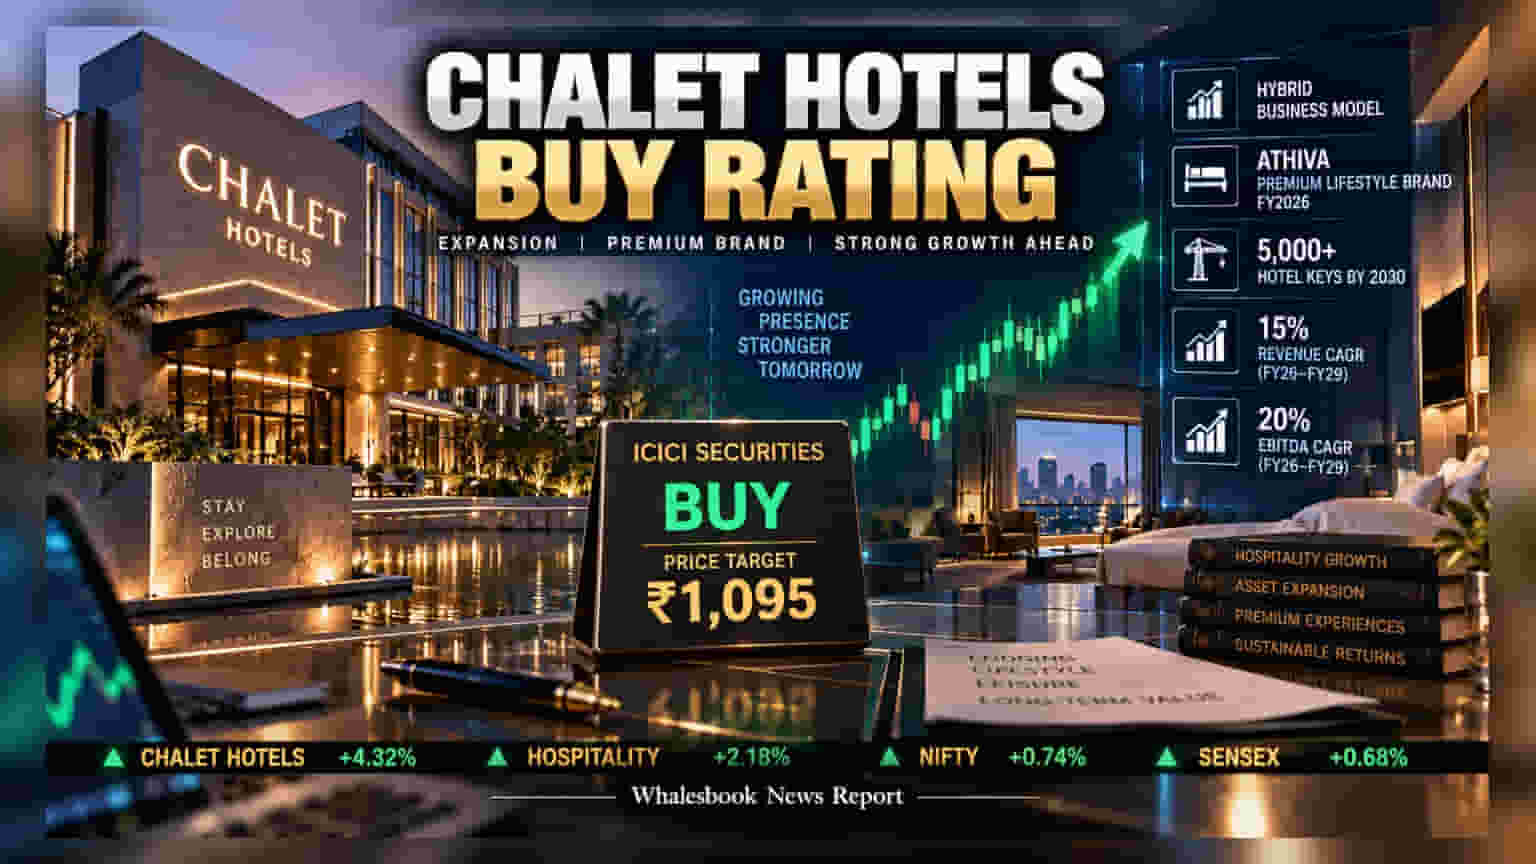
ICICI Securities has maintained a 'Buy' rating on Chalet Hotels with a target price of Rs 1,095. The brokerage cited the company's aggressive expansion to 5,000 keys by 2030 and its shift to a hybrid business model. Investors should monitor if the planned Rs 30 billion capital expenditure influences the company's debt levels or cash flow in the coming years.
ICICI Securities recently released a report maintaining a 'Buy' rating on Chalet Hotels, setting a price target of Rs 1,095. The brokerage firm noted that the company is moving toward a hybrid business model, which combines owning hotel assets with managing properties, as opposed to relying solely on ownership. This shift aims to improve the company's reach and operational flexibility.
A key part of this strategy is the upcoming launch of 'Athiva,' a premium lifestyle brand scheduled for the fiscal year 2026. By introducing this brand, the company aims to target a wider group of travelers, potentially moving beyond its traditional luxury and business segments. This comes as the company plans to increase its total portfolio capacity to more than 5,000 hotel keys by March 2030, which involves adding 1,655 new keys.
The expansion is capital-intensive, with Chalet Hotels planning to spend Rs 30 billion on projects between 2026 and 2029. Analysts from ICICI Securities expect this investment, alongside stable leasing income, to support an annual revenue growth of 15% and an EBITDA growth of 20% between fiscal years 2026 and 2029. The brokerage further projects that the company will generate post-interest operating cash flow of over Rs 10 billion annually starting from fiscal year 2027.
While these targets signal significant growth, investors should remain aware of the risks inherent in the hospitality sector. The hotel business is cyclical, meaning that occupancy and room rates depend heavily on general economic conditions, tourism trends, and business travel demand. Furthermore, an aggressive expansion plan involving Rs 30 billion in spending carries execution risks, such as potential delays in project commissioning or cost overruns, which could strain the company's balance sheet if not managed carefully. Competitors in the Indian hospitality space, such as Indian Hotels Company (IHCL), EIH, and Lemon Tree Hotels, are also expanding, which may increase pressure on pricing and market share in the premium segment.
For investors, the most important updates to track will be the timely execution of these new hotel projects and the company's ability to maintain healthy profit margins during this high-spending phase. Additionally, monitoring the company’s debt levels as it incurs the planned Rs 30 billion expenditure will be essential, as high debt can impact future profitability if hotel demand does not grow as expected.