

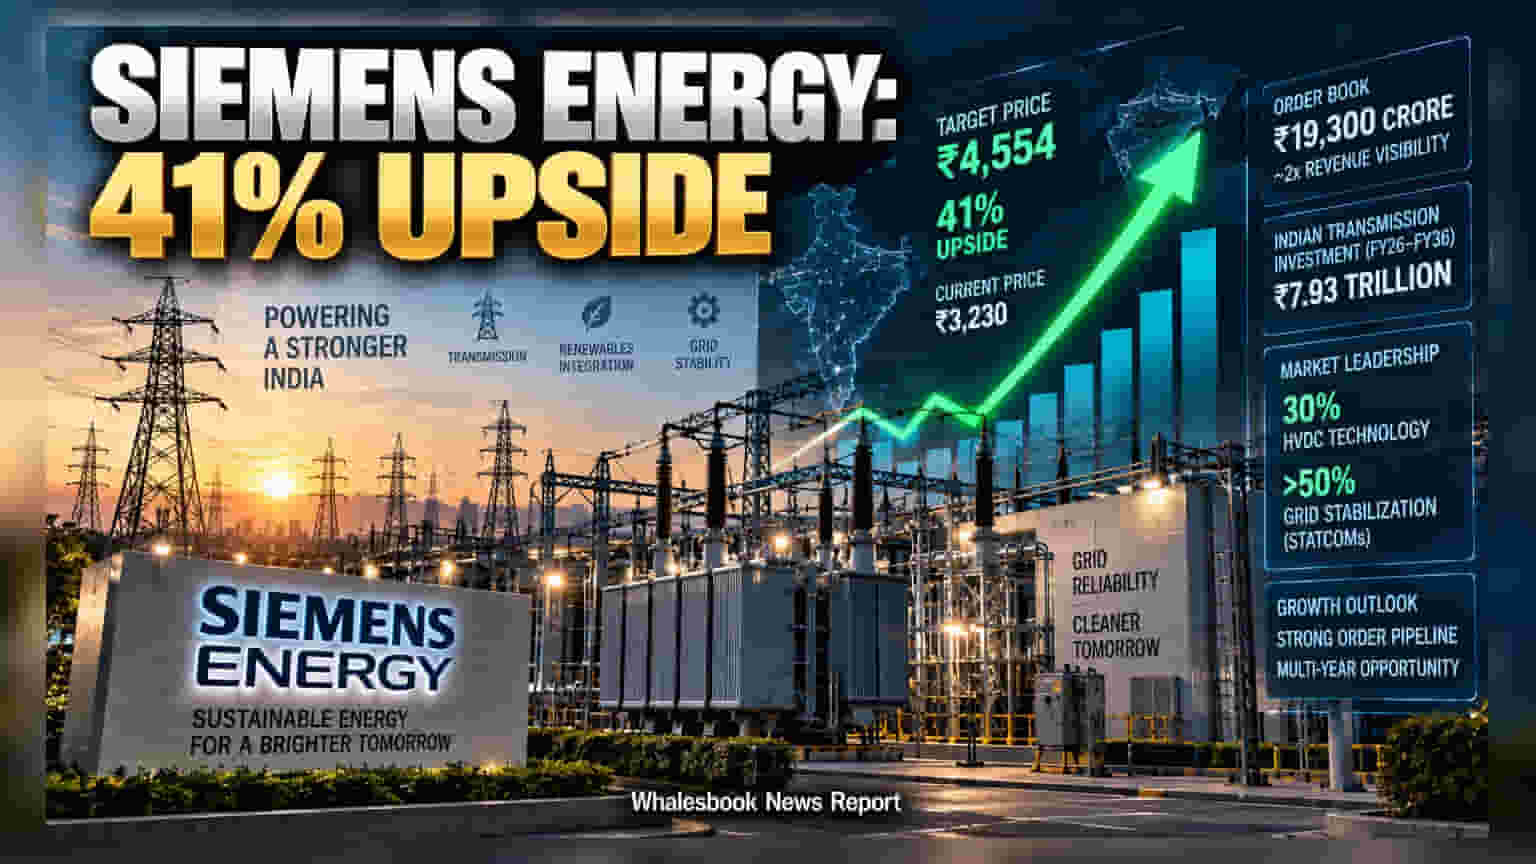
Brokerage firm DRChoksey has initiated coverage on Siemens Energy with a target price of ₹4,554. The report highlights the company's strong market position in India's power transmission sector and a robust order book of ₹19,300 crore as key growth drivers.
Brokerage firm DRChoksey has initiated research coverage on Siemens Energy, setting a price target of ₹4,554. This reflects a potential 41% upside from the company's recent trading level of ₹3,230. The report focuses on the firm’s expected role in the multi-year infrastructure growth cycle within India's power transmission business.
The brokerage anticipates a steady growth trajectory for the company, with three-year compound annual growth rate projections showing increases across revenue, EBITDA, and profit after tax. This outlook is supported by a solid order book of ₹19,300 crore, which offers about two times revenue visibility. The firm suggests that the company is well-placed to benefit from the broader capital expenditure cycle in the power sector.
India’s transmission infrastructure is set for significant investment, with industry estimates projecting a need for ₹7.93 trillion between FY26 and FY36. As industrial electrification accelerates and the integration of renewable energy becomes a priority, demand for grid components like transformers, switchgear, and substations is expected to rise. The company maintains a strong competitive presence, with an estimated 30% market share in high-voltage direct current (HVDC) technology and over 50% of the market share in grid-stabilization solutions, such as STATCOMs.
Regarding valuation, the stock is currently trading at approximately 43x its estimated FY28 earnings. The brokerage notes that this appears attractive when compared to some peers in the sector, which command multiples closer to 60x. The price target of ₹4,554 is based on applying a 60x price-to-earnings multiple to the projected FY28 earnings per share of ₹75.90. The brokerage also noted that this model is conservative, as it does not fully include potential revenue from upcoming nuclear energy contracts or additional HVDC projects, which could serve as potential upside.
For investors, the next important updates to monitor will be the company's progress on executing its existing order book and its ability to maintain its market share as the sector continues to evolve. Financial performance in the coming quarters, particularly the conversion of the order book into revenue, will be critical to tracking whether these growth projections remain on track.