

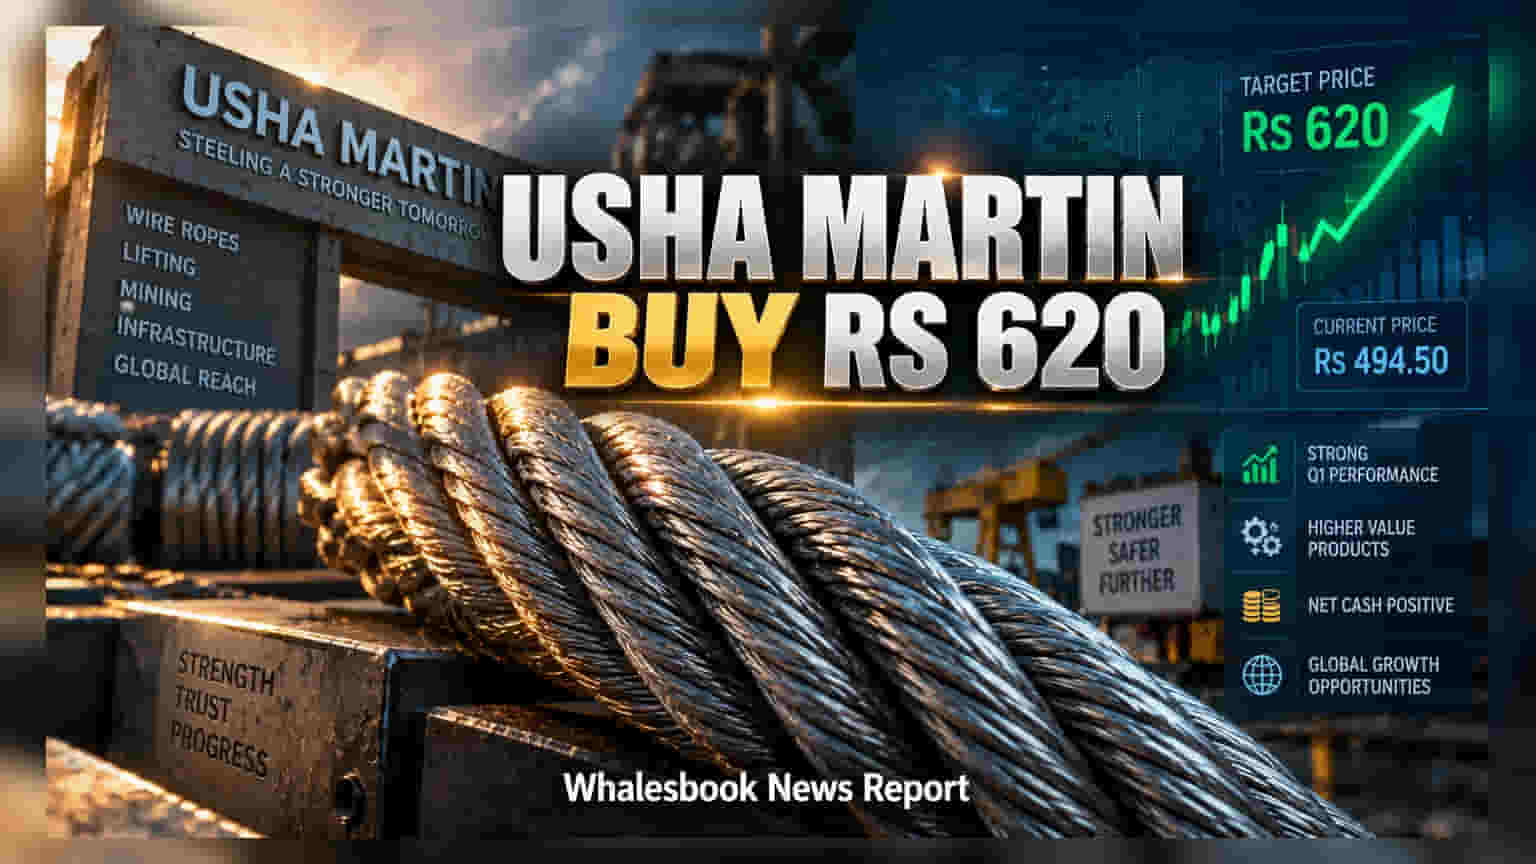
Brokerage firm Anand Rathi has started coverage on Usha Martin with a price target of Rs 620. The specialty steel wire rope maker recently reported a 40.9% jump in quarterly profit, aided by its shift toward high-margin products. Investors are tracking its debt-free financial status and ongoing global market expansion.
Anand Rathi has initiated coverage on Usha Martin, the specialty steel wire rope manufacturer, with a price target of Rs 620 per share. As of September 11, 2026, the company's stock was trading at approximately Rs 494.50, reflecting market interest in the firm's recent financial turnaround and strategic business shifts.
Strong Financial Performance
Usha Martin demonstrated a solid performance in the first quarter of the 2027 fiscal year. The company reported a revenue of Rs 1,033 crore, representing a 16.4% growth compared to the same period in the previous year. Even more notable was the rise in profitability, with the net profit climbing by 40.9% to Rs 142 crore. This improvement is largely attributed to better operational efficiency, with the company's operating profit margin expanding to 20.1% in the first quarter, up from 16.3% in the corresponding period of fiscal year 2026.
Strategic Pivot and Financial Health
A central part of the company's growth plan has been a transition toward higher-value products, such as specialty steel wire ropes. This segment now accounts for a significant portion of the total revenue, helping the company improve its profitability per tonne.
Financially, Usha Martin has strengthened its balance sheet considerably. The company has moved to a net cash-positive position, with cash reserves of approximately Rs 465 crore. This shift from debt to a net cash status has been recognized by credit rating agencies, with India Ratings and Research upgrading the company's long-term credit rating to IND AA-/Stable.
Key Risks and Challenges
While the company has shown improvements, investors should also consider the external risks that could impact future operations. The specialty steel sector is susceptible to global trade uncertainties and geopolitical conflicts, which can disrupt logistics and supply chains. Additionally, the company faces exposure to volatility in raw material and freight costs, which are essential inputs for manufacturing. Any sudden spike in these costs could put pressure on the operating profit margins the company has worked to expand. Furthermore, the company’s performance is partially dependent on demand volumes in the Middle Eastern market, where fluctuations can impact the overall sales growth.
Next Steps for Investors
Moving forward, the primary focus for the company will be maintaining its margin profile as it attempts to penetrate deeper into global markets. Investors may look for updates on how the company manages raw material cost cycles and whether it can successfully scale its high-value product offerings. The company’s ability to sustain its net cash position while pursuing growth will also be a key factor to monitor in coming quarterly filings.