

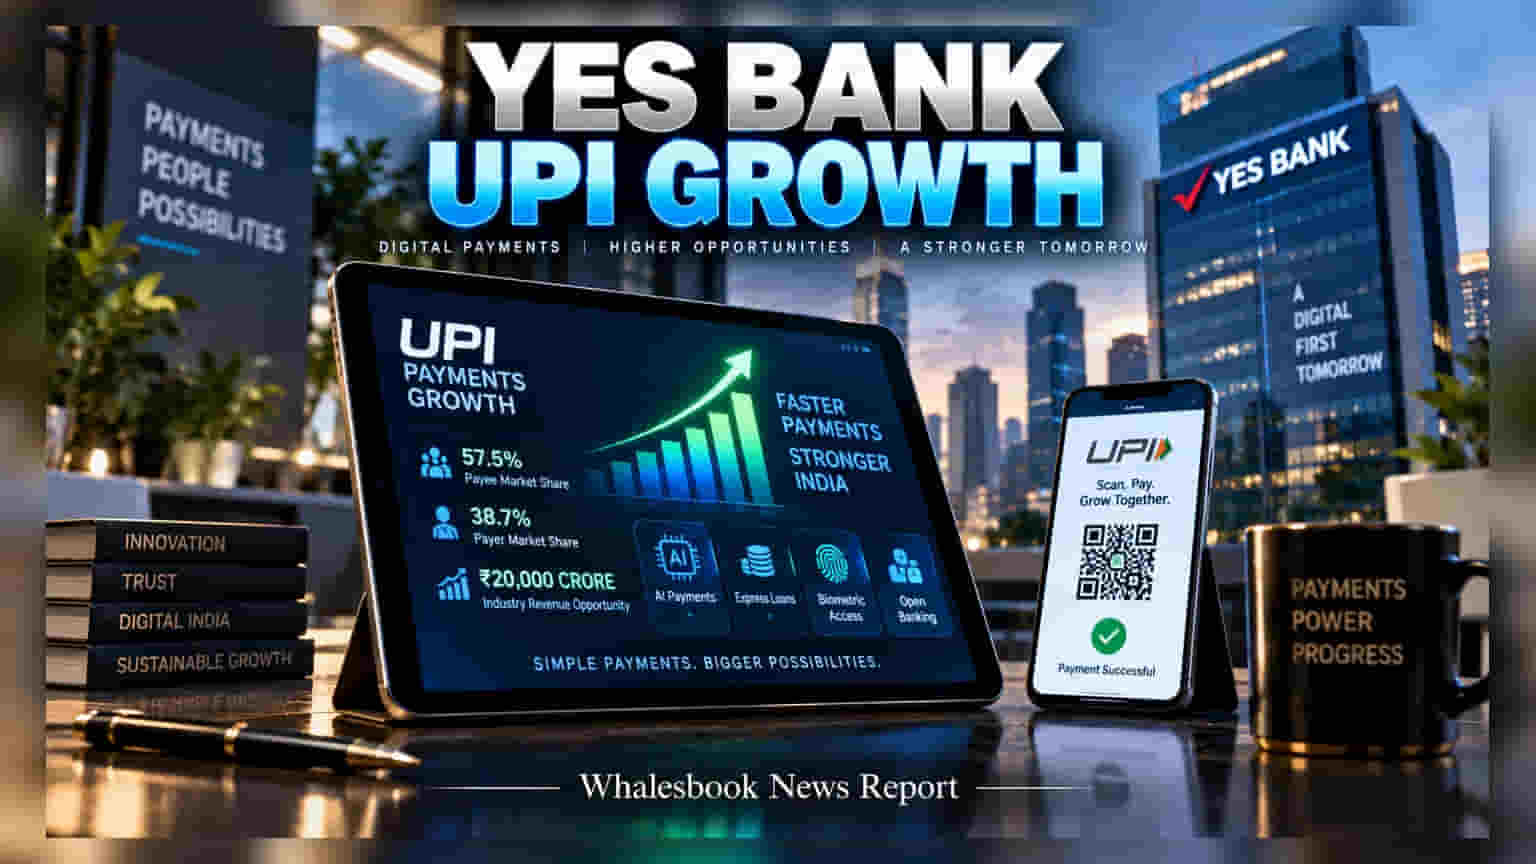
Starting October 15, UPI transactions above ₹2,000 will attract a 0.4% fee, creating a new income source for banks. YES Bank, which holds a significant share of UPI processing, plans to monetize this traffic. The lender is shifting focus from just transaction volume to higher-value services like AI-driven payments and express loans to improve its financial health.
The Indian digital payments landscape is set for a change starting October 15, as a 0.4% fee applies to person-to-merchant UPI transactions exceeding ₹2,000. While the vast majority of small transactions remain free for users and merchants, this new fee structure creates a fresh revenue opportunity for banks that process high volumes of digital payments. YES Bank is positioning itself to capture this benefit by leveraging its established presence in the digital payment ecosystem.
Leveraging UPI Market Leadership
YES Bank has built a significant footprint in the UPI space over the years. Currently, the lender manages 57.5% of payee payment services and 38.7% of payer payment services. Because it handles such a large portion of the nation's digital traffic, the bank is well-placed to generate income from the new fee structure. The shift allows the bank to move away from purely chasing volume and toward monetizing the traffic it already processes.
Industry analysts estimate that the total annual revenue pool for the banking sector from this shift could reach up to ₹20,000 crore, with a significant portion expected to be shared among participating banks. For YES Bank, the goal is to transform this high-volume business into a sustainable source of profit.
Strategic Pivot to Value-Added Services
The bank is evolving its strategy beyond simple payment processing. Management has indicated plans to introduce advanced services, such as agentic AI-powered payments, express loans, and biometric-authorized transactions. By integrating open-banking solutions and partnering with fintech companies, the bank aims to offer these high-value services without needing to spend heavily on building proprietary technology from scratch. This approach is intended to help the bank improve its margins while keeping capital spending under control.
Risk and Historical Context
Investors looking at the bank’s digital journey should also note the historical context. The bank faced significant challenges during a moratorium in 2020, yet it managed to retain a 42% share of UPI traffic during that period, demonstrating resilience in its digital operations. As the bank shifts toward complex services like express loans and AI payments, the challenge will be maintaining high cybersecurity and fraud prevention standards. The increased complexity of services means the cost of managing fraud and data security will become a key monitorable for the bank's profitability.
The next phase for the bank will be executing these high-value offerings without disrupting its core payment services. Shareholders and observers will likely watch whether the new fee revenue effectively boosts the bank's bottom line in the coming quarters and if it can successfully scale these new services against competitors in the crowded Indian banking market.