

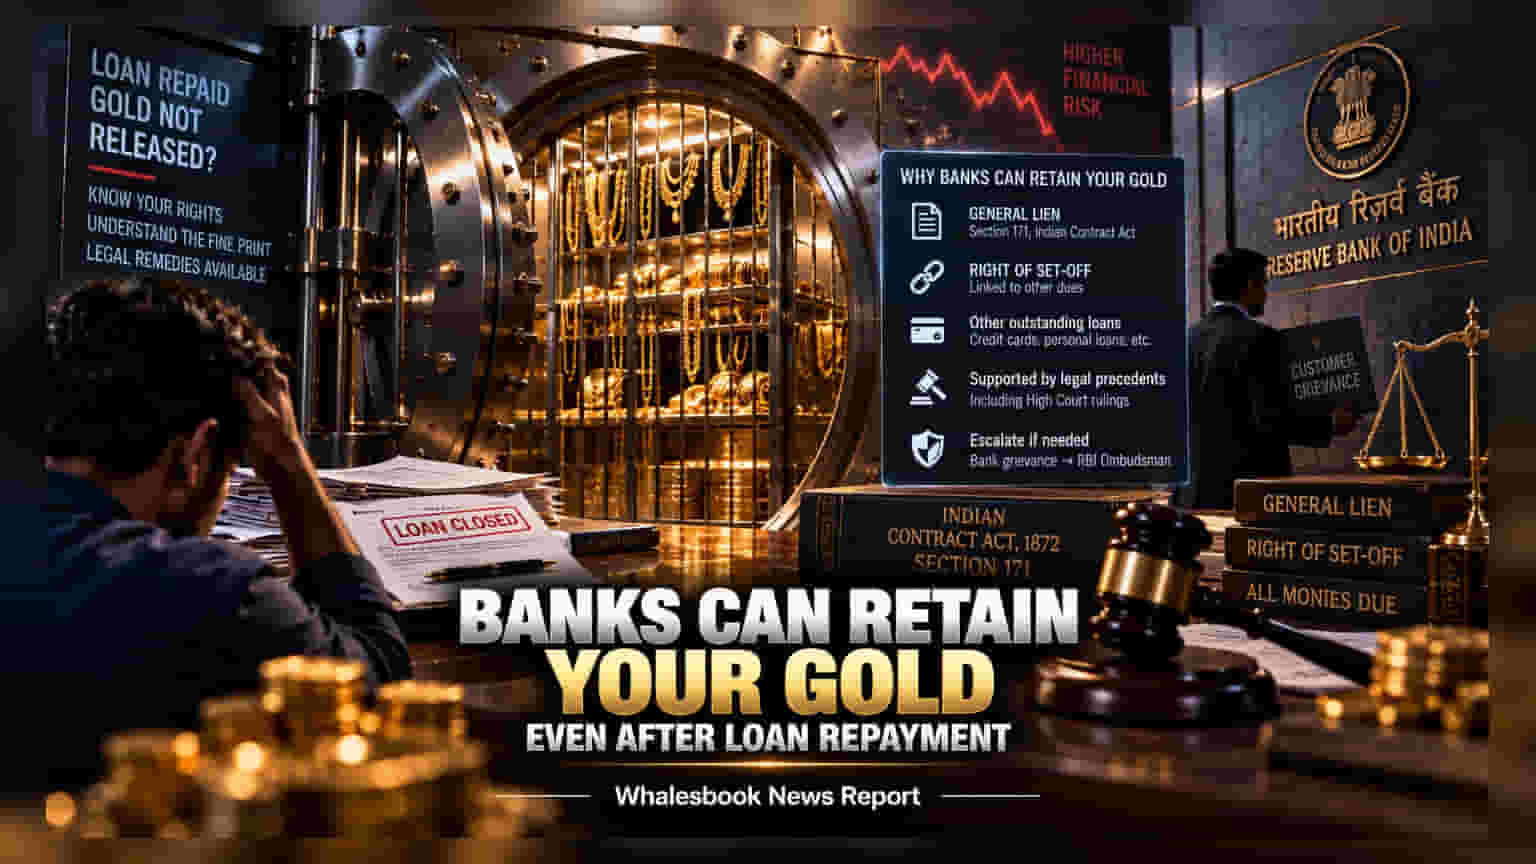
Paying off a gold loan does not always guarantee the immediate release of your jewelry. Banks can legally hold pledged gold as security for other unpaid debts under a 'general lien.' Borrowers should check loan agreements for 'right of set-off' clauses before signing to avoid unexpected complications when the loan term ends.
Many borrowers assume that once they repay their gold loan, the bank will automatically release their jewelry. However, this is not always the case. Banks can legally retain pledged assets even after a specific loan is closed, depending on the terms of the loan agreement signed at the start.
Understanding the Banker's Lien
The legal basis for this practice is Section 171 of the Indian Contract Act, 1872. This section grants banks a 'general lien,' which gives them the right to retain assets held in their possession against other outstanding debts. This means that if a borrower has multiple credit facilities with the same bank, or has acted as a guarantor for another person’s loan at that institution, the bank may hold the gold as security for those other liabilities.
The 'Right of Set-Off' Clause
When applying for a loan, the fine print often contains clauses such as 'right of set-off,' 'general lien,' or 'all monies due.' These terms authorize the bank to link all of a borrower's accounts together. If a borrower has an unpaid credit card bill, a personal loan, or any other pending due with the same bank, the lender may refuse to return the pledged gold until all those obligations are settled. Legal precedents, including rulings related to the Andhra Pradesh High Court, have supported the right of banks to exercise this lien when financial liabilities are interconnected.
What Borrowers Should Check
To avoid surprises, borrowers must read the loan application form carefully before signing. Look for clauses that link the security to other liabilities or existing credit accounts. The goal is to understand whether the gold is being pledged only for the specific loan being taken or if the agreement covers all past, present, and future dues with that bank.
If a bank refuses to release your jewelry after you have fully repaid the specific loan, the first step is to formally request written documentation. Ask the bank to identify the exact legal clause or the specific outstanding debt that justifies the retention of your asset. If the bank fails to provide a satisfactory explanation, borrowers can escalate the issue through the bank's internal grievance redressal mechanism. If the matter remains unresolved after 30 days, the Reserve Bank of India (RBI) Integrated Ombudsman Scheme serves as the next channel for relief. Throughout this process, it is essential to keep all original loan closure statements, payment receipts, and copies of correspondence for any potential regulatory or legal follow-up.