

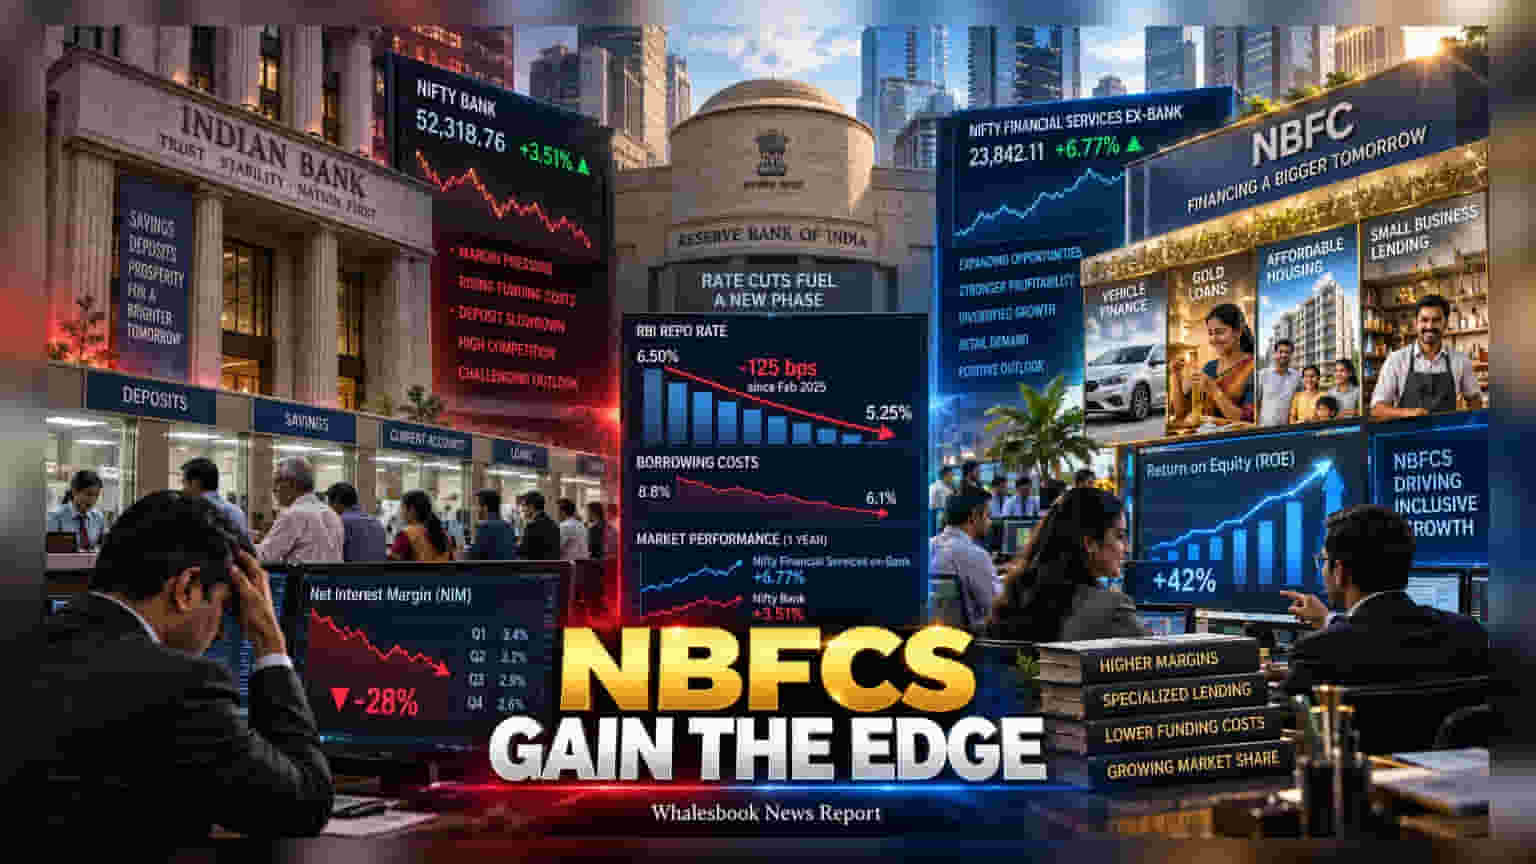
Investors are increasingly favoring NBFCs as rate cuts and niche lending strategies improve margins, while banks navigate slower deposit growth. With the repo rate falling 125 basis points since February 2025, non-bank lenders are showing stronger resilience, though banks remain important for their asset quality.
The Indian financial sector is witnessing a distinct shift in investor preference, with Non-Banking Financial Companies (NBFCs) gaining traction over traditional banks. Recent market data shows that the Nifty Financial Services ex-Bank index climbed 6.77% over the past year, outperforming the Nifty Bank index, which rose by 3.51%. This divergence highlights how different business models are reacting to the current interest rate cycle.
The Impact of Falling Rates on Margins
The Reserve Bank of India has lowered the repo rate by 125 basis points since February 2025. This move has created a lopsided impact on profitability. A large portion of bank loan portfolios is directly linked to floating policy rates, meaning lending yields fall almost immediately when rates drop. However, the cost of funds for banks—largely driven by customer deposits—does not adjust as quickly because these deposits are locked in for fixed tenures, often ranging from six to twelve months.
This gap creates a temporary squeeze on bank margins. In contrast, many NBFCs operate with a different structural setup. A significant part of their loan books, particularly in vehicle, gold, and small-business lending, is provided at fixed interest rates. As market interest rates decline, their borrowing costs decrease while their existing loan yields remain higher for longer, helping protect their profit margins.
Changing Savings Patterns
Banks have historically relied on low-cost household deposits to fund their lending operations. This advantage is now facing pressure as household savings patterns shift away from traditional bank deposits. According to the Economic Survey 2025-26, the share of household savings held in bank deposits has dropped from 57.9% in the 2012 fiscal year to 35.2% in the 2025 fiscal year. As this pool of cheap capital shrinks, banks are forced to rely more on market-linked funding sources like bonds and certificates of deposit, which are typically more expensive and volatile.
Niche Lending vs Scale
While banks have recorded higher overall credit growth, much of that expansion has been driven by large industrial borrowers and financing provided to NBFCs, where competition often keeps lending rates and margins tight. NBFCs, meanwhile, have successfully carved out dominance in specialized retail categories. These areas, including gold loans, used vehicle financing, and affordable housing, require deep local knowledge, specific borrower assessment skills, and localized collections. Because these segments are harder to standardize, NBFCs often face less direct competition from large banks.
What Investors Should Monitor
While the current environment favors NBFCs, the landscape is not without risks. Investors should keep a close watch on two critical metrics. For NBFCs, the primary monitorable is credit costs and the ability to maintain consistent access to affordable funding. Because NBFCs do not have access to retail deposits, any disruption in bond markets can be a liquidity risk. For banks, the focus should remain on the health of their loan books and their ability to attract low-cost deposits, which will ultimately dictate their long-term margin recovery.