

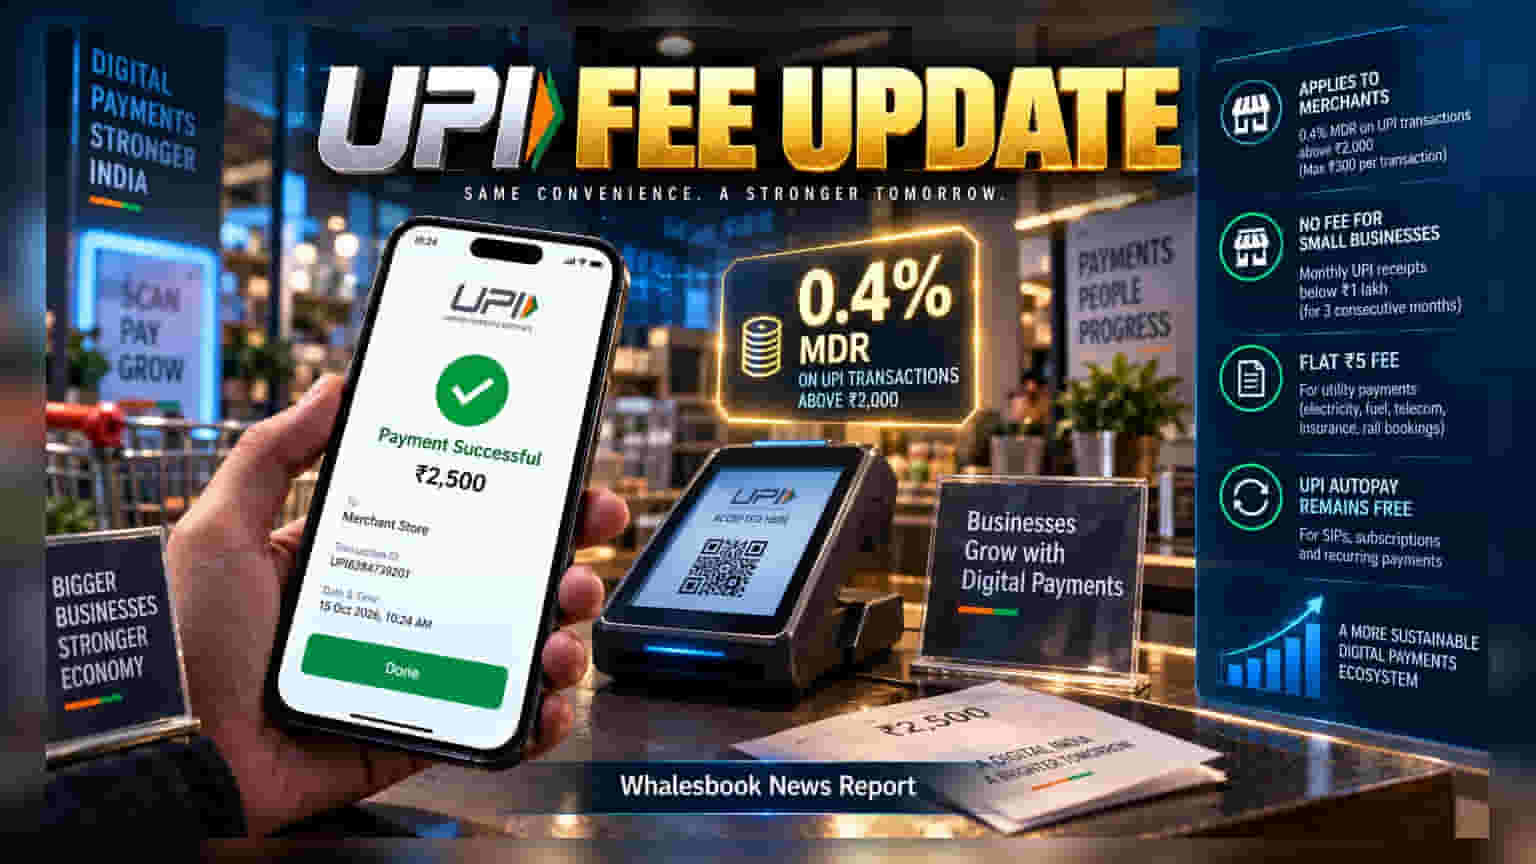
Starting October 15, 2026, businesses will pay a 0.4% Merchant Discount Rate (MDR) on UPI transactions exceeding Rs 2,000. This change addresses the rising operational costs of India's digital payment infrastructure, which currently costs the industry Rs 20,000 crore annually. While individual retail users remain unaffected, the policy marks a significant shift in revenue dynamics for banks and payment service providers.
Starting October 15, 2026, the financial structure of India’s digital payments will change. Merchants will now pay a 0.4% Merchant Discount Rate (MDR) on business-to-consumer (B2C) UPI transactions that exceed Rs 2,000. This fee is capped at a maximum of Rs 300 per transaction, ensuring that the cost does not spiral for very high-ticket items. Small businesses, however, are shielded from this new rule, provided their monthly UPI receipt volumes remain below Rs 1 lakh for three consecutive months.
This decision addresses a long-standing financial gap in the digital payments sector. For years, the industry has absorbed the costs of facilitating billions of monthly UPI transactions. With annual infrastructure operating costs estimated at Rs 20,000 crore and government subsidies falling to Rs 2,000 crore for the 2026-27 fiscal year, banks and payment providers have faced pressure to find a sustainable funding model. By implementing this fee, the system aims to stabilize the infrastructure that supports the country’s high-volume payment traffic.
The impact of this move will be tiered. For utility-based commercial payments—such as electricity bills, fuel, telecommunications, insurance premiums, and rail bookings—the industry is moving to a flat Rs 5 fee regardless of transaction size. Meanwhile, essential features like UPI AutoPay, which handles recurring payments like Systematic Investment Plans (SIPs) and streaming subscriptions, will continue to remain free of charge. This structure appears designed to maintain the mass adoption of digital payments while placing the burden of fees on high-value commercial transactions.
For investors, this shift marks a potential revenue unlock for banks and payment service providers, who have previously seen limited income from the UPI ecosystem. Companies processing payments may benefit from improved margins over time. However, the move creates a challenge for larger retailers, who may see an increase in operational costs. Although merchants are strictly prohibited from passing these costs directly to consumers via surcharges, businesses might look to manage this expense through subtle adjustments in shelf pricing or by nudging customers toward other payment modes like cards or net banking.
Looking ahead, investors should monitor how businesses and consumers react to the new fee structure. A critical point to track is whether large retailers change their payment acceptance strategies to avoid the fee or if transaction patterns show a shift away from UPI for high-ticket purchases. Furthermore, the effectiveness of the government's monitoring to prevent transaction splitting—where a single large purchase is broken into smaller parts to avoid the threshold—will be a key factor in how much total revenue this policy generates for the industry.